
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ASX Growth Stocks With High Insider Ownership To Watch
As the Australian market prepares for a potentially positive opening, driven by gains on Wall Street and a slight easing in oil prices and bond yields, investors are increasingly attentive to sectors beyond the AI trade. In this environment of shifting focus, growth companies with high insider ownership on the ASX present an intriguing opportunity as they often signal confidence from those closest to the business.
Top 10 Growth Companies With High Insider Ownership In Australia
| Name | Insider Ownership | Earnings Growth |
| Wisr (ASX:WZR) | 15.7% | 94.2% |
| Torque Metals (ASX:TOR) | 13.1% | 70.8% |
| Starpharma Holdings (ASX:SPL) | 17.3% | 75.1% |
| SKS Technologies Group (ASX:SKS) | 14.7% | 28.3% |
| PDI Gold (ASX:PDI) | 11.1% | 62.7% |
| Innovaero Technologies (ASX:INN) | 37.9% | 66.2% |
| Forrestania Resources (ASX:FRS) | 24.8% | 72.9% |
| Barton Gold Holdings (ASX:BGD) | 20.8% | 86.7% |
| Austral Resources Australia (ASX:AR1) | 24% | 28.2% |
| Adveritas (ASX:AV1) | 17.6% | 99.9% |
Let's explore several standout options from the results in the screener.
Catapult Sports (ASX:CAT)
Simply Wall St Growth Rating: ★★★★☆☆
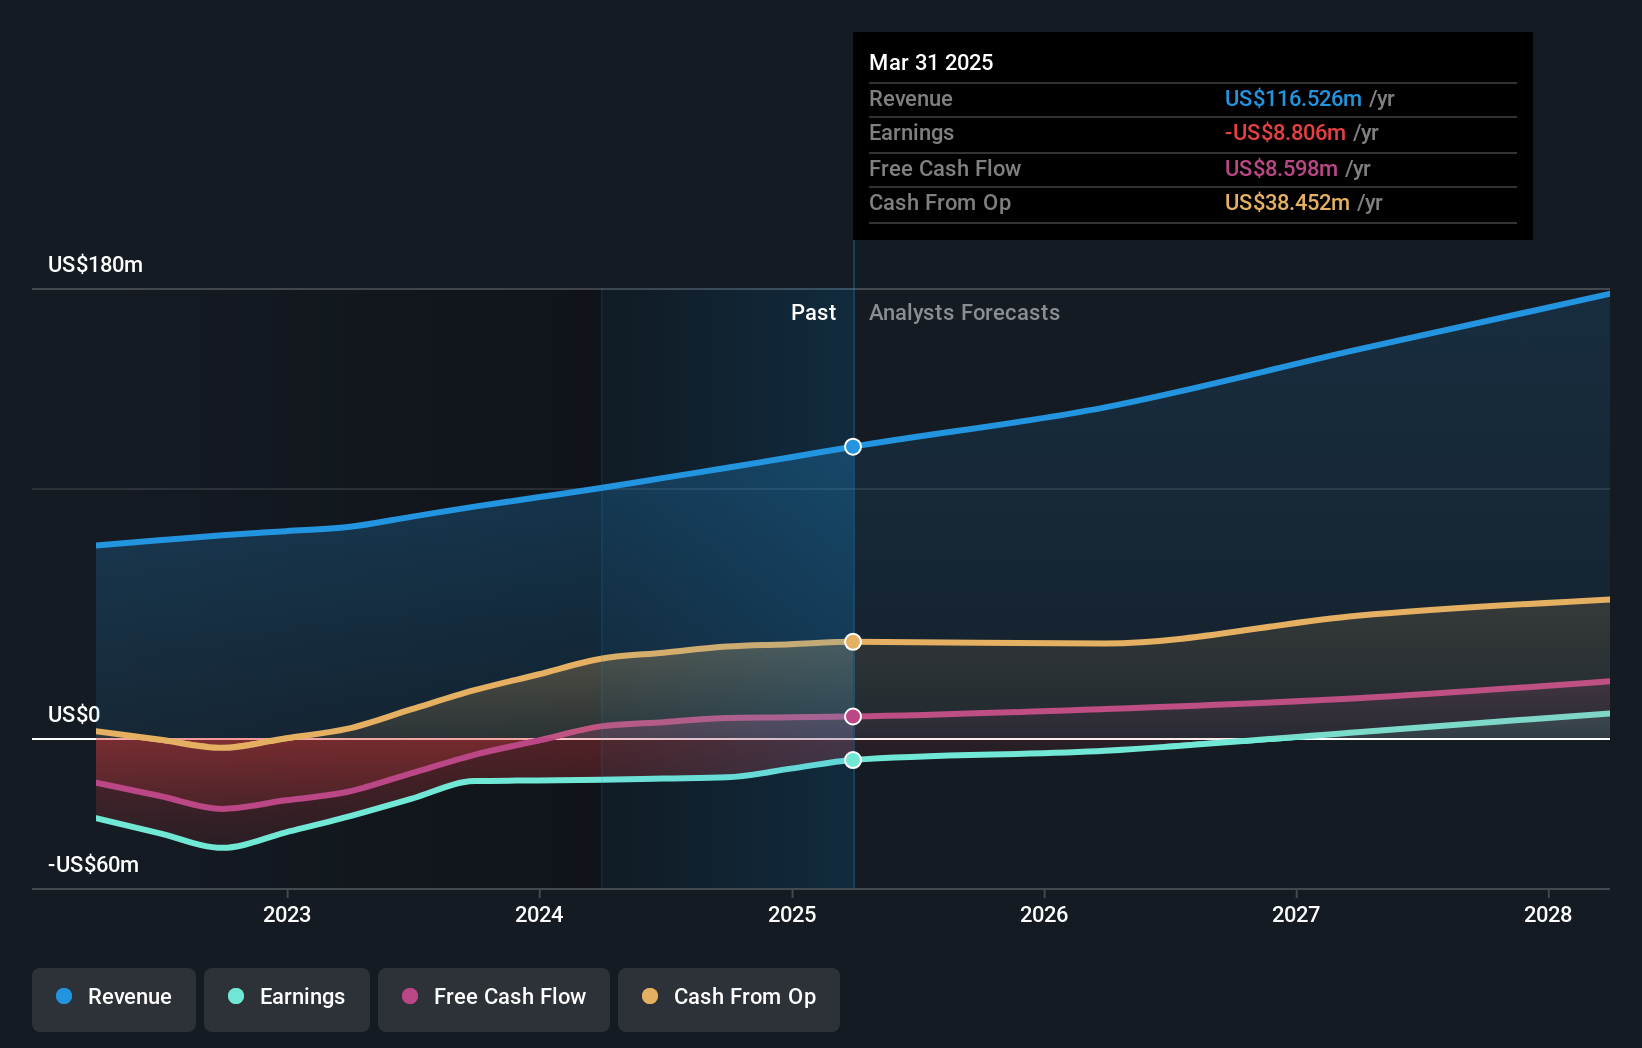
Overview: Catapult Sports Ltd is a sports science and analytics company that develops and supplies technologies to enhance athlete and team performance across multiple regions, with a market cap of A$1.01 billion.
Operations: The company's revenue is derived from three primary segments: Performance & Health ($77.51 million), Tactics & Coaching ($45.55 million), and Media & Other ($17.67 million).
Insider Ownership: 13%
Earnings Growth Forecast: 52% p.a.
Catapult Sports demonstrates potential as a growth company with substantial insider ownership, despite no recent insider trading activity. The company is expected to achieve profitability within three years, with earnings projected to grow at 51.98% annually. While its revenue growth of 13.6% per year surpasses the Australian market average, it remains below the high-growth threshold of 20%. Currently trading at a significant discount to its estimated fair value, Catapult offers an intriguing investment opportunity amidst these dynamics.
- Unlock comprehensive insights into our analysis of Catapult Sports stock in this growth report.
- Upon reviewing our latest valuation report, Catapult Sports' share price might be too optimistic.
MA Financial Group (ASX:MAF)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: MA Financial Group Limited, with a market cap of A$863.60 million, operates in Australia offering a range of financial services through its subsidiaries.
Operations: The company generates revenue from various segments including Asset Management (A$262.16 million), Lending & Technology (A$121.01 million), and Corporate Advisory and Equities (CA&E) (A$67.24 million).
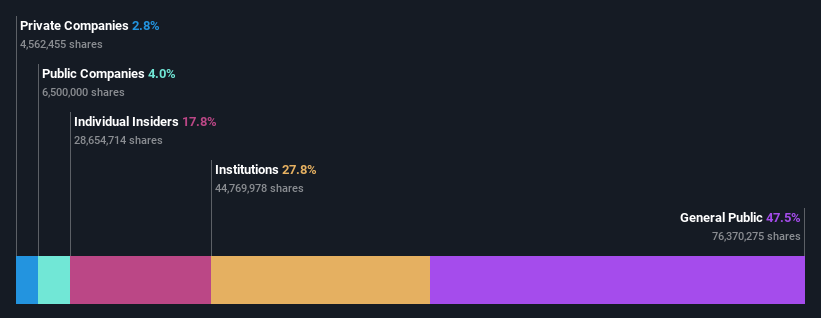
Insider Ownership: 33.4%
Earnings Growth Forecast: 51.8% p.a.
MA Financial Group shows promise with substantial insider buying in recent months, indicating confidence in its growth trajectory. Earnings are forecast to grow significantly at 51.8% annually, despite a projected revenue decline of 37% per year over the next three years. The company's stock trades below estimated fair value by 15.6%, and analysts expect a potential price increase of 99.2%. Recent board changes include appointing Professor David Lloyd, enhancing governance expertise.
- Navigate through the intricacies of MA Financial Group with our comprehensive analyst estimates report here.
- Our comprehensive valuation report raises the possibility that MA Financial Group is priced higher than what may be justified by its financials.
Regis Healthcare (ASX:REG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Regis Healthcare Limited provides aged care services in Australia and has a market cap of A$1.42 billion.
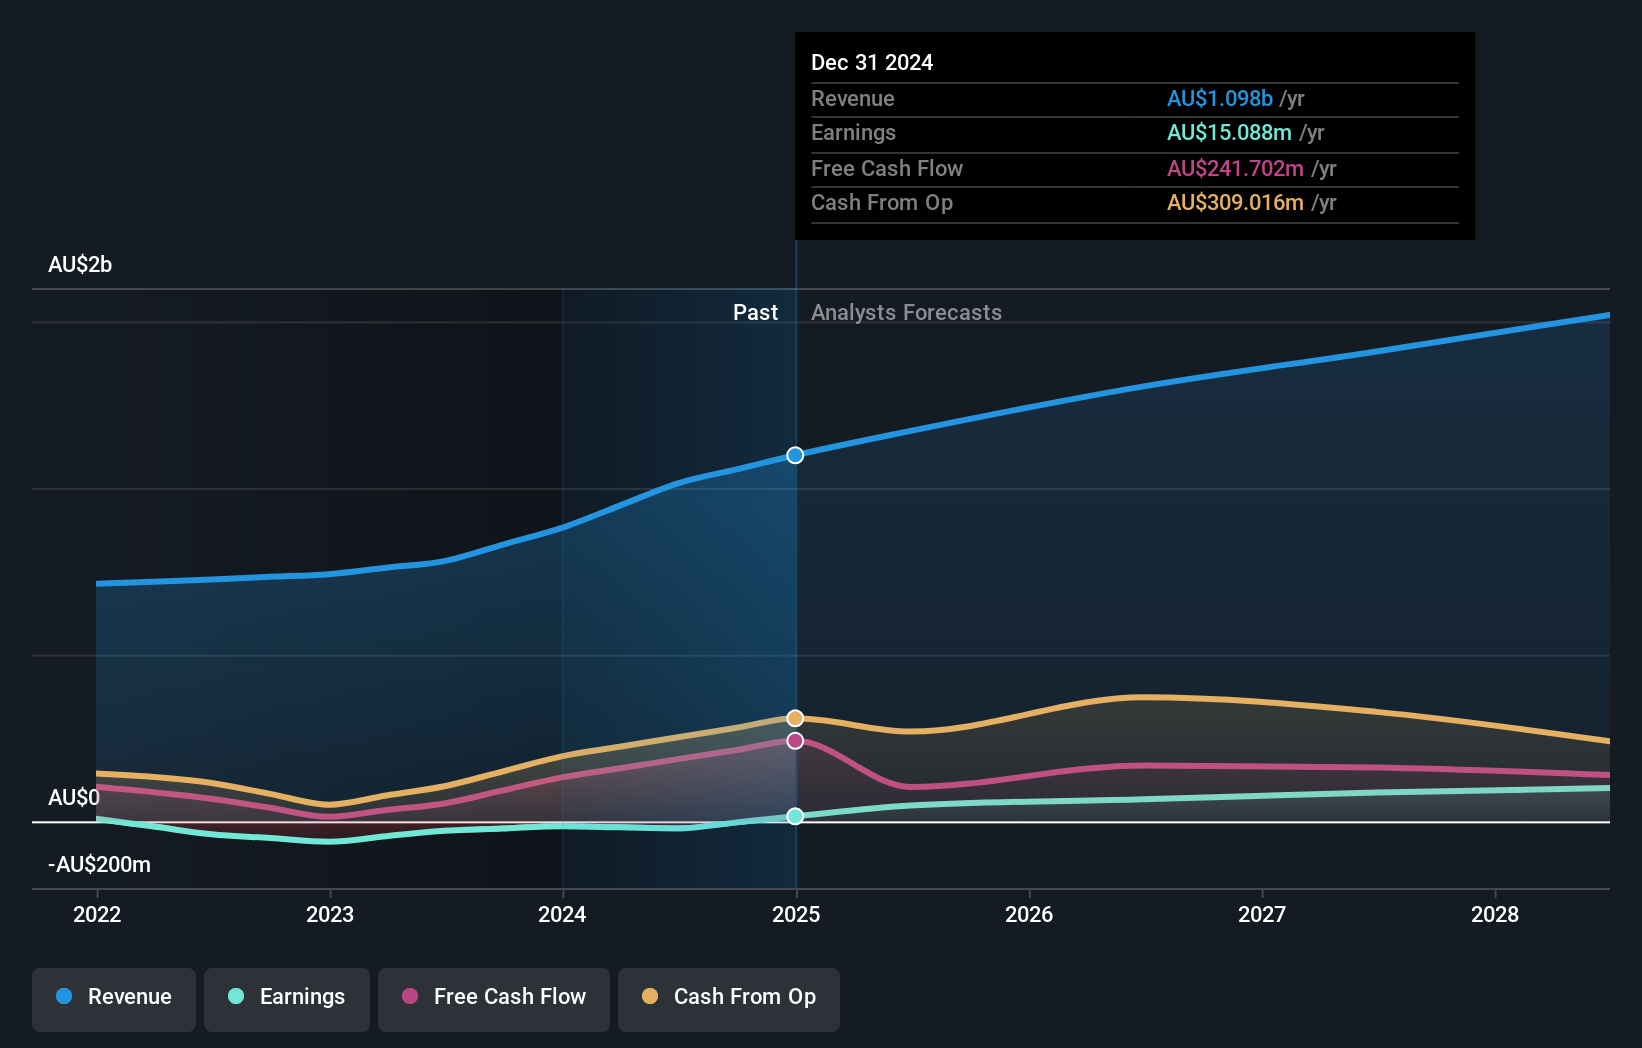
Operations: Regis Healthcare Limited generates revenue of A$1.35 billion from its residential aged care, home care, and retirement living services in Australia.
Insider Ownership: 38.7%
Earnings Growth Forecast: 11.8% p.a.
Regis Healthcare demonstrates growth potential with substantial insider buying, reflecting confidence in its future. The company is trading significantly below its estimated fair value and analysts anticipate a 29.8% price increase. Revenue and earnings are forecast to grow faster than the Australian market at 6.2% and 11.8% annually, respectively, despite a dividend not well covered by earnings. Recent strategic moves include seeking acquisitions to enhance growth and appointing a new CFO with extensive industry experience.
- Click here to discover the nuances of Regis Healthcare with our detailed analytical future growth report.
- The valuation report we've compiled suggests that Regis Healthcare's current price could be quite moderate.
Summing It All Up
- Reveal the 120 hidden gems among our Fast Growing ASX Companies With High Insider Ownership screener with a single click here.
- Seeking Other Investments? The end of cancer? These 38 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com