
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Stocks Estimated To Be Undervalued By Up To 49.2%
In the last week, the United States market has stayed flat, but it is up 12% over the past year with earnings forecast to grow by 17% annually. In such a climate, identifying undervalued stocks can be advantageous as they might offer potential for growth relative to their current price levels.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zions Bancorporation National Association (ZION) | $64.59 | $123.74 | 47.8% |
| Sociedad Química y Minera de Chile (SQM) | $60.05 | $118.57 | 49.4% |
| MYR Group (MYRG) | $274.80 | $528.27 | 48% |
| Futu Holdings (FUTU) | $105.51 | $207.17 | 49.1% |
| First Solar (FSLR) | $174.43 | $332.12 | 47.5% |
| FB Financial (FBK) | $52.25 | $103.32 | 49.4% |
| Civista Bancshares (CIVB) | $26.91 | $53.30 | 49.5% |
| Best Buy (BBY) | $93.89 | $187.33 | 49.9% |
| Artisan Partners Asset Management (APAM) | $32.96 | $64.84 | 49.2% |
| Addus HomeCare (ADUS) | $118.03 | $226.18 | 47.8% |
Below we spotlight a couple of our favorites from our exclusive screener.
Artisan Partners Asset Management (APAM)
Overview: Artisan Partners Asset Management Inc. is a publicly owned investment manager with a market cap of approximately $2.60 billion.
Operations: The company's revenue is primarily derived from its Investment Management Industry segment, which generated approximately $1.25 billion.
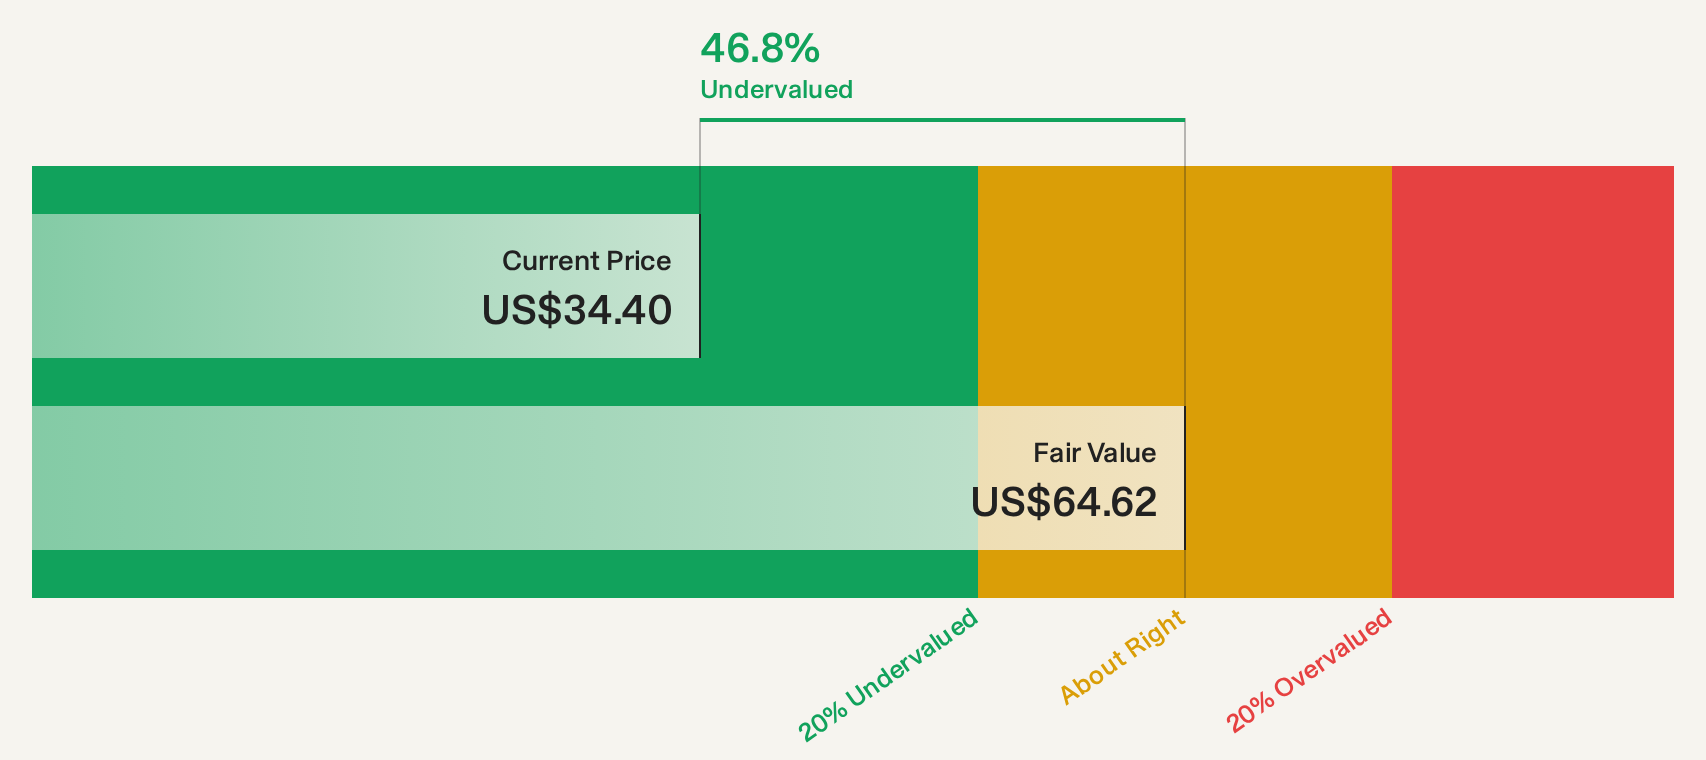
Estimated Discount To Fair Value: 49.2%
Artisan Partners Asset Management is trading at US$32.96, significantly below its estimated future cash flow value of US$64.84, indicating it may be undervalued based on cash flows. Despite recent earnings growth with net income rising to US$80.9 million in Q2 2026 from US$67.6 million a year ago, revenue is expected to decline slightly over the next three years and dividend coverage by free cash flows remains weak.
- Insights from our recent growth report point to a promising forecast for Artisan Partners Asset Management's business outlook.
- Navigate through the intricacies of Artisan Partners Asset Management with our comprehensive financial health report here.
Atlantic Union Bankshares (AUB)
Overview: Atlantic Union Bankshares Corporation is the bank holding company for Atlantic Union Bank, offering a range of banking and financial services to consumers and businesses in the United States, with a market cap of approximately $5.39 billion.
Operations: The company's revenue is primarily derived from Consumer Banking, which accounts for $510.22 million, and Wholesale Banking, contributing $755.09 million.
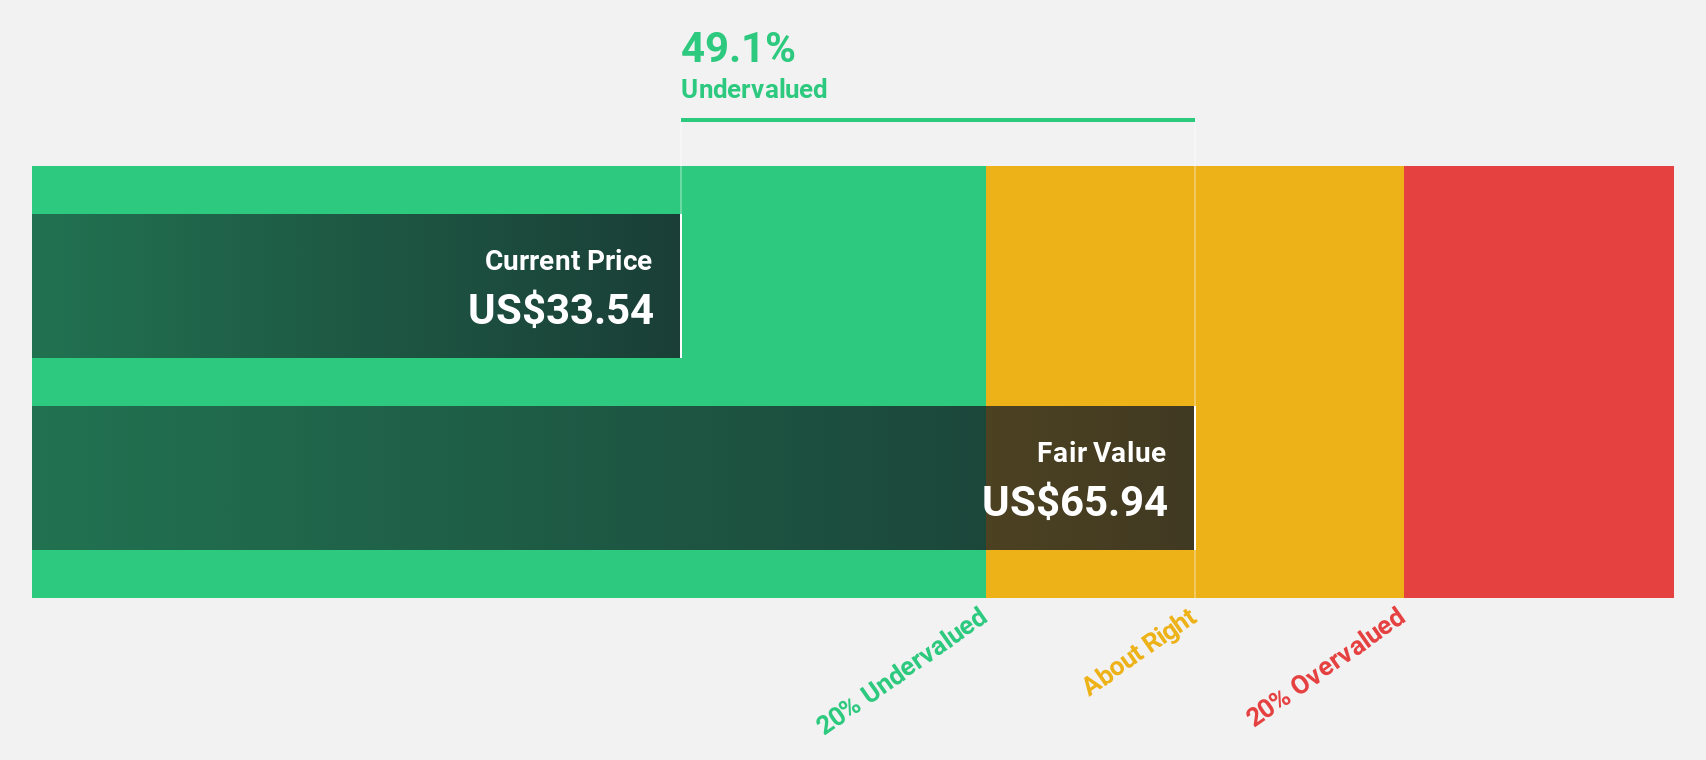
Estimated Discount To Fair Value: 40.2%
Atlantic Union Bankshares, trading at US$38.21, is significantly below its estimated future cash flow value of US$63.92, highlighting potential undervaluation based on cash flows. Recent earnings results show strong performance with net income rising to US$136.63 million in Q3 2026 from US$92.14 million a year ago, though revenue growth forecasts remain modest at 4.8% annually. The company maintains a reliable dividend yield of 3.87% and has been actively repurchasing shares to enhance shareholder value.
- Upon reviewing our latest growth report, Atlantic Union Bankshares' projected financial performance appears quite optimistic.
- Take a closer look at Atlantic Union Bankshares' balance sheet health here in our report.
F.N.B (FNB)
Overview: F.N.B. Corporation is a bank and financial holding company offering diverse financial products and services to consumers, corporations, governments, and small- to medium-sized businesses in the United States with a market cap of approximately $5.95 billion.
Operations: The company's revenue segments include interest income from loans and leases, investment securities, and other financial services provided to a diverse clientele in the United States.
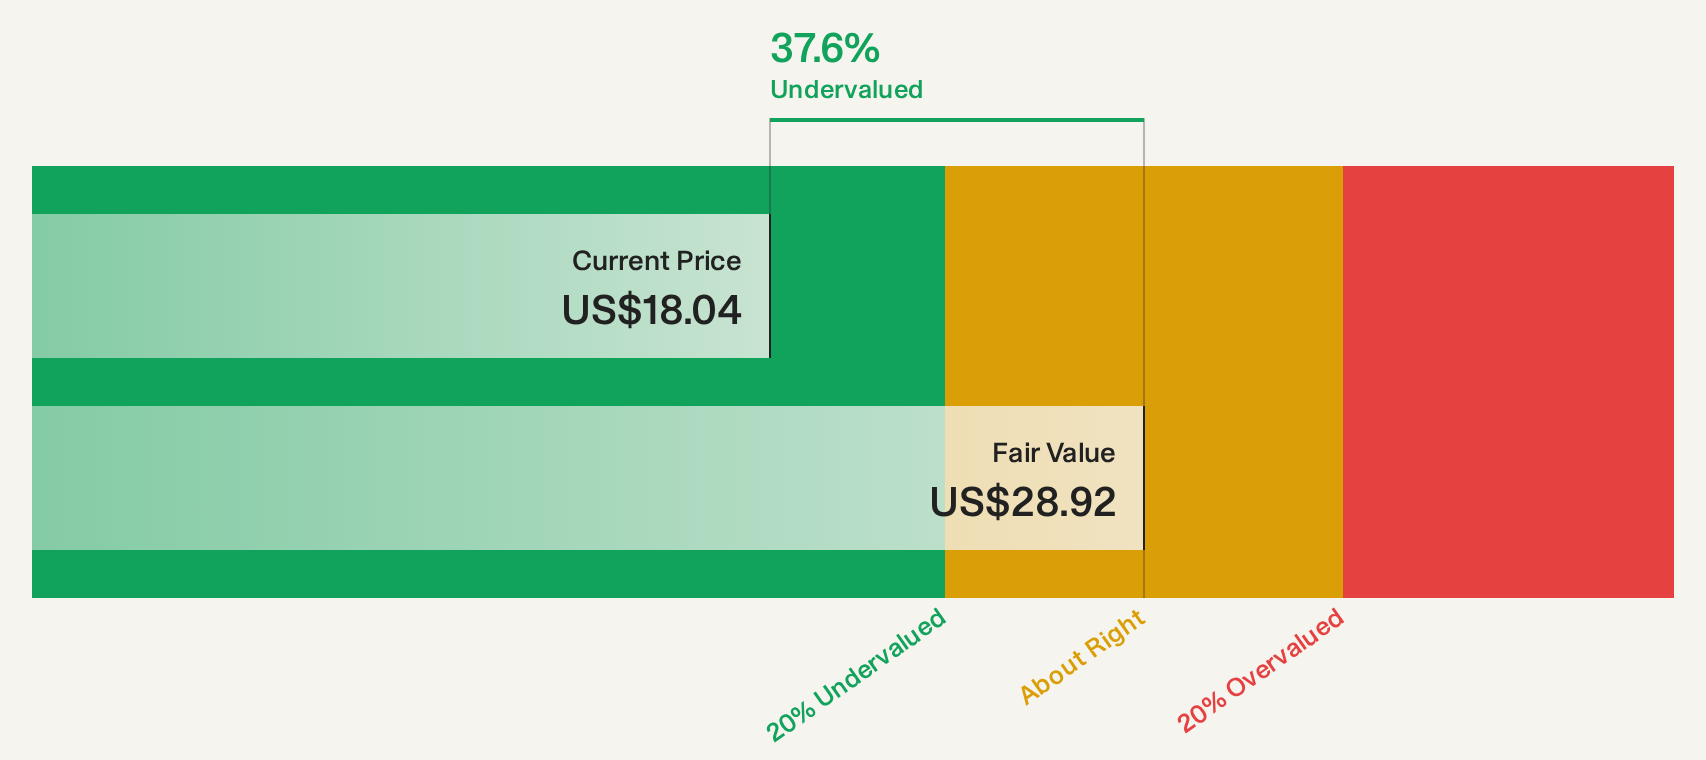
Estimated Discount To Fair Value: 38.8%
F.N.B. Corporation, priced at US$17.66, is trading well below its estimated future cash flow value of US$28.88, suggesting significant undervaluation based on cash flows. Recent earnings show net interest income for Q3 2026 increased to US$376.52 million from US$359.27 million a year ago, while net income rose to US$152.86 million from US$149.51 million last year. The company offers a steady dividend yield of 2.94% amidst slower revenue growth forecasts of 6.8% annually.
- The analysis detailed in our F.N.B growth report hints at robust future financial performance.
- Dive into the specifics of F.N.B here with our thorough financial health report.
Seize The Opportunity
- Dive into all 94 of the Undervalued US Stocks Based On Cash Flows we have identified here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com