
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Undervalued Small Caps With Insider Activity To Watch Closely
Over the last 7 days, the United States market has remained flat, yet it has shown a 12% rise over the past year, with earnings projected to grow by 17% annually in the coming years. In this context of steady growth and positive outlooks, identifying small-cap stocks that are undervalued and exhibit insider activity can offer intriguing opportunities for investors seeking potential value plays.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.7x | 0.5x | 29.83% | ★★★★★★ |
| Financial Institutions | 9.7x | 3.2x | 24.50% | ★★★★★☆ |
| Enovis | NA | 0.5x | 38.29% | ★★★★★☆ |
| Bank of Marin Bancorp | NA | 7.1x | 33.44% | ★★★★☆☆ |
| Union Bankshares | 9.4x | 2.0x | 45.49% | ★★★★☆☆ |
| Surgery Partners | NA | 0.6x | 19.86% | ★★★★☆☆ |
| Tilray Brands | NA | 0.5x | 9.45% | ★★★★☆☆ |
| German American Bancorp | 13.3x | 5.0x | 24.68% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.5x | 2.6x | 8.23% | ★★★☆☆☆ |
| Orion Group Holdings | 97.8x | 0.4x | 48.22% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
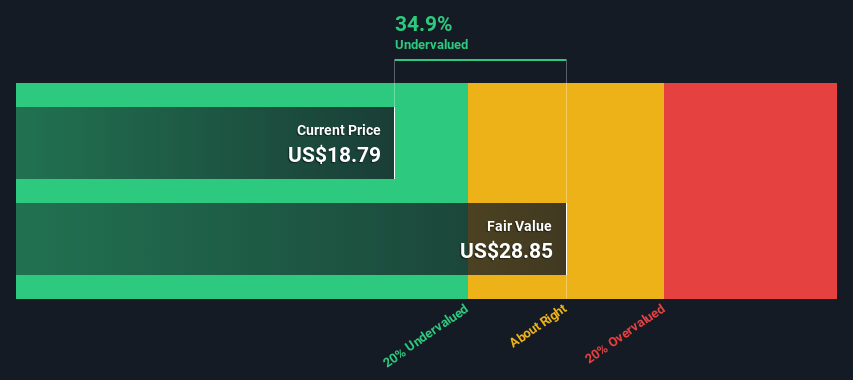
Alerus Financial (ALRS)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Alerus Financial operates as a diversified financial services company, providing banking, wealth advisory, and retirement and benefit services with a market cap of $0.41 billion.
Operations: Alerus Financial generates revenue primarily through its Banking, Wealth Advisory, and Retirement and Benefit Services segments. The company has experienced fluctuations in net income margin, reaching as high as 22.17% in early 2021 before declining to 1.93% by late 2024. Operating expenses are a significant component of the cost structure, with General & Administrative expenses consistently being one of the largest expense categories over time.
PE: 28.5x
Alerus Financial, a smaller company in the U.S., is catching attention with its earnings projected to grow by 29.06% annually. Recent insider confidence is evident as they initiated a share repurchase program valid until August 2029, having already bought back 500,000 shares for US$12.56 million by June 2026. The company also filed a US$200 million shelf registration and increased its dividend by 4.76%, signaling financial health and potential growth opportunities ahead.
- Click here to discover the nuances of Alerus Financial with our detailed analytical valuation report.
Examine Alerus Financial's past performance report to understand how it has performed in the past.
CPI Card Group (PMTS)
Simply Wall St Value Rating: ★★★★★☆
Overview: CPI Card Group is a payment technology company that provides comprehensive financial card solutions and related services, with a market cap of approximately $0.41 billion.
Operations: The company generates revenue primarily from Prepaid Solutions and a significant Segment Adjustment, totaling $589.21 million. A notable trend is the gross profit margin, which has seen fluctuations over the years, reaching 30.54% in mid-2026. Operating expenses have consistently been a significant portion of costs, with general and administrative expenses being a substantial component.
PE: 22.8x
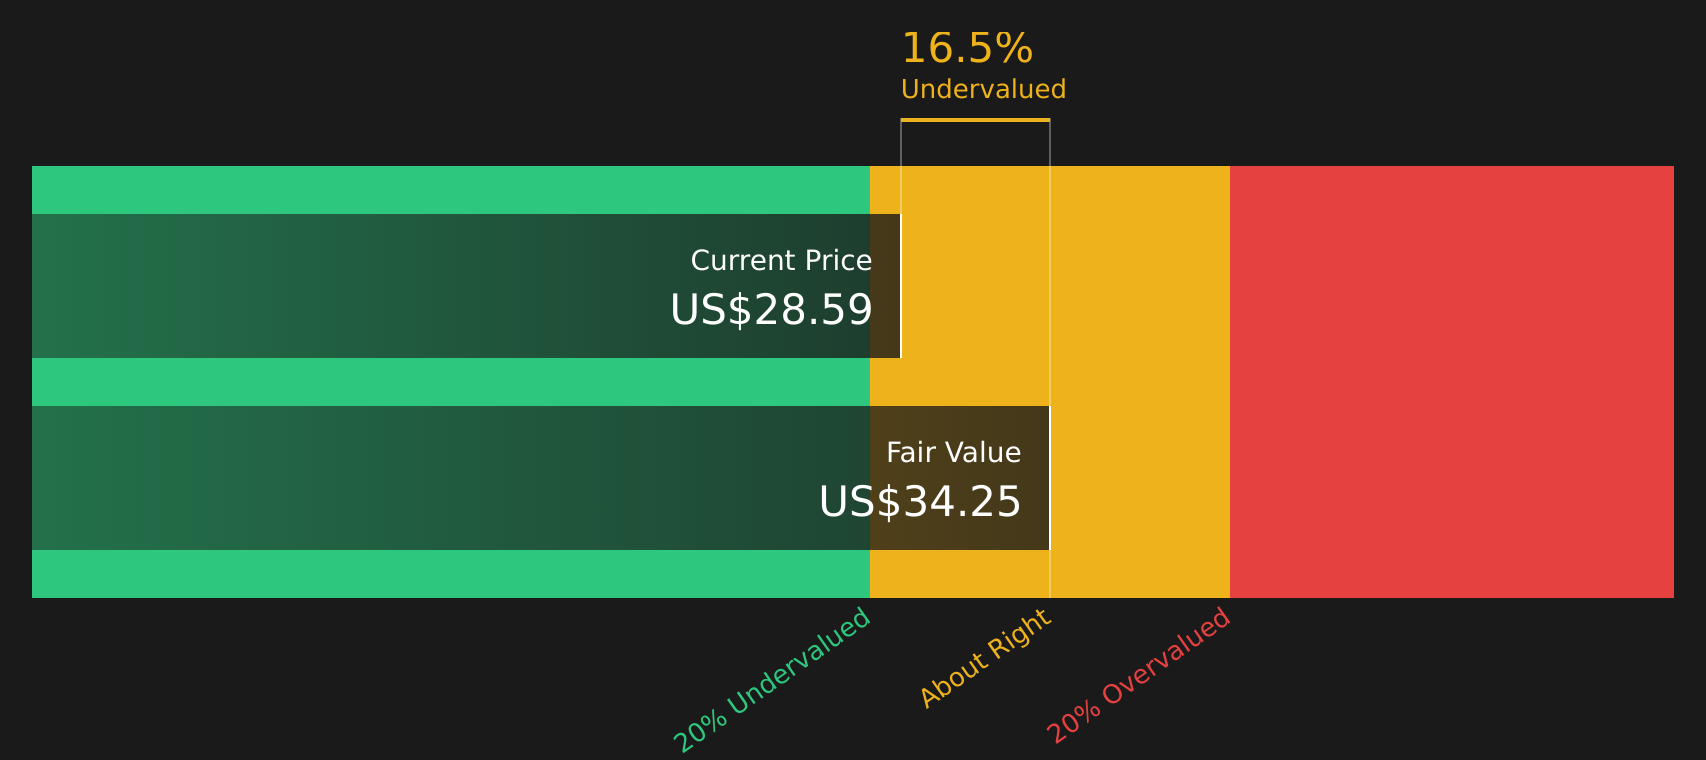
CPI Card Group, a player in the payment solutions industry, is drawing attention with its recent strategic moves and financial performance. The company renewed a multi-year agreement with Vericast and partnered with Bankjoy to enhance digital wallet integration, highlighting its commitment to innovation. Despite having negative shareholders' equity and relying on external borrowing for funding, CPI's earnings are projected to grow significantly at 46.84% annually. Recent follow-on equity offerings raised US$50 million, potentially strengthening its financial position amidst insider confidence shown by share purchases earlier this year.
- Unlock comprehensive insights into our analysis of CPI Card Group stock in this valuation report.
Explore historical data to track CPI Card Group's performance over time in our Past section.
Kura Oncology (KURA)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Kura Oncology focuses on the discovery and development of precision medicines for cancer treatment, with a market cap of approximately $0.67 billion.
Operations: Kura Oncology's revenue primarily comes from the discovery and development of precision medicines, with recent figures showing $77.23 million in this segment. The company has consistently reported no revenue until late 2024, while incurring substantial costs related to research and development (R&D) and general and administrative expenses. R&D expenses have shown a notable increase over the years, reaching $105.37 million by September 2023. Gross profit margins have been negative, reflecting higher costs of goods sold compared to revenues in recent periods.
PE: -3.0x
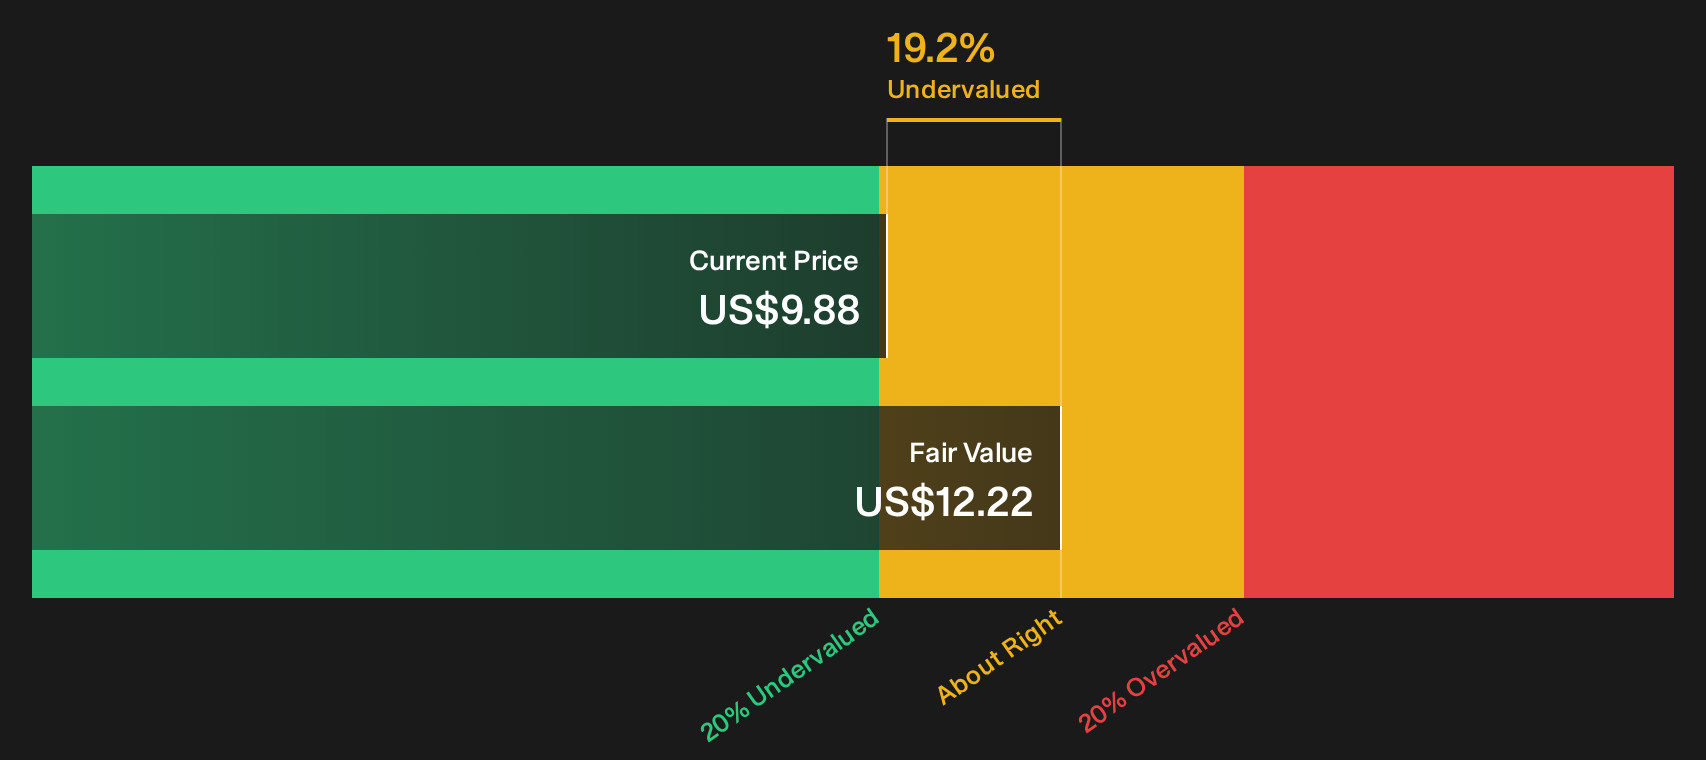
Kura Oncology, a small-cap biotech firm, is drawing attention with its promising menin inhibitor KO-7246. Recent preclinical data suggest it could revolutionize diabetes treatment by enhancing ß-cell mass and insulin production without hypoglycemia risk. Despite current unprofitability and reliance on external borrowing, the company forecasts significant revenue growth at 46.82% annually. Insider confidence is evident as insiders have increased their shareholdings over the past year, underscoring potential future value in Kura's innovative pipeline and strategic partnerships.
- Take a closer look at Kura Oncology's potential here in our valuation report.
Assess Kura Oncology's past performance with our detailed historical performance reports.
Turning Ideas Into Actions
- Explore the 67 names from our Undervalued US Small Caps With Insider Buying screener here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com