
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Discover These 3 Undervalued Small Caps With Insider Action In Global Markets
In recent weeks, global markets have experienced a notable shift as investors move away from large-cap growth stocks, driven by concerns over AI spending and inflation pressures. This has led to increased interest in small-cap stocks, particularly those with value-oriented characteristics and insider activity. In the current market environment, identifying promising small-cap opportunities involves looking for companies that demonstrate strong fundamentals and potential resilience amid economic fluctuations.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.4x | 0.2x | 46.58% | ★★★★★☆ |
| Timbercreek Financial | 16.7x | 9.7x | 38.66% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.9x | 0.9x | 39.24% | ★★★★★☆ |
| Centurion | 15.6x | 3.0x | 21.09% | ★★★★☆☆ |
| Transcontinental | 2.7x | 0.2x | -108.41% | ★★★★☆☆ |
| Diversified Royalty | 24.9x | 9.9x | 47.75% | ★★★★☆☆ |
| Franchise Brands | 27.2x | 2.0x | 47.62% | ★★★★☆☆ |
| MCAN Mortgage | 10.4x | 5.9x | -9.32% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -228.06% | ★★★☆☆☆ |
| Linc | 12.0x | 12.5x | 34.87% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
Craneware (AIM:CRW)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Craneware is a healthcare software company that specializes in providing solutions to improve financial and operational performance within the healthcare industry, with a market capitalization of approximately £0.45 billion.
Operations: The company's primary revenue stream is from its healthcare software segment, with a recent gross profit margin of 83.93%. Operating expenses are significant, primarily driven by general and administrative costs. The net income margin stands at 9.58%, reflecting the impact of these expenses on profitability.
PE: 25.3x
Craneware, a company with a volatile share price over the past three months, reported steady financial performance for the year ending June 30, 2026. Sales reached US$205.96 million with net income at US$19.73 million. Insider confidence is evident as Keith Neilson acquired 9,074 shares valued at approximately £100K in recent months. Despite relying on external borrowing for funding, Craneware maintains consistent dividends and anticipates reporting Q1 2027 results soon, signaling potential stability ahead.
- Click to explore a detailed breakdown of our findings in Craneware's valuation report.
Understand Craneware's track record by examining our Past report.
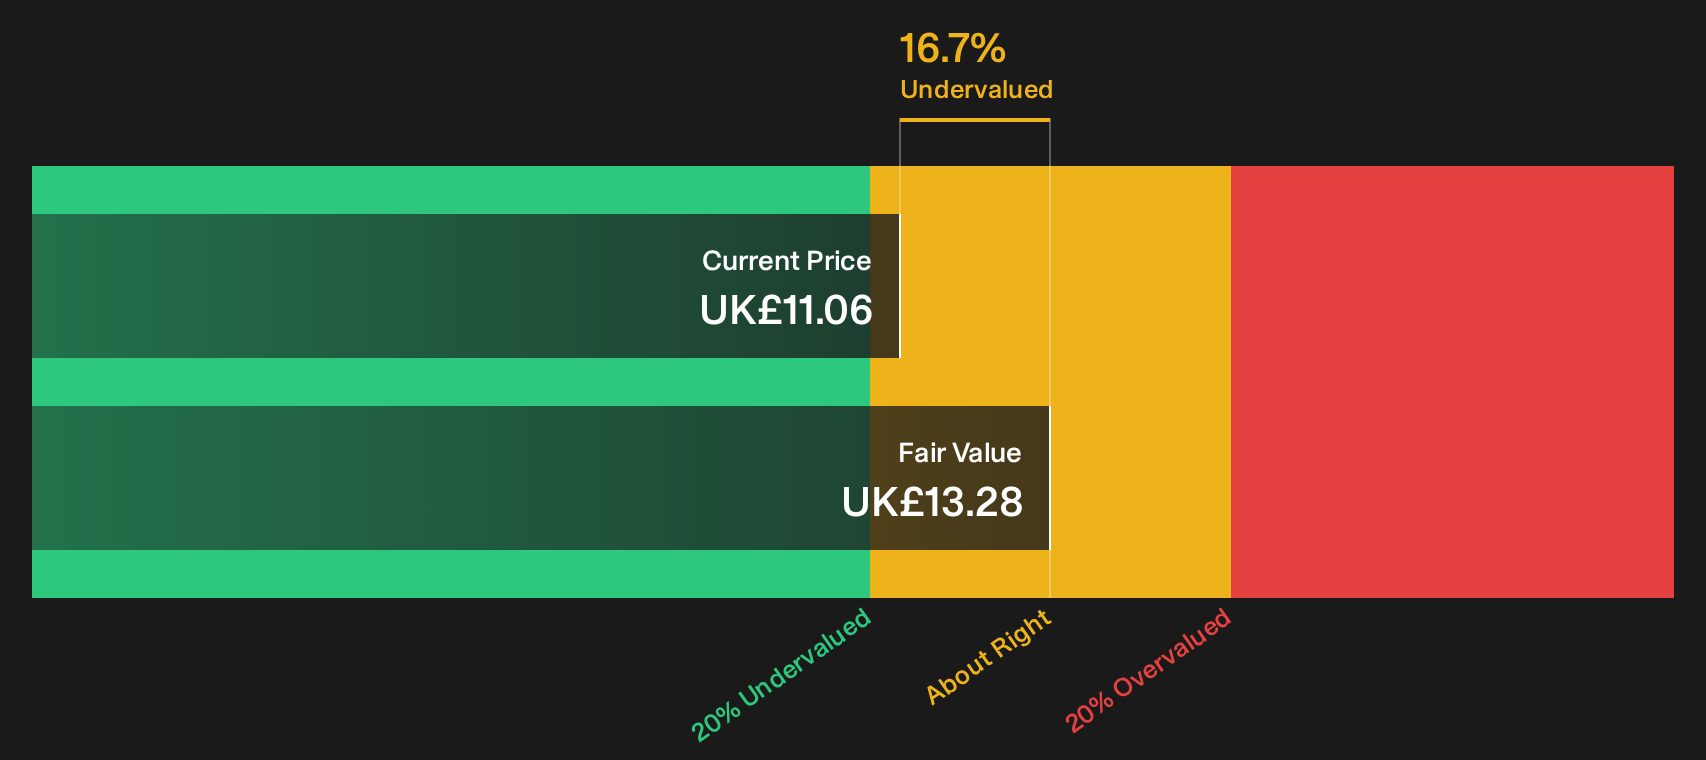
Ingenia Communities Group (ASX:INA)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Ingenia Communities Group is a company that operates in the real estate sector, focusing on holiday and lifestyle communities, with a market capitalization of A$1.89 billion.
Operations: Ingenia Communities Group generates revenue primarily from its Residential - Lifestyle Development and Tourism - Ingenia Holidays segments, contributing significantly to its overall income. The company has seen fluctuations in its gross profit margin, reaching a peak of 64.87% in September 2022 before adjusting to 61.72% by June 2026. Operating expenses have consistently increased over time, impacting net income margins which varied from a high of 32.35% in June 2026 to lower levels such as 3.01% in June 2024 due to rising costs and non-operating expenses during certain periods.
PE: 10.0x
Ingenia Communities Group, a company with a strong earnings record, reported A$559.88 million in revenue for the year ending June 2026, up from A$517.7 million previously. Despite external borrowing as their sole funding source, they maintain a solid financial position with debt well-supported by operating cash flow. Insider confidence is evident through share purchases over recent months, indicating potential growth prospects. The recent rejection of Warburg Pincus's A$5.25 per share proposal underscores Ingenia's perceived value and future potential amidst ongoing negotiations.

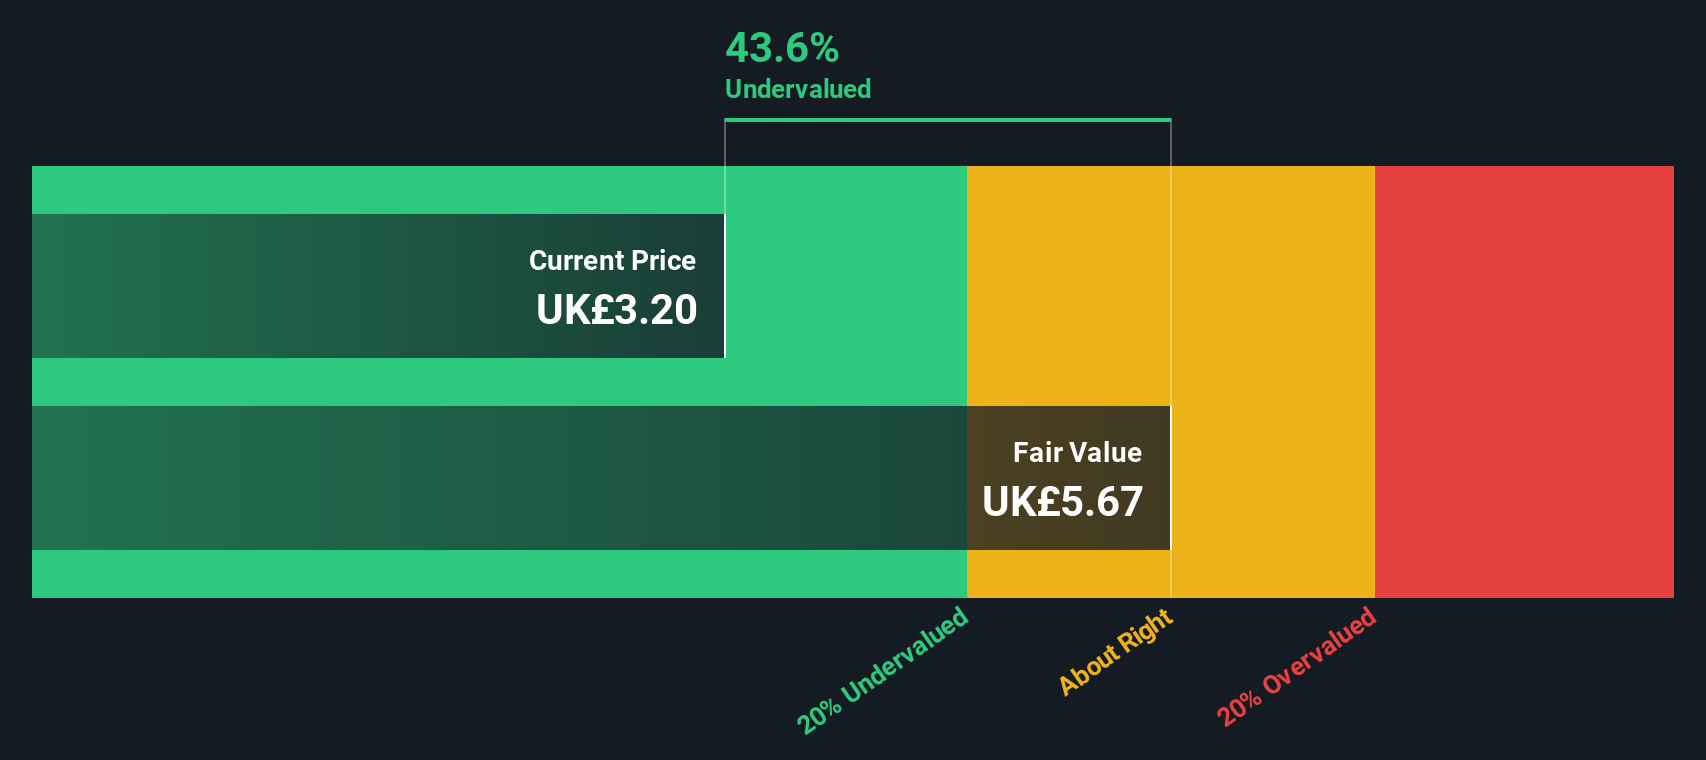
LSL Property Services (LSE:LSL)
Simply Wall St Value Rating: ★★★★★☆
Overview: LSL Property Services operates in the UK, providing financial services, surveying and valuation, and estate agency services with a market cap of approximately £0.28 billion.
Operations: The company generates revenue primarily from three segments: Financial Services (£48.19 million), Surveying and Valuation (£110.70 million), and Estate Agency (£26.70 million). Over recent years, the net income margin has shown variability, with notable fluctuations such as a peak of 18.95% in late 2021 and a dip to -16.02% in mid-2023, indicating shifts in profitability amidst changing operating conditions.
PE: 14.8x
LSL Property Services, a smaller company in the property sector, recently reported improved half-year earnings with sales at £92.31 million and net income of £8.61 million. The company's financial health is highlighted by insider confidence; their CFO purchased 46,205 shares valued at approximately £99,479. Despite relying solely on external borrowing for funding, LSL's earnings are projected to grow annually by nearly 12%. Their inclusion in the S&P Global BMI Index further underscores potential growth opportunities ahead.
Summing It All Up
- Unlock our comprehensive list of 120 Undervalued Global Small Caps With Insider Buying by clicking here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com