
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Discovering Global Undiscovered Gems This October 2026
As global markets navigate the pressures of AI spending concerns and inflationary trends, small-cap stocks have shown resilience amid a rotation from large-cap growth to value-oriented segments. With the Russell 2000 Index experiencing a recent decline, investors may find opportunities in lesser-known companies that exhibit strong fundamentals and potential for growth despite broader market volatility.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Silvery Dragon Group Tianjin | 25.01% | 2.55% | 25.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
| Bastide Le Confort Médical | 263.37% | 2.00% | -22.93% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
Angler Gaming (DB:0QM)
Simply Wall St Value Rating: ★★★★★★
Overview: Angler Gaming plc invests in companies providing online gaming services in Malta, with a market capitalization of €416.92 million.
Operations: The company generates revenue primarily from iGaming activities, amounting to €32.50 million.
Angler Gaming, a nimble player in the market, has shown impressive growth with earnings surging 271% over the past year, outpacing the Hospitality industry's 58.9%. The company reported EUR 8.45 million in sales for Q2 2026, up from EUR 6.64 million last year, and net income rose to EUR 2.38 million from EUR 0.47 million. Trading at a significant discount of around 85% below estimated fair value suggests potential upside for investors seeking undervalued opportunities. Despite its volatile share price recently, Angler Gaming's debt-free status and positive free cash flow position it well for future growth prospects.
- Click here and access our complete health analysis report to understand the dynamics of Angler Gaming.
Assess Angler Gaming's past performance with our detailed historical performance reports.

Selçuk Ecza Deposu Ticaret ve Sanayi (IBSE:SELEC)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Selçuk Ecza Deposu Ticaret ve Sanayi A.S., along with its subsidiary, functions as a pharmacy depot in Turkey and has a market capitalization of TRY36.67 billion.
Operations: The primary revenue stream for Selçuk Ecza is its wholesale drug segment, which generated TRY180.82 billion. The company's financial performance can be evaluated through its net profit margin, which was 2.53%.
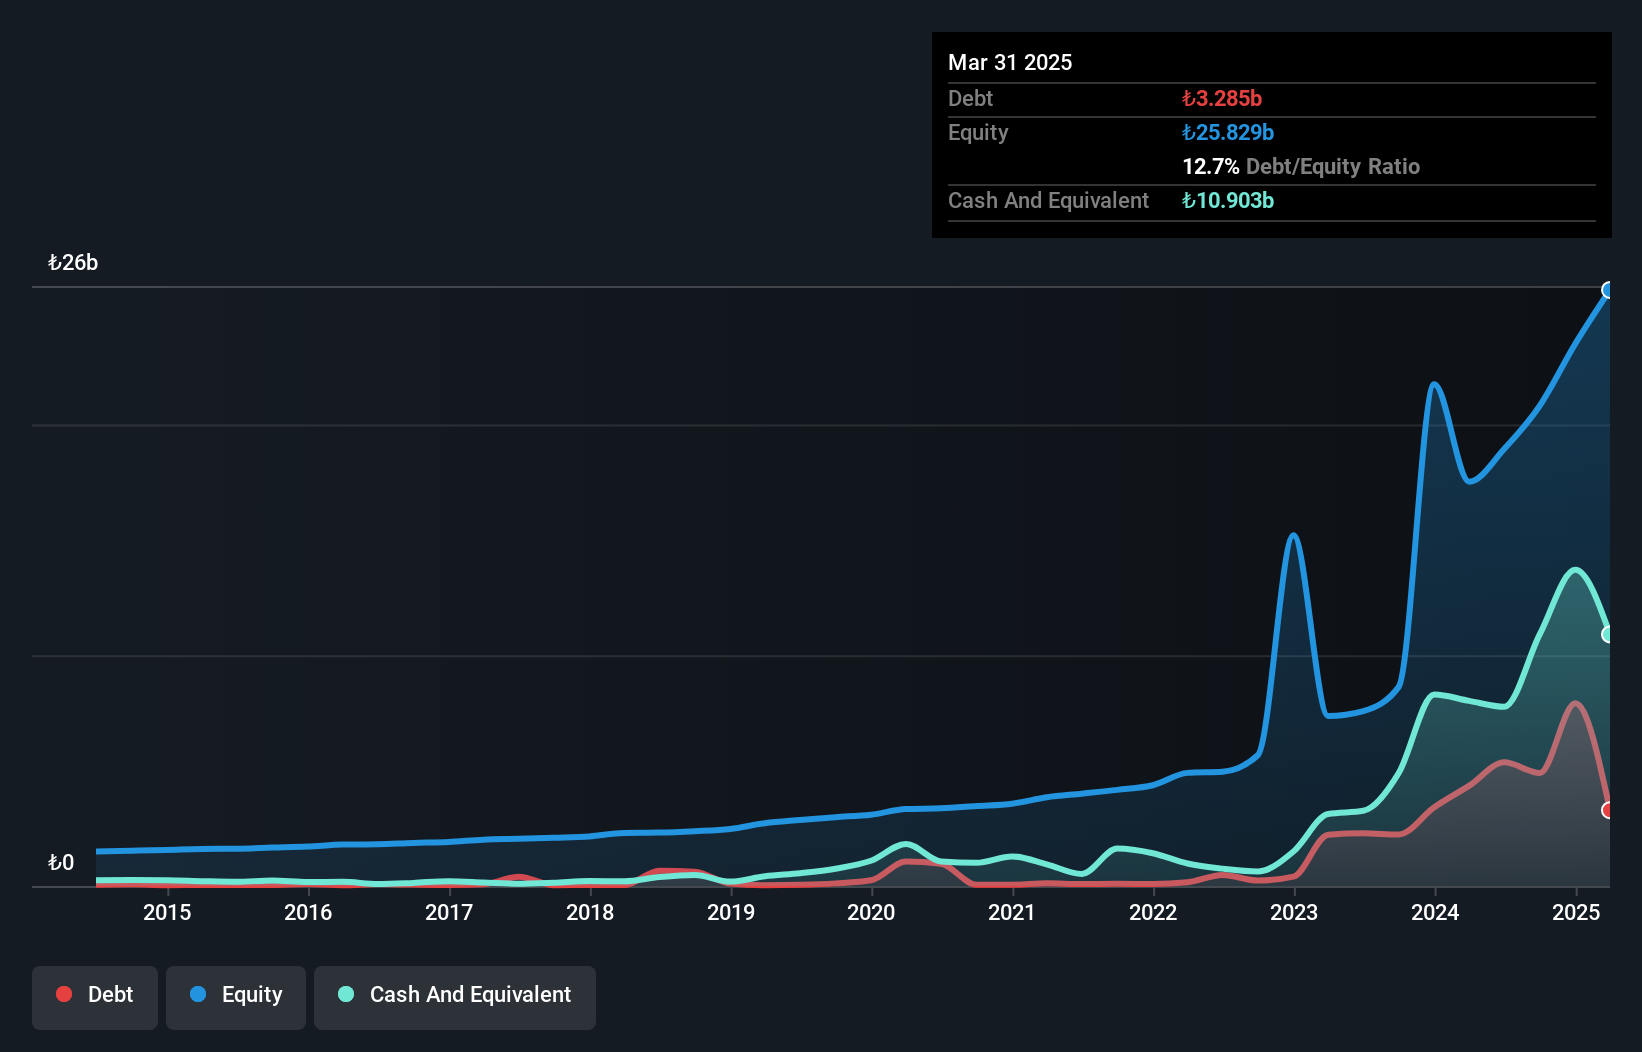
Selçuk Ecza, a notable player in the healthcare sector, showcases impressive growth with earnings up by 31.5% over the past year, outpacing the industry’s -21.6%. The company turned a corner with net income reaching TRY 534.39 million in Q2 2026 from a loss of TRY 424.71 million previously, and sales climbing to TRY 53,439.93 million from TRY 47,699.48 million last year. Despite its debt-to-equity ratio rising to 16.1% over five years, it holds more cash than total debt and trades at an estimated fair value discount of 54.8%, suggesting potential for value investors seeking opportunities in smaller companies within this space.
Scales (NZSE:SCL)
Simply Wall St Value Rating: ★★★★★☆
Overview: Scales Corporation Limited is involved in the manufacturing and trading of food ingredients across New Zealand, Asia, Europe, North America, and other international markets, with a market capitalization of approximately NZ$949.83 million.
Operations: Scales generates revenue primarily from its Global Proteins and Horticulture segments, contributing NZ$843.86 million and NZ$371.98 million, respectively.
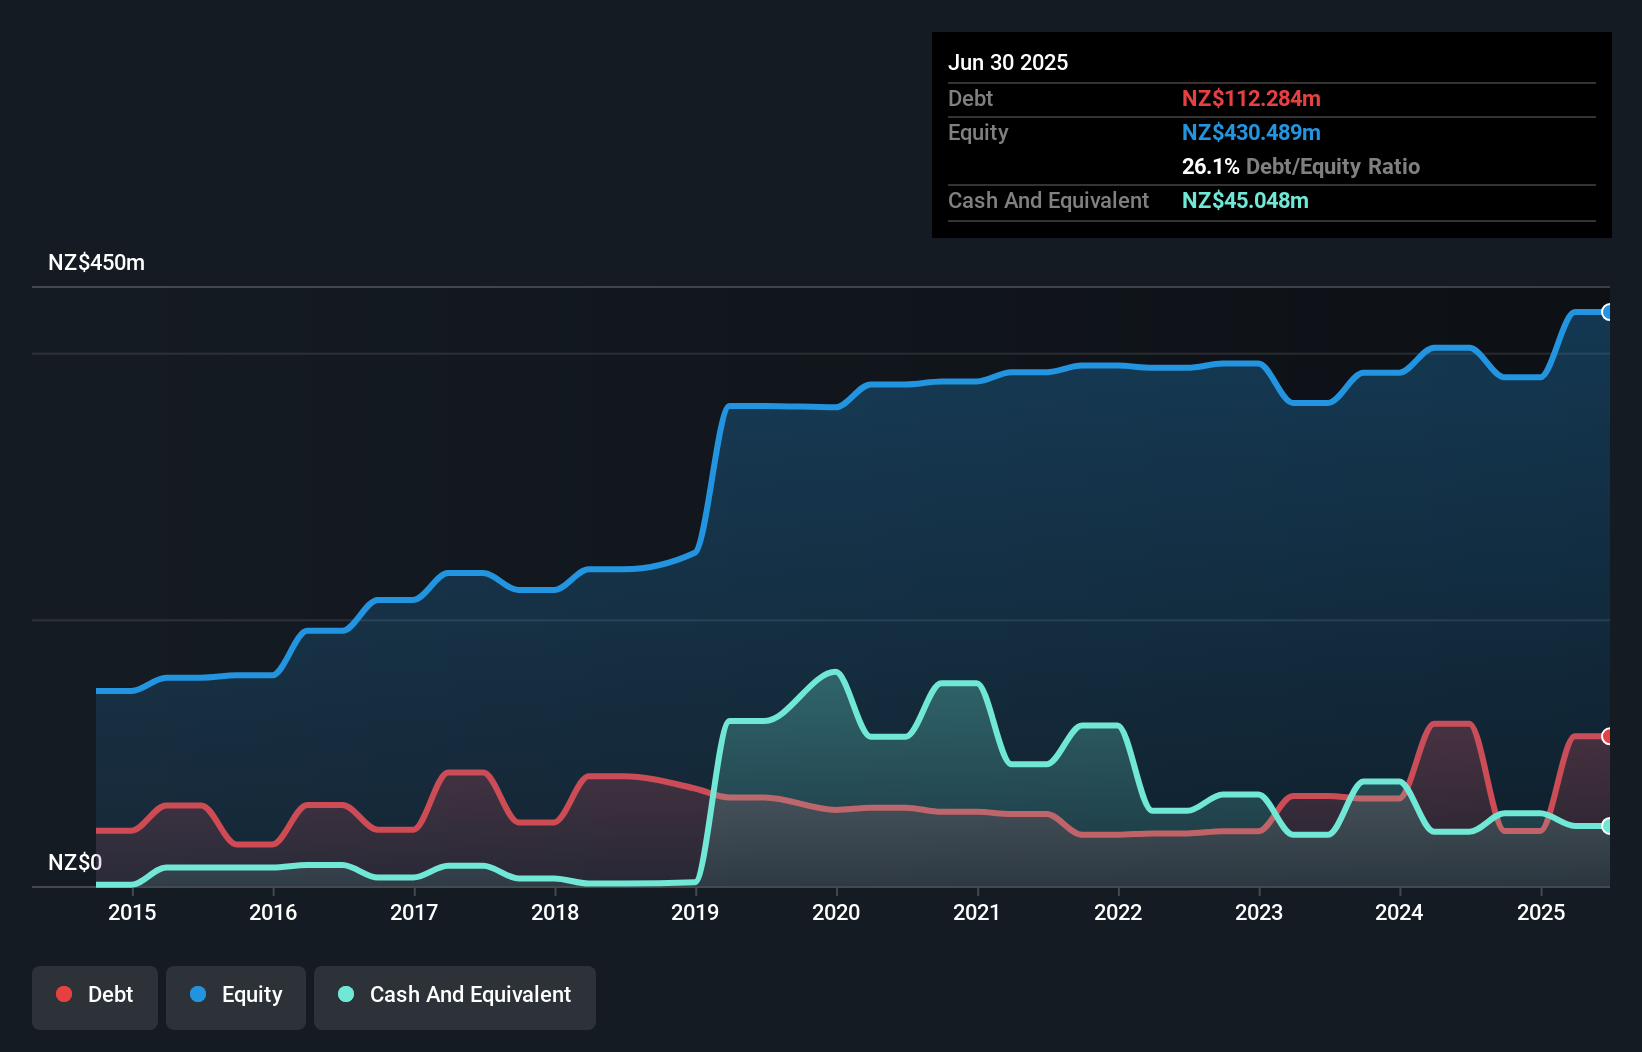
Scales, a small cap player in the food industry, has seen its earnings grow by 63% over the past year, surpassing the industry's 34.5% growth rate. Its net debt to equity ratio stands at a satisfactory 22.7%, and interest payments are well-covered at 9.1 times by EBIT. Despite recent insider selling and a large one-off gain of NZ$23.8 million impacting results, Scales remains profitable with positive free cash flow. The company is trading significantly below estimated fair value by about 63%, presenting potential opportunities for investors mindful of market conditions and performance risks.
Seize The Opportunity
- Investigate our full lineup of 180 Global Undiscovered Gems With Strong Fundamentals right here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com