
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ServiceNow's Quarterly Earnings Preview: What You Need to Know
With a market cap of $150.3 billion, ServiceNow, Inc. (NOW) is a leading provider of cloud-based digital workflow solutions that help organizations automate and streamline business operations across industries worldwide. The company offers a comprehensive portfolio of products spanning IT services, customer service, security, risk management, human resources, and workflow automation, enabling enterprises to improve efficiency and enhance user experiences.
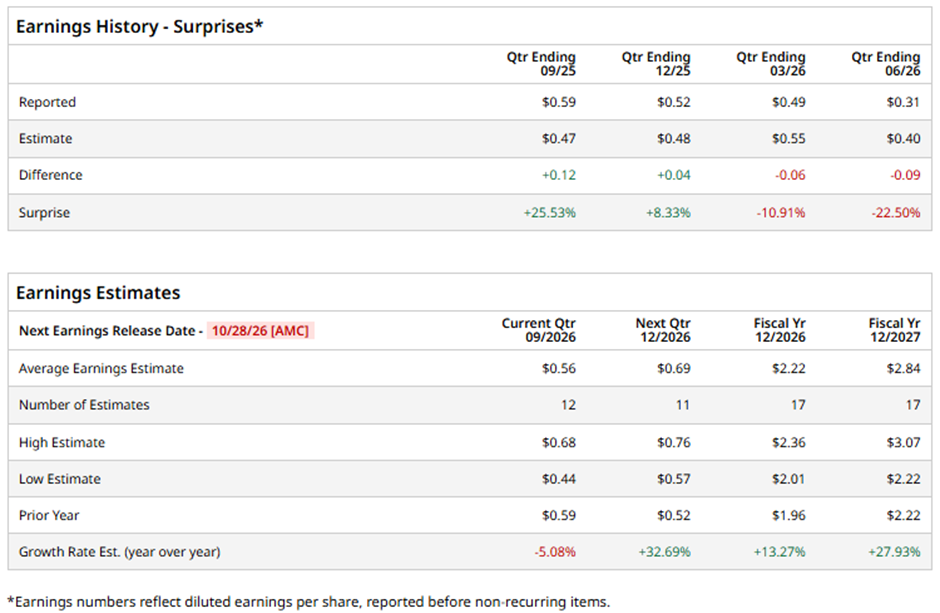
The Santa Clara, California-based company is slated to announce its fiscal Q3 2026 results after the market closes on Wednesday, Oct. 28. Ahead of the event, analysts expect NOW to report a profit of $0.56 per share, a 5.1% decline from $0.59 per share in the year-ago quarter. It has exceeded Wall Street's earnings expectations in two of the past four quarters while missing on two other occasions.
For fiscal 2026, analysts forecast the business software specialist to post EPS of $2.22, an increase of 13.3% from $1.96 in fiscal 2025. In addition, EPS is anticipated to grow 27.9% year-over-year to $2.84 in fiscal 2027.
Shares of ServiceNow have decreased 18.5% over the past 52 weeks, lagging behind the broader S&P 500 Index's ($SPX) 14.5% gain and the State Street Technology Select Sector SPDR ETF's (XLK) 28.7% return over the same period.
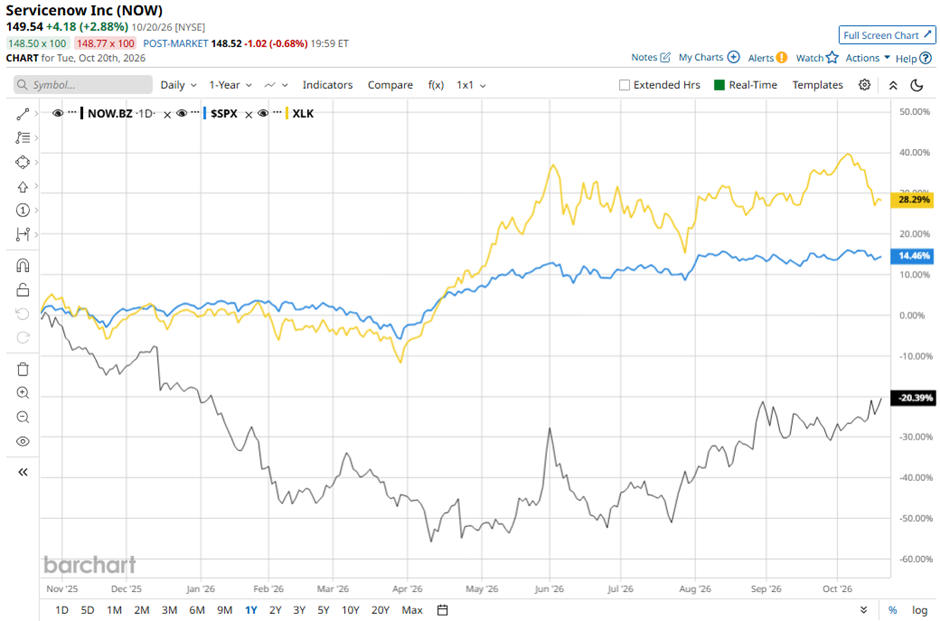
ServiceNow has underperformed over the past year due to concerns that AI could disrupt traditional IT software spending and threaten its seat-based pricing model. Aggressive acquisitions, heavy AI and cybersecurity investment, and elevated stock-based compensation have also increased concerns about margin pressure and earnings quality.
However, analysts' consensus view on NOW stock remains bullish, with a "Strong Buy" rating overall. Out of 46 analysts covering the stock, 38 recommend a "Strong Buy," three "Moderate Buys," three give a "Hold" rating, one "Moderate Sell," and one "Strong Sell." This configuration is slightly more bullish than three months ago, with 37 analysts suggesting a "Strong Buy."
The average analyst price target of $158.50, suggesting a potential upside of nearly 6% from current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.