
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Arrowhead Pharmaceuticals (ARWR) Brain Drug Trial Progress
- Arrowhead Pharmaceuticals reported past interim data from a Phase 1/2a trial of ARO-MAPT in healthy volunteers and confirmed deep, durable cerebrospinal fluid tau reductions with a generally mild safety profile, while also securing FDA STAR program entry for plozasiran in severe hypertriglyceridemia.
- The combination of central nervous system RNAi proof of concept and an accelerated US review pathway for an already approved triglyceride therapy directly affects Arrowhead Pharmaceuticals' development costs, regulatory timelines, and potential future revenue mix across neurology and cardiometabolic care.
- This section examines how Arrowhead Pharmaceuticals' investment narrative is shaped by ARO-MAPT brain delivery progress and the plozasiran STAR review.
Arrowhead Pharmaceuticals Investment Narrative Recap
To own Arrowhead Pharmaceuticals, you need to believe its RNAi platform can translate into multiple therapies across cardiometabolic disease and now neurology, before funding pressure bites. The latest ARO MAPT data and plozasiran STAR news push the story toward a more clinically validated, multi asset model, but the group is still loss making and reliant on external capital.
In the near term, the most important catalyst remains regulatory and commercial progress for plozasiran and the broader late stage cardiometabolic portfolio. The biggest risk is that elevated R&D and commercial spending outstrip incoming milestones, especially if partner programs slip or regulatory reviews slow, which would increase pressure on Arrowhead Pharmaceuticals to raise additional funding.
The FDA STAR pilot program acceptance for plozasiran is the operationally clearest piece for near term catalysts. A shorter review clock for the sHTG sNDA concentrates attention on the next set of regulatory milestones, and on how efficiently management can convert an already approved triglyceride drug into a broader indication with meaningful patient reach.
STAR does not remove core risks. Trial outcomes for other late stage assets, competitive RNA based cardiometabolic readouts, and Arrowhead Pharmaceuticals’ ability to manage cash while remaining unprofitable still sit in the foreground. For you as a shareholder, the trade off is execution speed on plozasiran and ARO MAPT against ongoing regulatory, funding, and partnership uncertainty.
Arrowhead Pharmaceuticals' narrative projects US$1.0b revenue and US$176.0 million earnings by 2029. This builds in 15.7% yearly revenue growth and an earnings swing of about US$496.0 million from a current loss of US$320.0 million to the 2029 consensus figure.
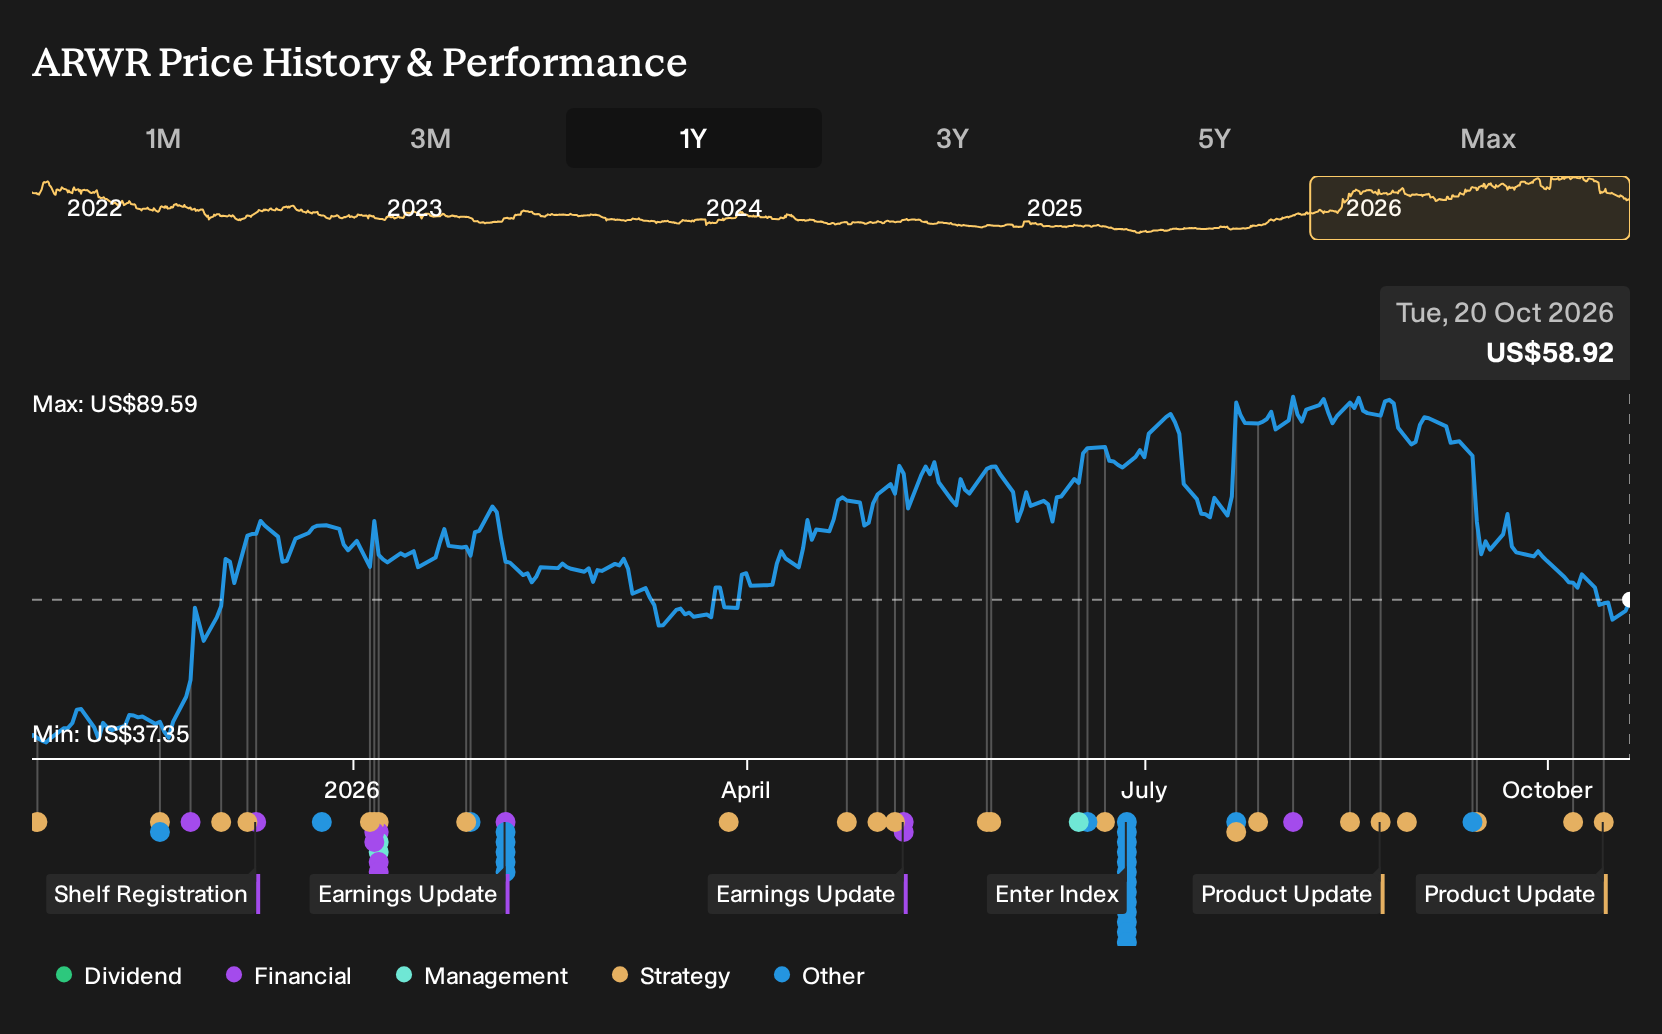
Uncover why Arrowhead Pharmaceuticals' fair value indicates a 87% potential upside to its current price before that discount gap closes.
Exploring Other Perspectives
One alternate view focuses on plozasiran’s severe hypertriglyceridemia launch as the key swing factor for Arrowhead Pharmaceuticals. Bullish analysts were already modeling revenue growth of 31.7% a year and earnings of about US$143.5 million by 2029, well above consensus. The new ARO MAPT and STAR updates can be treated as fresh inputs that might push those narratives in either direction.
Explore 2 other Arrowhead Pharmaceuticals fair value estimates, including one that suggests as much as 365% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Arrowhead Pharmaceuticals research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Arrowhead Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arrowhead Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Arrowhead Pharmaceuticals?
Once you have a view on Arrowhead Pharmaceuticals, it can help to compare that thesis with other opportunities that match your risk tolerance, income needs, and growth priorities. The Simply Wall St Screener gives you a way to quickly line up different types of companies against the same set of fundamentals so you can see where Arrowhead Pharmaceuticals fits in your wider watchlist.
- For investors who care most about balance sheet strength and business resilience, start with a list of solid balance sheet and fundamentals (25 results) that can help you focus on financially robust opportunities.
- If your priority is limiting downside risk, use the 31 resilient stocks with low risk scores to surface companies where volatility and risk scores are kept in tighter check.
- If you are interested in uncovering potential future leaders before they attract wide attention, there is a 21 high quality undiscovered gems that highlights companies with strong fundamentals that are still off most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com