
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Supermicro Stock Could Change Following Raised AI Guidance
- Super Micro Computer raised its preliminary fiscal Q1 2027 revenue and gross margin outlook, citing stronger than expected demand for its AI platforms and a more favorable customer and product mix.
- The stronger AI driven outlook is directly tied to Super Micro Computer's push toward higher margin integrated data center solutions and software centric offerings.
- The next focus will be on how this stronger AI driven outlook reshapes Super Micro Computer's investment narrative and risk balance.
Scan Super Micro Computer’s AI surge against a curated field of peers by reviewing the 55 AI infrastructure stocks that is now powering the same data center build out story.
Super Micro Computer Investment Narrative Recap
To own Super Micro Computer, you effectively need to believe AI data center build outs keep supporting high demand for its rack scale systems, software tools, and services. The near term swing factor is still execution on large AI orders and keeping the product mix skewed toward higher margin integrated solutions rather than lower value commodity hardware.
The biggest risk remains revenue and earnings volatility if one or two multibillion dollar customers slow orders or if AI pricing tightens, which could pull gross margins toward prior guidance levels. The latest upbeat AI outlook does not remove those pressures, but it helps near term confidence around backlog conversion and factory utilization.
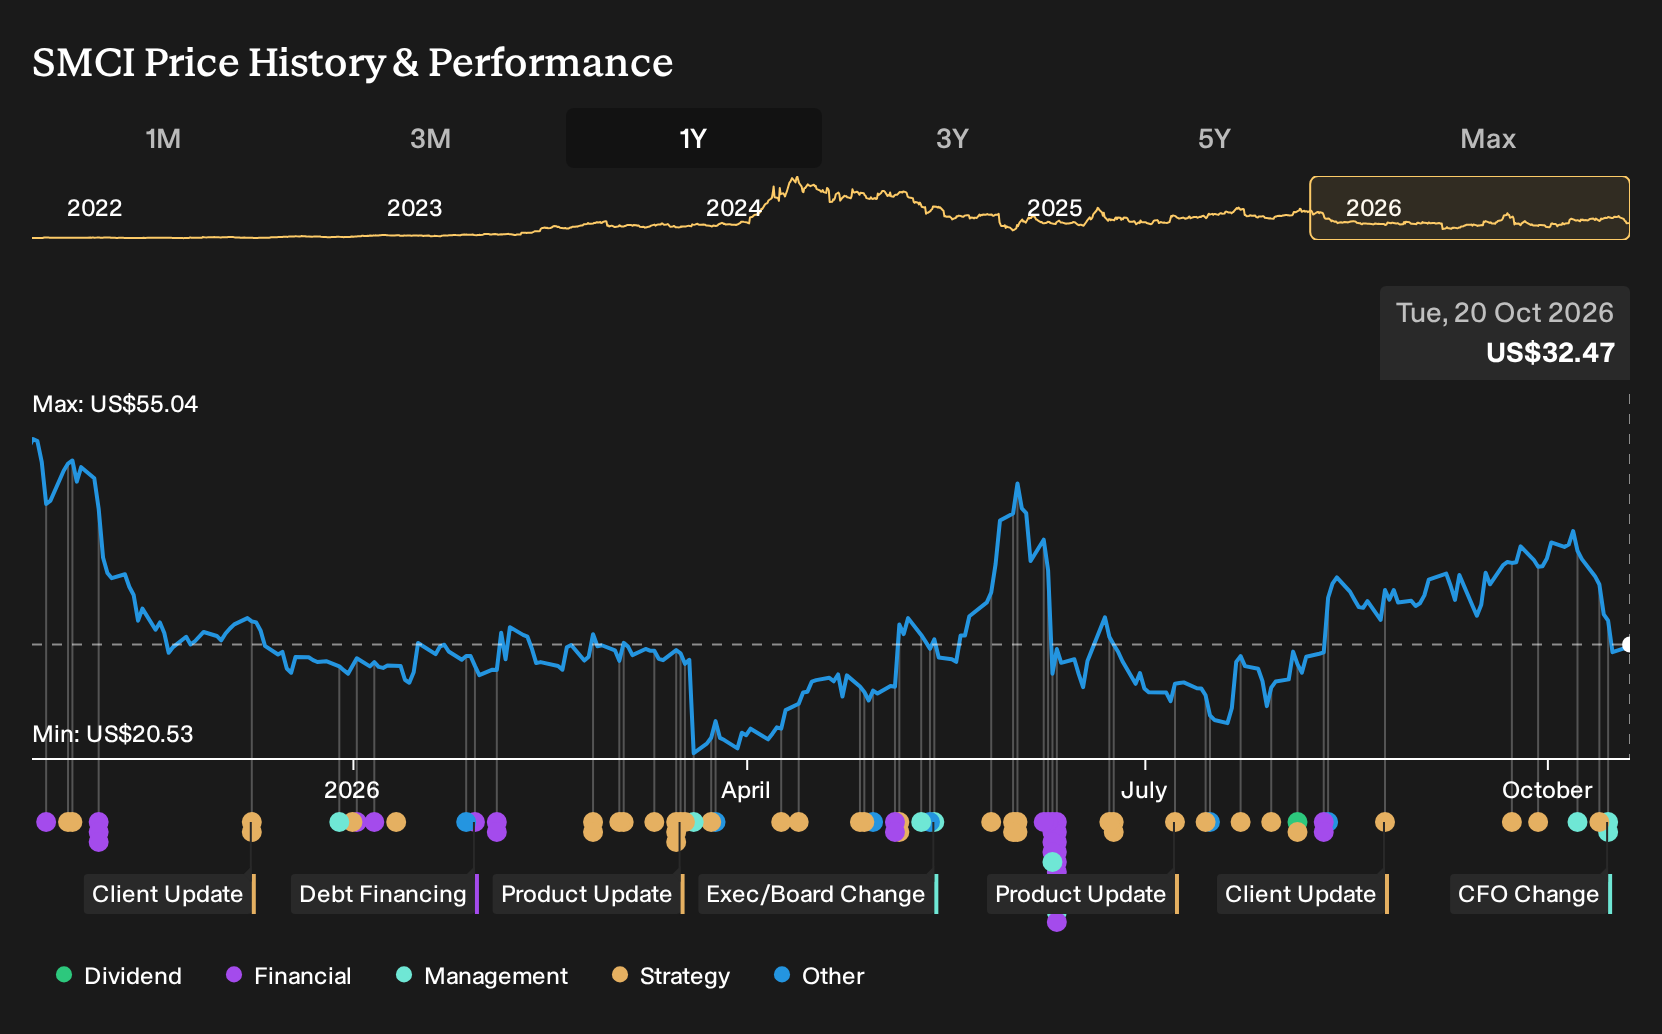
The appointment of Mark Long as Chief Financial Officer and Senior Vice President looks most relevant to this earnings revision. He brings experience in corporate finance, capital allocation, and large scale storage and data infrastructure from Western Digital, which matters when Super Micro Computer is carrying heavy working capital and scaling capacity for AI racks.
For you, the question is whether this leadership change helps tighten controls around working capital, export compliance, and earnings quality while the business leans harder into data center building block solutions and software centric offerings. If execution on those fronts improves, it could support the AI led revenue catalysts already visible in recent guidance.
Super Micro Computer Consensus Outlook And Implied Stretch
Analyst forecasts around Super Micro Computer put some hard numbers around the AI build out story you are weighing. The models behind the current targets assume revenue grows at 32.9% a year over the next three years while profit margins compress from 5.6% today to 3.7% by 2029.
On those assumptions, earnings are projected to move from US$2.2b today to US$3.4b by 2029, which is roughly a US$1.2b step up in profit even with lower margins. Forecasts for that 2029 earnings line are spread out, with the most optimistic analysts at US$4.2b and the most cautious closer to US$2.9b, so the dispersion here is not trivial.
For that profile to tie back to current price targets, the stock would need to trade on a P/E of 13.1x those 2029 earnings compared with 12.3x today and against an indicative 25.7x for the broader US tech group. Analysts are also baking in share count growth of roughly 7% a year for the next three years, which matters for you because it spreads any future profit across more shares.
The consensus valuation framework pulls this together into a headline target of US$42.38 per share for Super Micro Computer, based on those revenue, margin, and risk inputs. The current price of US$41.07 sits only about 3.1% below that mark, which signals that, on average, analysts see the stock as roughly aligned with their base case rather than clearly mispriced.
Behind that top line target, the scenario that analysts outline for 2029 requires US$91.7b in revenue and US$3.4b in earnings, discounted back at 9.5% in the Simply Wall St work. For you as an investor, the practical task is to decide whether a 32.9% annual revenue growth path, margin compression to 3.7%, and an eventual 13.1x P/E multiple feels realistic given your own read on AI data center spending, Super Micro Computer’s execution risks, and capital needs.
Super Micro Computer's narrative projects US$91.7b revenue and US$3.4b earnings by 2029. This setup assumes 32.9% yearly revenue growth and roughly US$1.2b earnings increase from US$2.2b today.
Uncover why Super Micro Computer's fair value indicates a 31% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts framed a very different catalyst for Super Micro Computer before this CFO news, leaning on the guided FY27 revenue range of US$65b to US$72b and potential earnings around US$4.2b by 2029. You can treat Mark Long’s appointment as a fresh test of that bolder AI factory story and compare multiple viewpoints.
Explore 10 other Super Micro Computer fair value estimates, including one that suggests as much as 85% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Super Micro Computer research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Super Micro Computer. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Super Micro Computer's overall financial health at a glance.
Looking For More Super Micro Computer Investment Ideas?
If the Super Micro Computer story has sharpened your thinking and you want to cast the net wider, the Simply Wall St Screener can help you quickly line up other opportunities that match your risk tolerance and return goals.
- For investors who want a focus on financial resilience and low leverage, it can be worth scanning a list of solid balance sheet and fundamentals (25 results) that may better match a capital preservation mindset.
- If your priority is limiting downside risk while still staying exposed to equities, you could review a 31 resilient stocks with low risk scores that keep volatility in check.
- Those hunting for underappreciated opportunities with stronger fundamentals than the price implies might start with a 21 high quality undiscovered gems that rarely shows up on mainstream stock lists.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com