
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Northwest Bancshares (NWBI), Why Is Fresh Attention Building Now?
Fresh attention is landing on Northwest Bancshares (NWBI) after recent coverage highlighted growing optimism around its upcoming September-quarter earnings report, with expectations for year-over-year growth in both revenue and profit.
Northwest Bancshares has seen short term momentum pick up, with a 1-day share price return of 1.51% and a 7-day gain of 2.62%, even though the 30-day move is down 2.43% and the 90-day share price return is down 1.66%.
Across a longer stretch, the year-to-date share price return of 25.92% and 1-year total shareholder return of 29.43% sit alongside a 3-year total shareholder return of 76.37% and 5-year total shareholder return of 44.51%. This suggests that the current optimism around the earnings outlook is being layered on top of an already strong track record of investor gains rather than coming from a cold start.
Capitalize on the renewed earnings buzz around Northwest Bancshares by lining it up against 34 high quality undervalued stocks, which also combine solid cash generation with balance sheet strength.Bulls point to Northwest Bancshares’ earnings momentum and sizeable intrinsic discount, while bears focus on recent share price softness and sector risk. Which story do the numbers lean toward as the valuation work begins?
Most Popular Narrative: 7% Undervalued
Against a last close of $15.09, the most followed narrative for Northwest Bancshares anchors on a fair value of $16.29. This frames the recent share price pause as a modest discount rather than a sign of fading conviction.
Expansion of Northwest Bancshares’ nationwide commercial and industrial verticals, which reached 27% of commercial lending by Q2 2026 and supported C&I loan growth of 32% year over year, continues to build a larger base for interest income and related fee revenue.
The multi year buildout of new financial centers in Columbus, together with the opening schedule through early 2027, is increasing Northwest Bancshares’ presence in growth markets and is aimed at adding deposits and local lending that can support future revenue.
See why 11 investors see Northwest Bancshares as 7% undervalued.
Result: Fair Value of $16.29 (UNDERVALUED)
Still, the thesis around Northwest Bancshares can fray if higher quarterly expenses in the US$107 million to US$109 million range, or rising healthcare related credit issues, start to pressure earnings and asset quality.
Find out about the key risks to this Northwest Bancshares narrative.
Another View: What Multiples Say About Northwest Bancshares
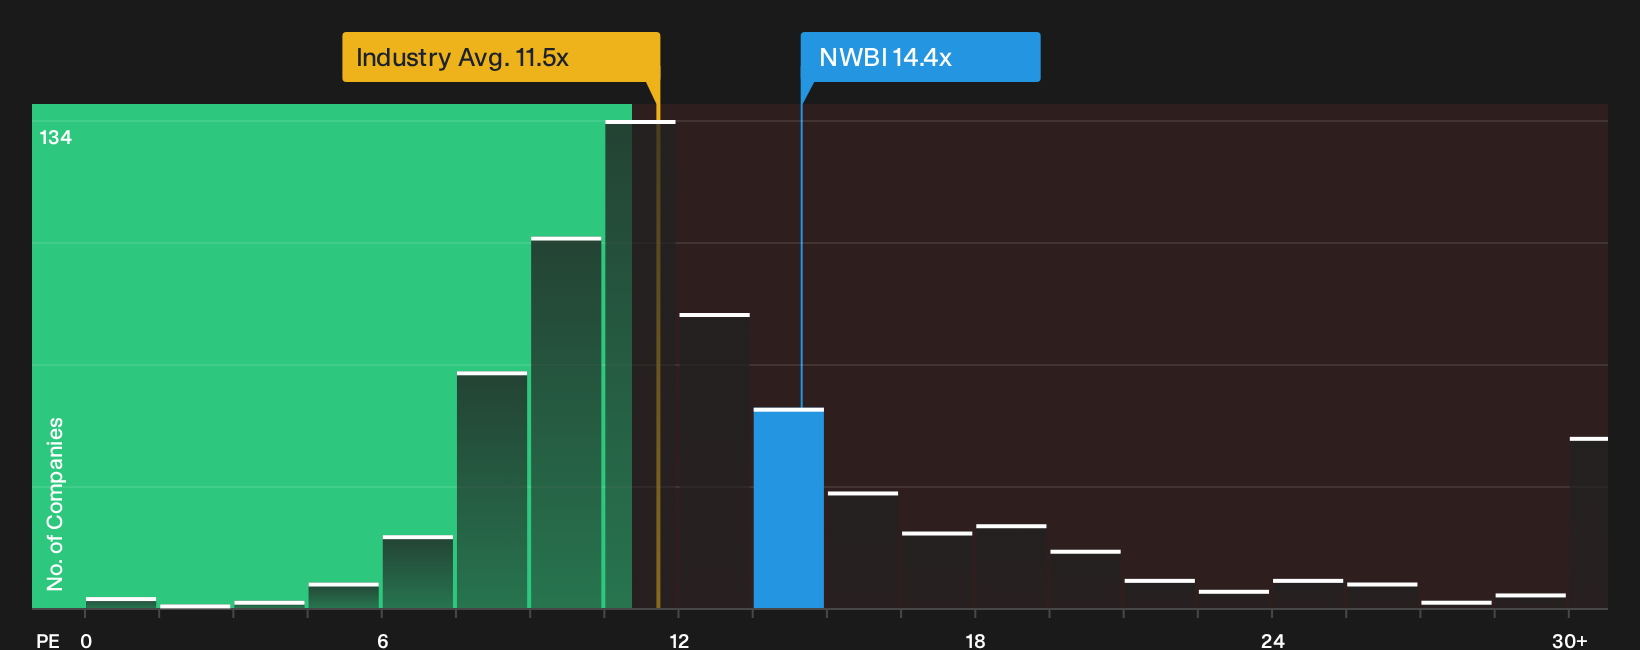
The SWS DCF work paints Northwest Bancshares as undervalued, yet the market is asking a richer price on earnings. The current P/E of 14.4x sits above both the US Banks industry on 11.4x and the estimated fair ratio of 13.2x. That gap points to some valuation risk if sentiment cools.
To see whether that higher P/E is justified by quality or simply optimism, it is worth going deeper into the valuation breakdown and letting the numbers do the talking through See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Northwest Bancshares is clearly split, which is exactly when fresh eyes matter most. Review the upside case for yourself through 3 key rewards
Looking for more investment ideas beyond Northwest Bancshares?
If you only stop at Northwest Bancshares, you could miss other opportunities that fit your goals just as well or even better.
- Target dependable income streams by scanning companies that qualify as 8 dividend fortresses for yields supported by underlying fundamentals.
- Hunt for value opportunities by checking the 21 high quality undiscovered gems that pair solid financials with limited market attention.
- Strengthen portfolio resilience by filtering for a 31 resilient stocks with low risk scores that screens for stocks with sturdier balance sheets and lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com