
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ryanair Holdings (ISE:RYA) Could Be 18% Below Fair Value After Rimini Base Expansion
Ryanair Holdings (ISE:RYA) has scheduled a €200 million, two-aircraft base in Rimini for Summer 2027, linking the new route capacity to Emilia Romagna’s recent Municipal Tax abolition.
For investors watching the tape, Ryanair Holdings’ recent Rimini move lands after a rough patch, with the share price down 21.38% year to date but supported by a 3-year total shareholder return of 70.20%, suggesting long-term holders have still seen meaningful gains.
Scan how Ryanair Holdings compares on growth, pricing power, and balance sheet strength next to a hand picked 188 high quality undervalued stocks that share similar operational tailwinds.
Bulls see Rimini as proof Ryanair Holdings can still find profitable capacity, while bears point to a share price that has fallen this year. Which side do the numbers lean toward as you weigh valuation?
Most Popular Narrative: 18% Undervalued
Ryanair Holdings closed at €23.35, while the most followed narrative pegs fair value near €28.57. The story hinges on whether its cost edge and traffic ambitions can justify that gap.
Fuel and currency hedging out to FY 2027 at materially better rates, alongside a transition to a debt free balance sheet with over 600 unencumbered aircraft, gives Ryanair a high degree of cost and financing visibility. This can be used to selectively stimulate fares while still widening the cost gap to competitors, potentially supporting resilient earnings through the cycle.
See why 7 investors see Ryanair Holdings as 18% undervalued.
Result: Fair Value of €28.57 (UNDERVALUED)
Still, softer near term fares and shareholder pushback on Michael O’Leary’s pay package could unsettle sentiment and test conviction in the Ryanair Holdings narrative.
Find out about the key risks to this Ryanair Holdings narrative.
Another View: Ryanair Holdings Through The P/E Lens
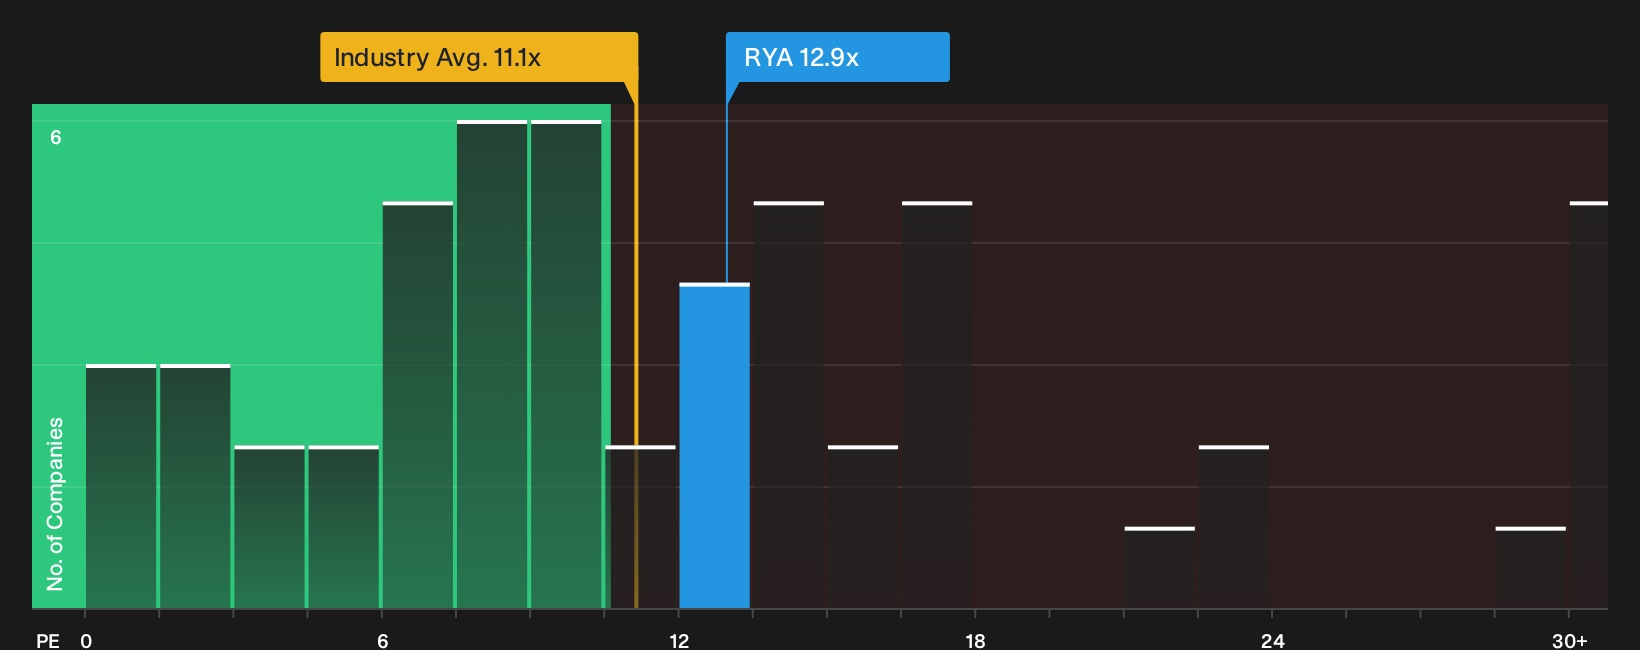
The story changes when you step away from cash flows and look at simple earnings multiples. Ryanair Holdings trades on a P/E of 12.9x, higher than the global airlines average of 11.1x, yet below its peer group at 14.2x. That mix of richer industry pricing and cheaper peer comparison raises a practical question for you. Is the premium to the sector a red flag, or does the discount to similar operators hint at value risk being more balanced than it first appears?
For a closer look at how this earnings multiple stacks up against history, peers, and our fair ratio view, check the detailed breakdown next to the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Ryanair Holdings is split, with clear risks on one side and meaningful potential on the other. Weigh the data yourself and move quickly to frame your stance with 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Ryanair Holdings?
If Ryanair Holdings has sharpened your focus on valuation and risk, use that momentum and line up your next watchlist candidates while this insight is fresh.
- Spot potential value upside before the crowd by scanning a curated 188 high quality undervalued stocks that already clear key quality and balance sheet checks.
- Build a steadier income stream by reviewing a focused set of 221 dividend fortresses that pair higher yields with robust fundamentals.
- Dial down portfolio stress by concentrating on a 228 resilient stocks with low risk scores that screens for resilient businesses with lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com