
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For FactSet Stock Could Change Following Scotia Wealth Expansion
- In early October 2026, FactSet Research Systems reported an expanded partnership with Scotia Wealth Management that will embed FactSet's unified research, data, and portfolio tools more deeply into Scotia's advisor and investment platforms.
- This deeper integration into Scotia Wealth Management's workflows, alongside FactSet's role in supporting equity capital market activity around high profile IPOs, highlights how embedded data platforms can become critical infrastructure for both advisory and capital markets teams.
- We will now look at how FactSet's broader Scotia Wealth integration could influence the investment narrative that analysts outlined earlier.
Scan beyond FactSet Research Systems and focus on other data driven platforms that could benefit from heavier wealth management and IPO workflows by reviewing our hand picked 21 high quality undiscovered gems list.
FactSet Research Systems Investment Narrative Recap
To own FactSet Research Systems today, you need to believe its role as a core data and workflow utility for advisors, bankers, and asset managers keeps deepening, even if headline growth stays mid single digit. The Scotia Wealth expansion fits that view. It reinforces FactSet inside a large wealth channel but does not dramatically change the near term trajectory on its own.
The key near term swing factor remains how effectively FactSet turns AI products, MCP data delivery, and longer contracts into steadier ASV and margin progress while clients scrutinize tech budgets. The main risk is still slower pricing and cautious asset management and banking spending, which could blunt upsell activity and limit operating leverage.
Against that backdrop, the expanded Scotia Wealth Management partnership looks most relevant. It pushes FactSet Research Systems deeper into day to day advisor workflows, tying research, data, and portfolio tools into a single interface for a broad group of front office users. That kind of embedded usage can support stickier subscriptions and cross sell opportunities over time.
Anthropic related IPO excitement also matters for the story. FactSet already serves equity capital market desks that track deal flow and underwriting pipelines. If ECM and IPO teams lean more heavily on its platform during busy issuance periods, that usage lines up directly with existing catalysts around AI driven analytics, MCP delivery, and longer duration enterprise style agreements.
FactSet Research Systems' current analyst narrative points to revenues of US$2.9b and earnings of US$704.3m by 2029, built on 5.7% yearly top line growth and an increase in profit from US$533.5m today to that 2029 consensus, which is about a US$170.8m earnings step up over the period.
Uncover why FactSet Research Systems' fair value indicates a 10% potential downside to its current price that leaves little room for error.
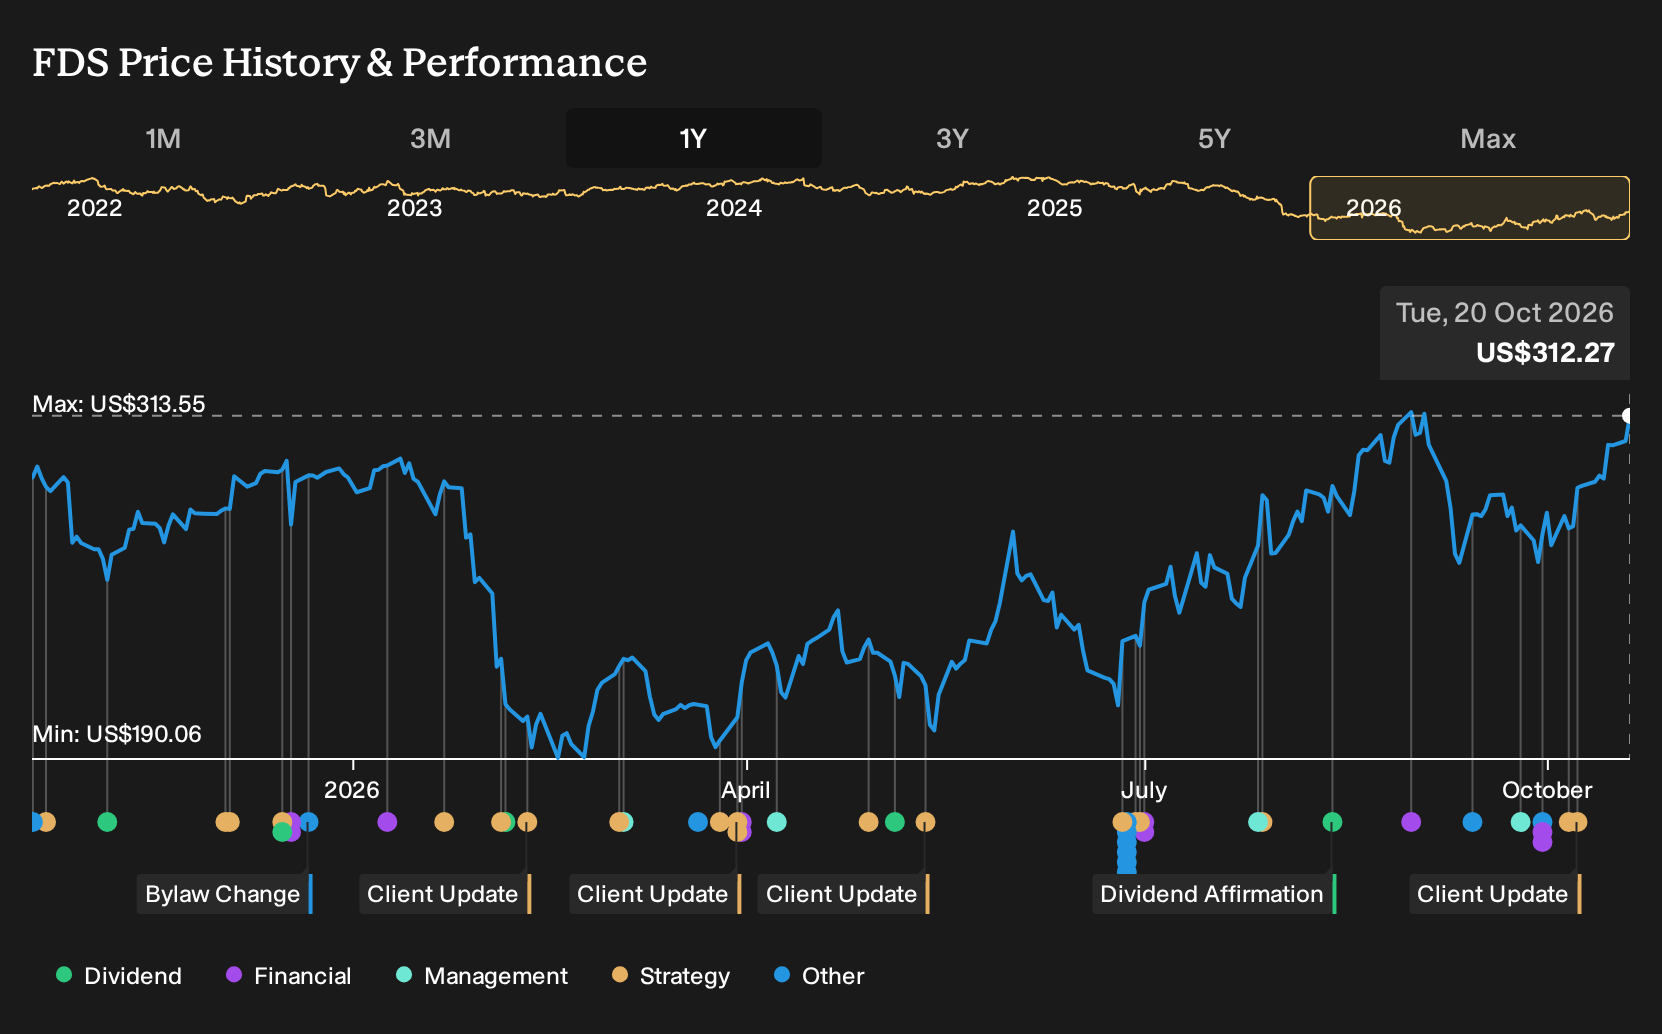
Exploring Other Perspectives
Some of the lowest FactSet Research Systems forecasts lean into a different worry. They focus on AI driven rivals eroding pricing power and keep 2029 earnings closer to US$695.5m on roughly US$2.9b of revenue. Those estimates, set before the Scotia Wealth news, show how sharply opinions can differ. Use them as a prompt to compare multiple narratives yourself.
Explore 5 other FactSet Research Systems fair value estimates, including one that suggests as much as 33% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis.
- A great starting point for your FactSet Research Systems research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FactSet Research Systems. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate FactSet Research Systems' overall financial health at a glance.
Looking for more FactSet Research Systems style investment ideas?
Once you have a handle on FactSet Research Systems, it can help to widen the search and compare it with other businesses that share traits you care about, whether that is value, resilience, or balance sheet strength.
- If you are hunting for quality at a reasonable price, start with a curated set of potential value opportunities through our 34 high quality undervalued stocks.
- If capital preservation matters most to you, focus on stability first by scanning a 31 resilient stocks with low risk scores that score well on resilience.
- If financial robustness is your priority, concentrate on companies with strong funding and liquidity profiles through a list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com