
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kyndryl Holdings (KD) Wins IDC Praise And Toyota AI Deal, Is It Fully Priced?
Kyndryl Holdings (KD) is back in the headlines after two fresh developments: a partnership with Toyota Finance on agentic AI for IT operations and recognition as a Leader in IDC’s global digital workplace services assessment.
Those headlines are landing against a sharp bounce in Kyndryl Holdings’ share price in the short term, with a 1-day share price return of 4.59%, 7-day return of 13.48%, and 30-day return of 15.08%. However, total shareholder return over the past year has declined 51.52%, and the 5-year total shareholder return is down 60.87%. This suggests that recent enthusiasm around partnerships and AI projects is emerging against a longer record of weak investor outcomes.
Spot emerging AI infrastructure momentum plays by scanning our hand picked 55 AI infrastructure stocks that, like Kyndryl Holdings, are tied to large scale digital transformation projects.Kyndryl Holdings now trades only slightly below analyst targets yet still at a sizeable discount to some fair value estimates. After such a sharp bounce, is the market’s caution misplaced or exactly on point?
Most Popular Narrative: 1% Undervalued
Kyndryl Holdings last closed at $13.89, which sits slightly below a widely followed fair value estimate of $14.10 that applies a 12.46% discount rate. That small gap leaves the narrative leaning on execution in higher margin services and AI partnerships rather than on a wide valuation cushion.
The company's focus on expanding AI, data, and cybersecurity services, supported by investments in proprietary initiatives like Kyndryl Bridge and new alliances such as Databricks, is allowing Kyndryl to address rising complexity and security requirements, supporting both higher margins and new revenue streams.
See why 52 investors see Kyndryl Holdings as 1% undervalued.
Result: Fair Value of $14.10 (ABOUT RIGHT)
Still, Kyndryl Holdings remains tied to older, lower margin contracts and complex account reshaping, so delays or lost renewals could quickly unsettle that fair value story.
Find out about the key risks to this Kyndryl Holdings narrative.
Another View: What Kyndryl Holdings’ P/E Is Telling You
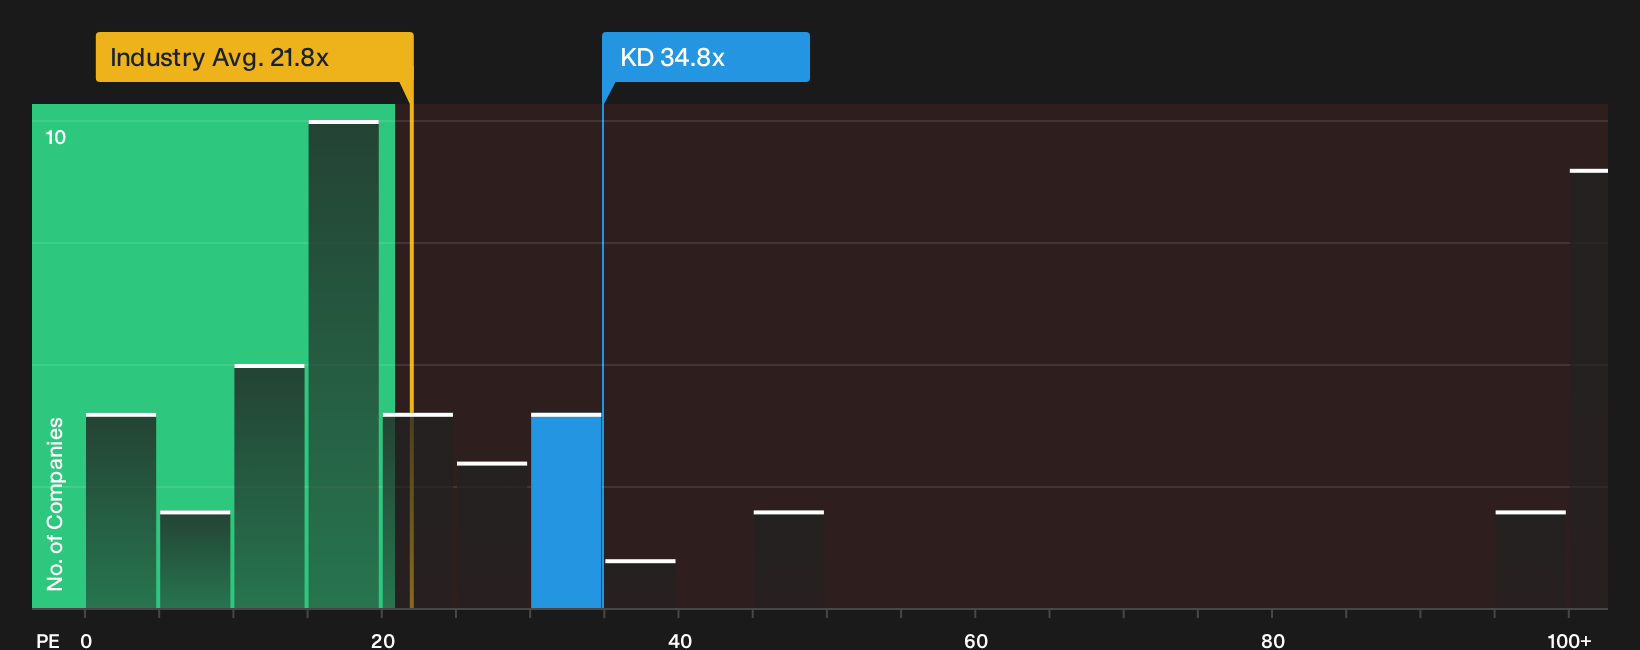
The fair value story points to Kyndryl Holdings trading about 30% below an internal estimate, yet the market is charging a P/E of 34.8x. That is richer than the US IT industry at 22.9x and far above a fair ratio of 52.2x, which leaves a wide range of outcomes for investors to weigh.
That gap between current P/E, peers, and the fair ratio raises a simple question. Is the market overpaying for near term uncertainty or underpricing the longer term earnings path implied by those forecasts?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Kyndryl Holdings so far. If you want to move quicker than the crowd, pull up the data, stress test the narratives, and weigh the 2 key rewards and 3 important warning signs.
Looking for more Kyndryl Holdings sized opportunities?
If Kyndryl Holdings has you rethinking where the real potential lies, use this as a springboard to widen your watchlist with fresh, data backed ideas.
- Zero in on quality at a discount by scanning our hand picked 34 high quality undervalued stocks before other investors catch on.
- Prioritise resilience and sleep easier at night by reviewing the 31 resilient stocks with low risk scores built around balance sheet strength and lower risk scores.
- Hunt for tomorrow's quiet winners by checking the 21 high quality undiscovered gems that pair solid fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com