
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ESCO Technologies (ESE) Could Be 42% Undervalued On Its Backlog Backed Growth Narrative
ESCO Technologies (ESE) has drawn investor attention after its share price declined about 7% over the past month and roughly 24% in the past 3 months, despite reporting annual revenue of US$1.29b and net income of US$139.84m.
Over the shorter term, momentum has cooled for ESCO Technologies, with the share price down 4.91% over the past week and 6.87% over the last month. However, the year to date share price return of 25.31% and a 5 year total shareholder return of 194.35% still paint a picture of a stock that has rewarded patient holders, even as recent moves hint at a reassessment of growth prospects and risk.
Spot short term pullbacks such as ESCO Technologies and compare them with other industrials on the radar using the list of solid balance sheet and fundamentals (25 results).
That mix of recent weakness and longer term gains puts ESCO Technologies at an interesting crossroads. Does the current pullback leave a margin of safety for new money, or has the easy part of the risk reward already played out?
Most Popular Narrative: 30% Undervalued
In the most followed narrative, ESCO Technologies is described as undervalued, with a fair value estimate of $352.75 compared with the last close of $247.64. That gap is based on a view that long-run demand and a sizeable order book can continue to support the current earnings trajectory.
Record consolidated book to bill of 1.21 and backlog of US$1.54b, with all three segments above 1.0 book to bill, is cited as signaling multi quarter revenue support as ESCO Technologies converts existing orders to sales and earnings.
See why 3 investors see ESCO Technologies as 30% undervalued.
Result: Fair Value of $352.75 (UNDERVALUED)
Still, the upbeat ESCO Technologies story quickly changes if the Megger integration stumbles or renewables weakness drags on margins longer than analysts currently assume.
Find out about the key risks to this ESCO Technologies narrative.
Another View: ESCO Technologies Through The P/E Lens
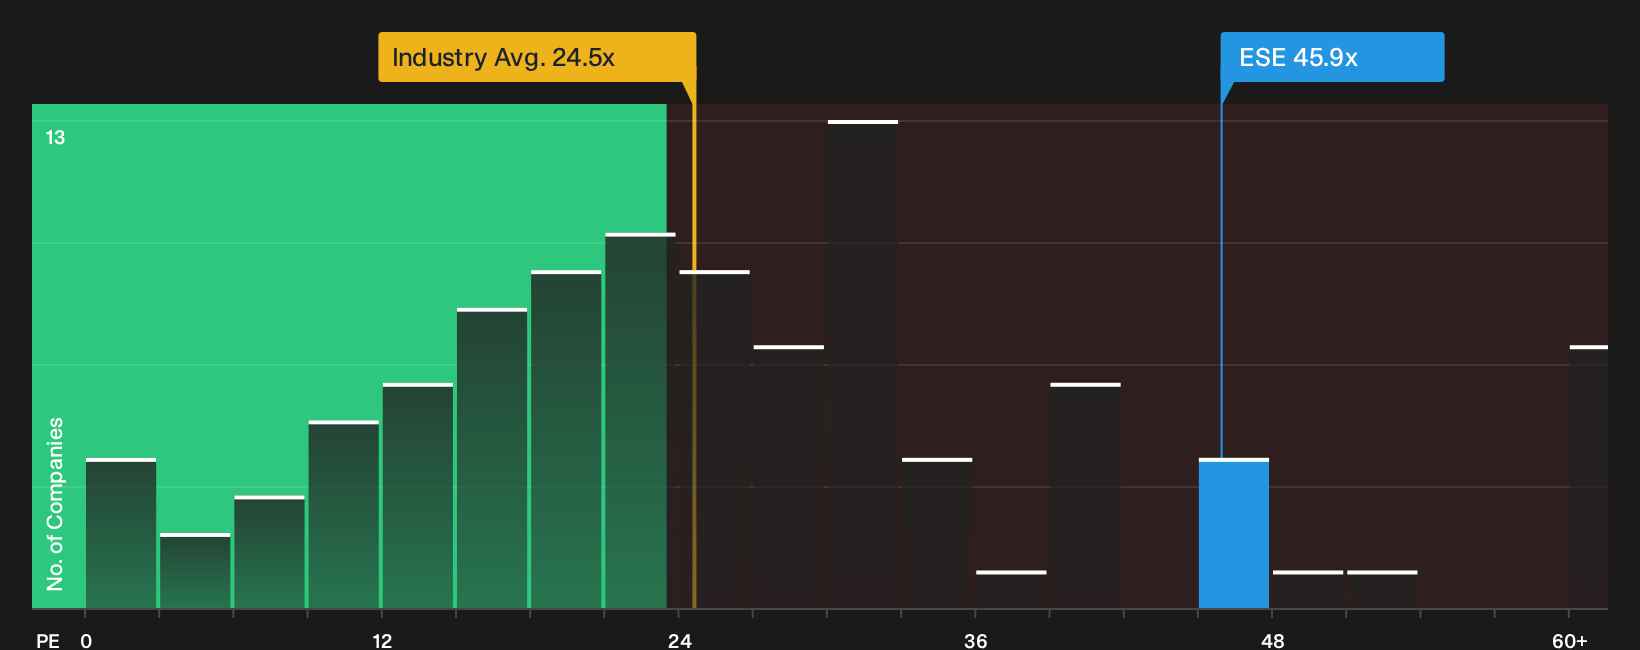
Looking at ESCO Technologies through a simple P/E lens, the picture appears less relaxed. The stock trades around 45.9x earnings compared with 24.1x for the wider US Machinery group and a fair ratio of 29.1x, which suggests a relatively rich valuation and less room for mistakes.
Against closer peers, the current multiple lines up a bit better, with the group sitting nearer 53.8x. That still leaves investors weighing whether ESCO Technologies merits industry-level pricing or whether the market eventually moves back toward that lower fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between ESCO Technologies’ recent pullback and its longer term strength is normal, and the cleanest way through that conflict is to test the data yourself and decide whether the current setup fits your risk profile. To see what investors view as the main positives, take a closer look at the 4 key rewards.
Looking for more ESCO Technologies sized opportunities?
Do not stop your research with ESCO Technologies alone. Broaden your watchlist with fresh ideas that match your risk tolerance and return goals using focused screeners.
- Target potential mispricing by scanning a curated pool of opportunities through the 34 high quality undervalued stocks.
- Strengthen your income stream by hunting for payout-focused ideas inside the 8 dividend fortresses.
- Trim portfolio risk by zeroing in on stocks that prioritise resilience using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com