
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Asian Stocks That May Be Undervalued In October 2026
As global markets grapple with inflation pressures and AI-related investment concerns, Asian equities have experienced a mixed performance, with technology stocks facing particular scrutiny. In this environment, identifying undervalued stocks can be crucial for investors looking to capitalize on potential opportunities amidst market volatility.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Wacom (TSE:6727) | ¥832.00 | ¥1624.92 | 48.8% |
| Riken Technos (TSE:4220) | ¥2419.00 | ¥4769.19 | 49.3% |
| PAL GROUP Holdings (TSE:2726) | ¥1465.00 | ¥2912.16 | 49.7% |
| Nissui (TSE:1332) | ¥1106.00 | ¥2168.23 | 49% |
| Kumagai GumiLtd (TSE:1861) | ¥1203.00 | ¥2405.85 | 50% |
| Kingnet Network (SZSE:002517) | CN¥15.33 | CN¥30.54 | 49.8% |
| Inner Mongolia ERDOS ResourcesLtd (SHSE:600295) | CN¥14.31 | CN¥28.25 | 49.3% |
| ENN Energy Holdings (SEHK:2688) | HK$49.20 | HK$97.21 | 49.4% |
| Double Medical Technology (SZSE:002901) | CN¥39.77 | CN¥78.97 | 49.6% |
| Apex Mining (PSE:APX) | ₱16.92 | ₱33.29 | 49.2% |
We'll examine a selection from our screener results.
Beijing Kingsoft Office Software (SHSE:688111)
Overview: Beijing Kingsoft Office Software, Inc. offers office software products and services both in China and internationally, with a market capitalization of approximately CN¥108.52 billion.
Operations: The company generates revenue primarily from its software and programming segment, which amounts to CN¥6.58 billion.
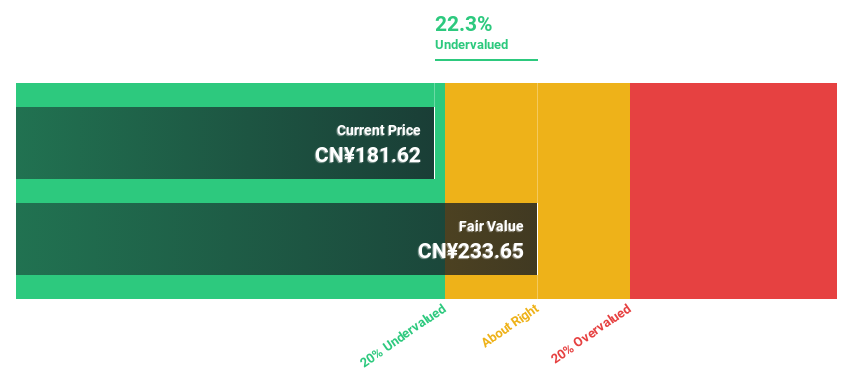
Estimated Discount To Fair Value: 31.5%
Beijing Kingsoft Office Software is trading at CN¥233.88, significantly below its estimated cash flow value of CN¥341.28, indicating it may be undervalued based on cash flows. Despite a forecasted earnings growth of 3.82% per year and revenue growth outpacing the Chinese market at 16.7%, the company's return on equity is expected to remain low at 17.9%. Recent reports show strong financial performance with net income surging to CN¥2.52 billion for H1 2026 from CN¥747 million a year ago, highlighting robust profitability despite moderate future growth expectations.
- Upon reviewing our latest growth report, Beijing Kingsoft Office Software's projected financial performance appears quite optimistic.
- Unlock comprehensive insights into our analysis of Beijing Kingsoft Office Software stock in this financial health report.
ZYNP (SZSE:002448)
Overview: ZYNP Corporation focuses on the research, development, manufacture, and sales of automotive components in China and internationally with a market cap of CN¥6.37 billion.
Operations: The company's revenue is primarily generated from Auto Parts Manufacturing, totaling CN¥3.91 billion.
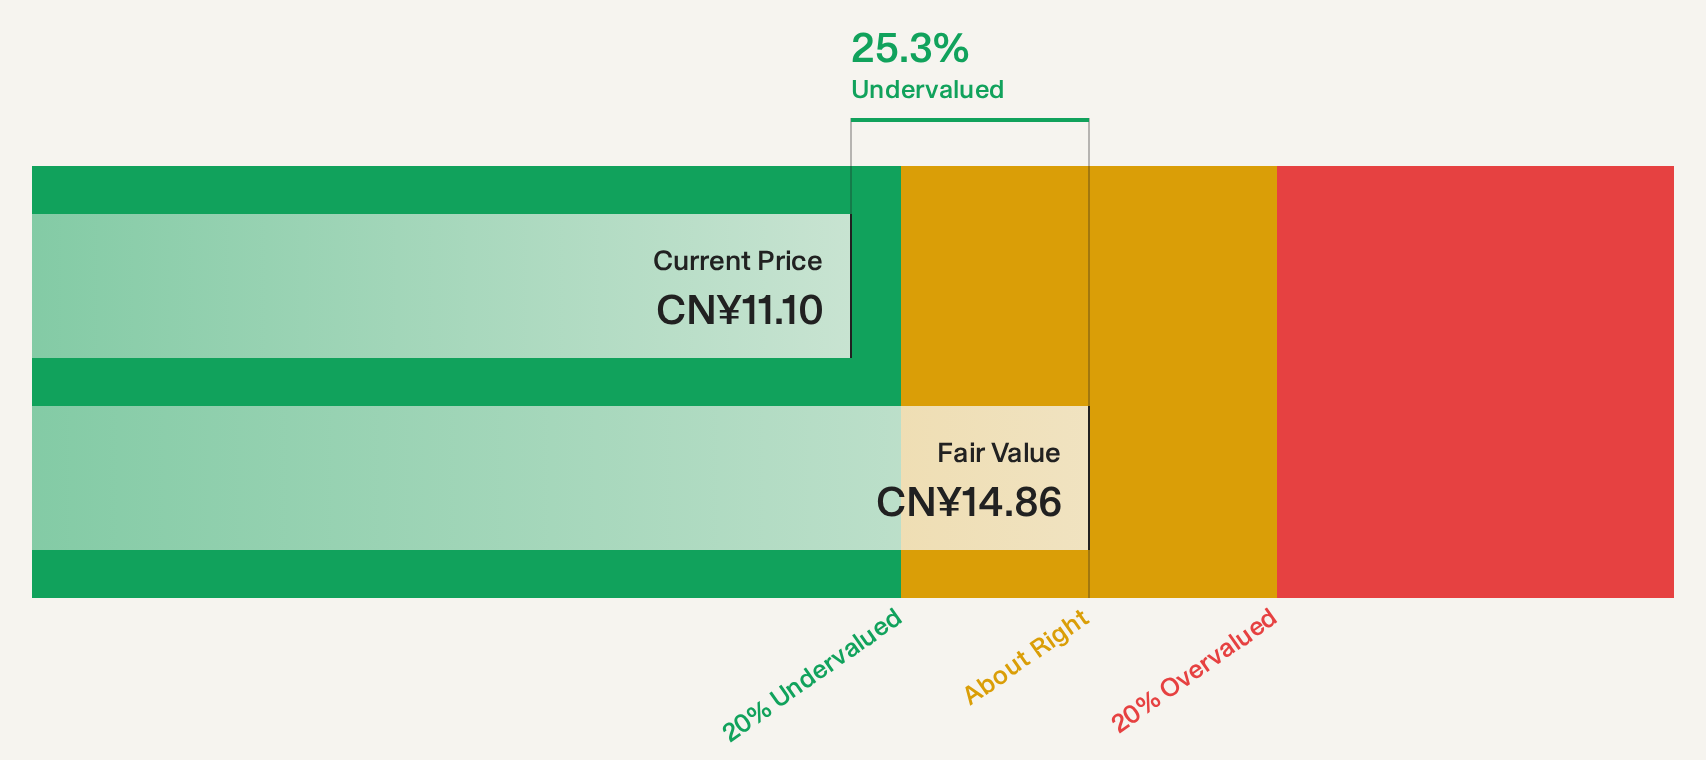
Estimated Discount To Fair Value: 25.7%
ZYNP Corporation, currently priced at CN¥10.82, is trading below its estimated future cash flow value of CN¥14.56, suggesting potential undervaluation. The company's earnings have grown by 100.2% over the past year and are expected to continue growing at 15.96% annually, although this lags behind the broader Chinese market's forecasted growth of 26.4%. Recent financials show revenue increased to CN¥2.47 billion for H1 2026 from CN¥1.94 billion a year earlier, reflecting solid performance amidst slower projected earnings growth relative to market peers.
- In light of our recent growth report, it seems possible that ZYNP's financial performance will exceed current levels.
- Delve into the full analysis health report here for a deeper understanding of ZYNP.
Double Medical Technology (SZSE:002901)
Overview: Double Medical Technology Inc. focuses on the research, development, production, and sale of high-value medical consumables in China and has a market cap of CN¥16.08 billion.
Operations: The company's revenue segments include Spine Products (CN¥513.09 million), Joint Products (CN¥239.18 million), Trauma Products (CN¥1.04 billion), Dental Products (CN¥76.35 million), Neurosurgical Products (CN¥117.82 million), and Minimally Invasive Surgery Products (CN¥426.57 million).
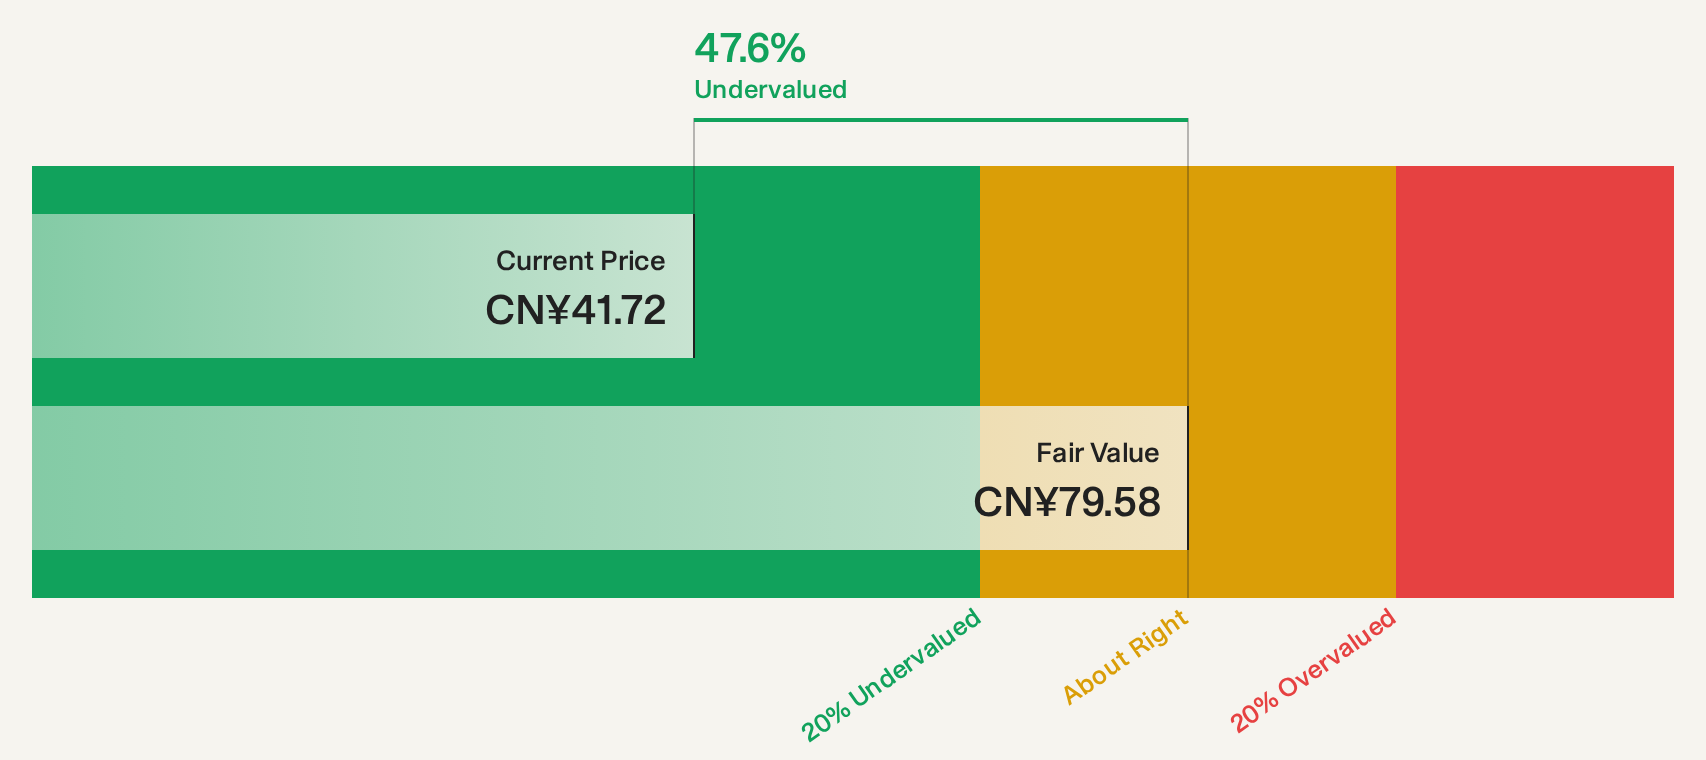
Estimated Discount To Fair Value: 49.6%
Double Medical Technology, priced at CN¥39.77, trades significantly below its estimated future cash flow value of CN¥78.97, highlighting potential undervaluation based on cash flows. Despite earnings growing by 53.1% over the past year and a recent share buyback totaling CN¥258.95 million, future revenue growth is projected at 13.2% annually—below the Chinese market average of 16.2%. The company reported H1 2026 revenue of CNY 1.34 billion with net income rising to CNY 353.33 million from CNY 244.26 million year-on-year.
- According our earnings growth report, there's an indication that Double Medical Technology might be ready to expand.
- Click to explore a detailed breakdown of our findings in Double Medical Technology's balance sheet health report.
Where To Now?
- Gain an insight into the universe of 182 Undervalued Asian Stocks Based On Cash Flows by clicking here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com