
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 British Undervalued Stocks Trading Up To 48% Below Fair Value
Global mergers and acquisitions are running close to record levels as businesses race to secure assets that can support artificial intelligence, data centers and energy needs. That kind of deal fever often searches for strong cash generators. For investors in United Kingdom shares, this creates a window to look at companies where cash flows appear undervalued. This article highlights three such stocks from our cash flow value screen.
The three examples that follow only scratch the surface of what this cash flow lens can uncover, as the wider screen surfaced 25 more businesses with similarly interesting stories that are not covered here. To see the full picture, analyze and sort these opportunities directly in the Undervalued Stocks Based On Cash Flows screener.
Balfour Beatty (LSE:BBY)
Balfour Beatty is a £4.0b infrastructure group that builds and maintains everything from roads to hospitals, with its Infrastructure Investments and Support Services arms running long-term concession and maintenance contracts that feed into discounted cash flow models. Revenue is heavily skewed toward Construction Services at about £8.0b, with Support Services at roughly £1.5b and Infrastructure Investments near £470m.
Balfour Beatty matters for this cash flow screen because a meaningful slice of its business is tied to long-life infrastructure concessions and maintenance contracts that can support relatively visible, contract-backed cash generation over time.
The company could stand to benefit if the Labour government proceeds with its initiative for growth and implements the related, mooted slashing of planning and building regulations in particular.
What happens if one pressure on future project economics shifts even slightly will be crucial for how those projected cash flows translate into value.
If that planning shift is even partial reality for Balfour Beatty, the full narrative for Balfour Beatty shows how contract cash flows and risk could be decoupling in interesting ways.
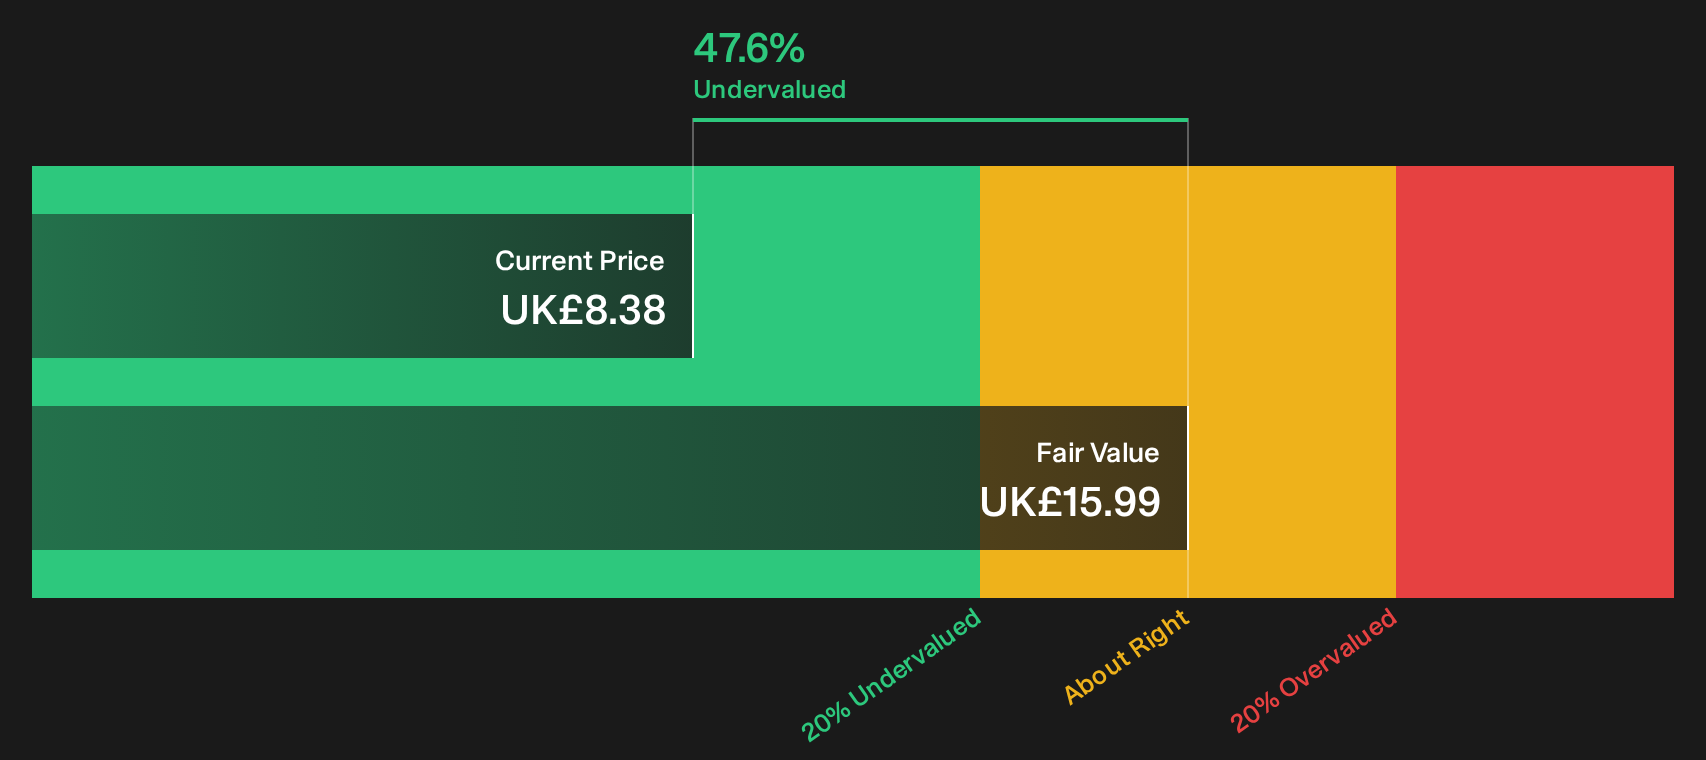
Gamma Communications (LSE:GAMA)
Gamma Communications runs cloud-based voice, video and contact centre services that produce recurring cash flows, which is exactly what this cash flow screen is looking for. The focus here is how those subscription revenues might line up with what the discounted cash flow work is implying.
Large parts of the business communications market in Germany are still using legacy on premise systems. With only a small portion of that market currently on cloud solutions, Gamma’s existing presence and proprietary platforms such as STARFACE and Placetel give it a long runway to grow cloud seats and recurring revenue as adoption continues over many years, which can support earnings.
What happens if one key piece of that recurring cash flow story does not track the assumptions baked into those earnings models?
Gamma Communications provides cloud communications, connectivity and contact centre tools that let organisations run phone, video and customer support over the internet, with meaningful recurring revenue from services like Gamma Connect and cloud contact centres. Enterprise brings in about £136 million, Germany SME about £121 million and Other Europe £31 million, while segment adjustments and inter-segment items take the reported total higher. The business carries a market value of roughly £973 million.
If those recurring assumptions prove too tight or too loose, the full narrative for Gamma Communications explains where Gamma Communications’ cash story may be accelerating, stalling or quietly masking risk.
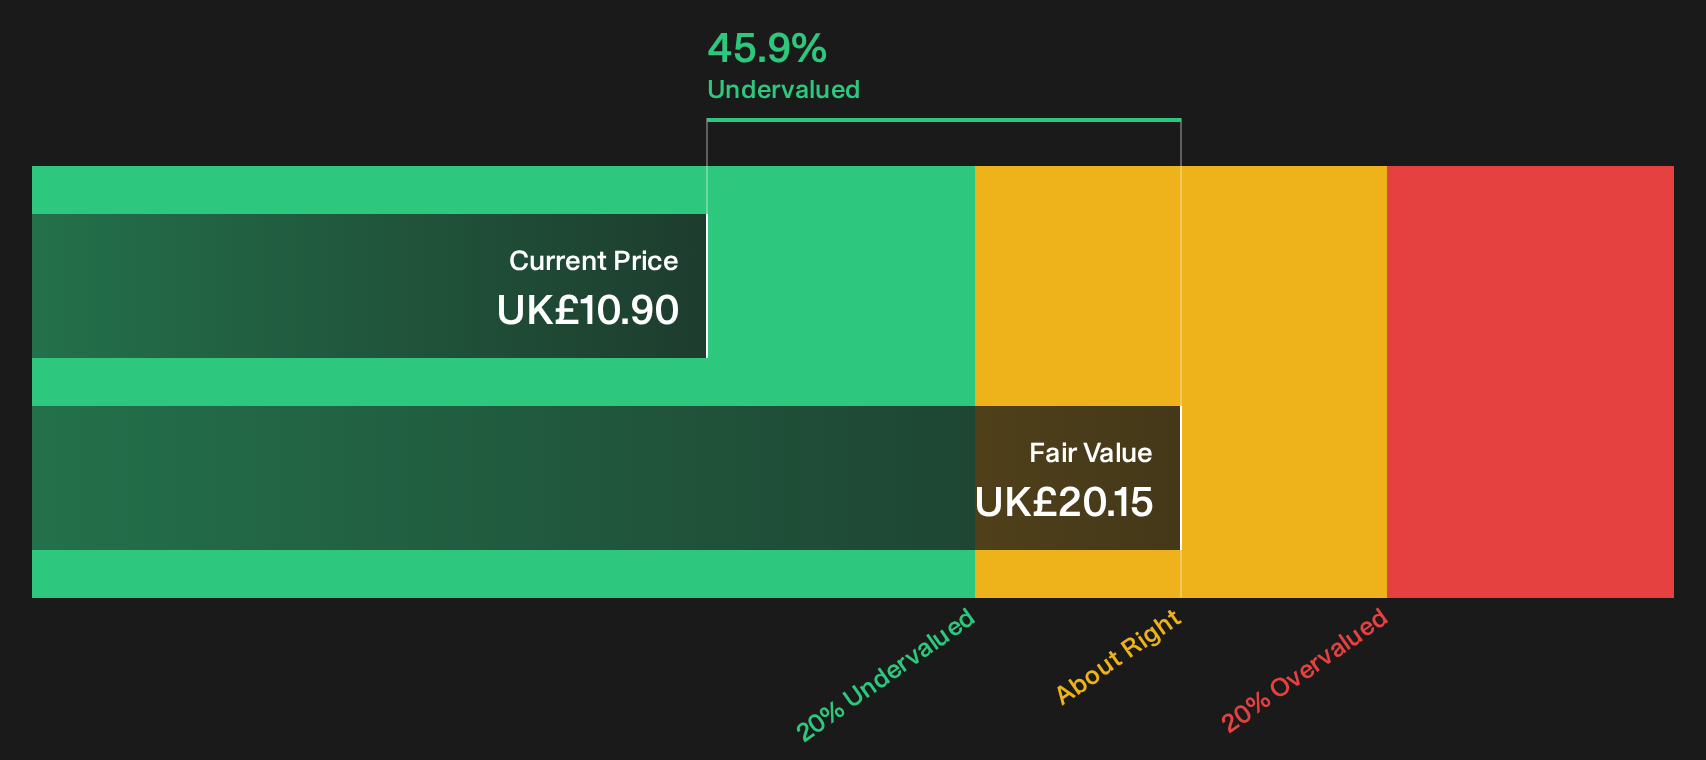
Smith & Nephew (LSE:SN.)
Smith & Nephew is a £9.1b medical devices group whose cash flow story leans heavily on its Orthopaedics arm, where knee and hip implants can generate repeat demand, while Sports Medicine & ENT and Advanced Wound Management round out a broad surgical and wound care portfolio.
Orthopaedics brought in about $2.5b, with Sports Medicine & ENT at roughly $2.0b and Advanced Wound Management near $1.8b, giving Smith & Nephew a sizeable mix of implant led and consumable revenue streams that underpin its cash flow profile.
Smith & Nephew matters in this cash flow focused screen because its joint replacement implants and related instrumentation can support recurring, high margin device demand as populations age and procedures shift toward more advanced techniques.
Acceleration in new product innovation, such as expanded robotic-assisted surgery (CORI, CORIOGRAPH), new implants (CATALYSTEM Hip, TRIGEN MAX Tibia Nailing), and significantly increased contributions from recent product launches (75% of H1 growth from products <5 years old), is described as positioning the company to capture greater market share and maintain higher revenue as global demand for advanced orthopaedic and minimally invasive solutions develops.
What happens if one unresolved pressure on how much value investors place on those future cash flows shifts even slightly from here?
If that shift materialises even partially, the full narrative for Smith & Nephew lays out where Smith & Nephew’s cash flows could be accelerating, stalling or quietly masking risk and upside.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once momentum builds and capital floods in, ideal entry points get caught up or drop away under the radar for now, so consider acting sooner rather than later.
- Target steadier compounding by scanning a curated pool of companies built to withstand shocks using the list of solid balance sheet and fundamentals (9 results).
- Review structural demand for smarter power by looking at carefully filtered infrastructure players inside the 42 power grid technology and infrastructure stocks.
- Explore potential breakout technologies by assessing focused opportunities through the 25 quantum computing stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com