
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Telia Company (OM:TELIA) Following 900 Job Cuts Is Its Valuation Still Fair
Telia Company (OM:TELIA) announced a major restructuring plan that includes about 900 position cuts and SEK 1 billion in targeted annual gross cost savings. The company expects most of the cash flow effects to occur from 2027 onward.
Telia Company’s restructuring news lands after a strong run, with the share price up 16.54% year to date and a 7 day share price return of 6.08%, while total shareholder return of 34.95% over one year and 123.66% across three years suggests that investors have already been rewarded for taking on the associated risks.
Scan how Telia Company's restructuring story compares with other hand picked operators targeting efficiency gains through cost cuts and cash flow improvement using the list of solid balance sheet and fundamentals (202 results).
Telia Company’s sharp rerating has come alongside restructuring plans and improving reported earnings, rather than a wave of euphoric headlines. Is this valuation now anchored in fundamentals or drifting on sentiment ahead of the next leg of analysis?
Most Popular Narrative: 1% Undervalued
Telia Company's most followed narrative points to a fair value of SEK46.60, almost in line with the latest close at SEK46.22. This puts the recent restructuring plan in the context of a business already priced for disciplined execution rather than a turnaround gamble.
Continued execution of cost efficiency programs, such as headcount reductions, early AI use in customer service and capex kept below SEK 13b, supports EBITDA margin expansion and free cash flow that covers the dividend and leaves room to strengthen the balance sheet. Transformation and portfolio restructuring, including the exit from non core markets, the sale of part of the Finnish ICT operations with limited EBITDA impact and the Bredband2 acquisition, are reshaping Telia Company toward higher margin connectivity and improving the mix of earnings and return on capital.
See why 14 investors see Telia Company as 1% undervalued.
Result: Fair Value of SEK46.60 (UNDERVALUED)
Still, Telia Company’s narrative can wobble if Norwegian EBITDA weakness persists or if Finnish competition keeps service revenue and group earnings under pressure.
Find out about the key risks to this Telia Company narrative.
Another View: Valuing Telia Company On Earnings Multiples
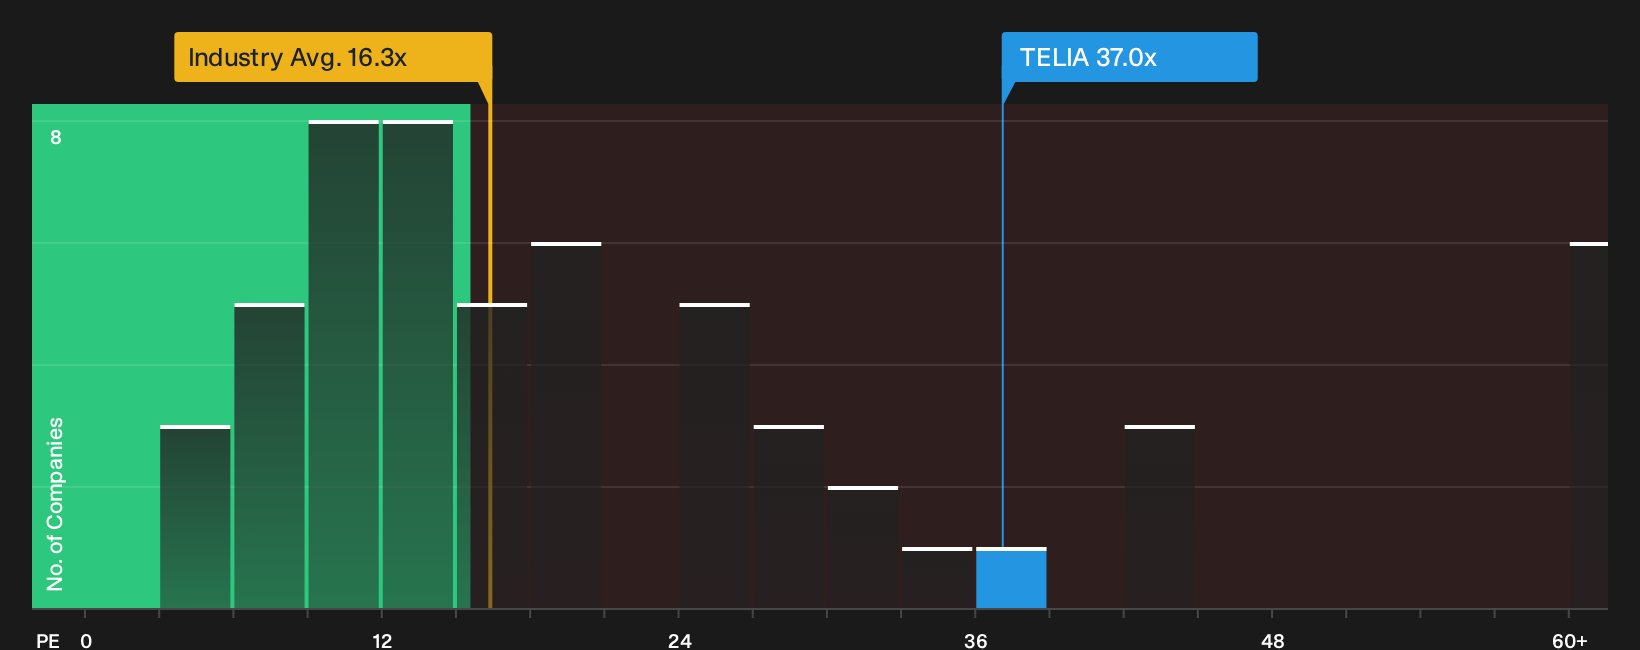
On one hand, Telia Company screens as cheap against an internal fair value estimate, trading 60.5% below that figure. On the other, the stock changes hands at a P/E of 37x, compared with 16.3x for the European telecom group, 15.1x for peers and a fair ratio of 24.5x.
That gap points to meaningful valuation risk if sentiment cools faster than earnings progress, especially with earnings growth and margin expansion still needing to be delivered in full. The question for investors is simple: does the current price justify paying a premium today for that future execution or not?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strong run or froth building? Either way, the only view that matters is your own. Review the full picture and weigh the 2 key rewards and 2 important warning signs.
Looking for more Telia Company sized opportunities?
If Telia Company feels fully priced to you, broaden your watchlist now. Fresh ideas help you compare quality, manage risk, and avoid anchoring on one story.
- Spot potential bargains early by scanning a curated pool of resilient opportunities through the 188 high quality undervalued stocks.
- Target resilient income ideas by reviewing companies that qualify as 221 dividend fortresses.
- Prioritise sleep-at-night holdings by focusing on companies screened as 228 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com