
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What NKT (CPSE:NKT)'s Hamburg Grid Contract Means For Shareholders
- Hamburger Energienetze has awarded NKT three high-voltage AC onshore cable projects in Hamburg, covering more than 50 kilometres of 110 kV XLPE cables and full-scope delivery from planning through commissioning.
- The projects feed directly into Hamburg's "Grid of the Future" programme, highlighting how NKT's local manufacturing footprint and turnkey execution capability align with rising electrification and grid modernisation needs.
- Next comes a look at how NKT's investment narrative could be influenced by this full-scope Hamburg grid contract and local production.
Scan beyond NKT and this Hamburg grid contract by reviewing the hand-picked 42 power grid technology and infrastructure stocks that is shaping tomorrow's electrification build out across transmission, distribution and supporting technologies.
NKT Investment Narrative Recap
NKT attracts investors who believe large scale grid investment and a sizeable high voltage backlog can offset near term growing pains. The Hamburg award supports that view but does not fundamentally change the immediate picture. The key near term catalyst remains how effectively new capacity and large projects move from ramp up into smoother, more predictable execution.
The biggest risk remains the squeeze between flat or softer transmission revenue in 2026 and higher operating costs from the €2b capex program. This Hamburg distribution win helps demonstrate demand and utilisation potential, but it does not remove the pressure on margins, free cash flow or pricing power if capacity stays underused.
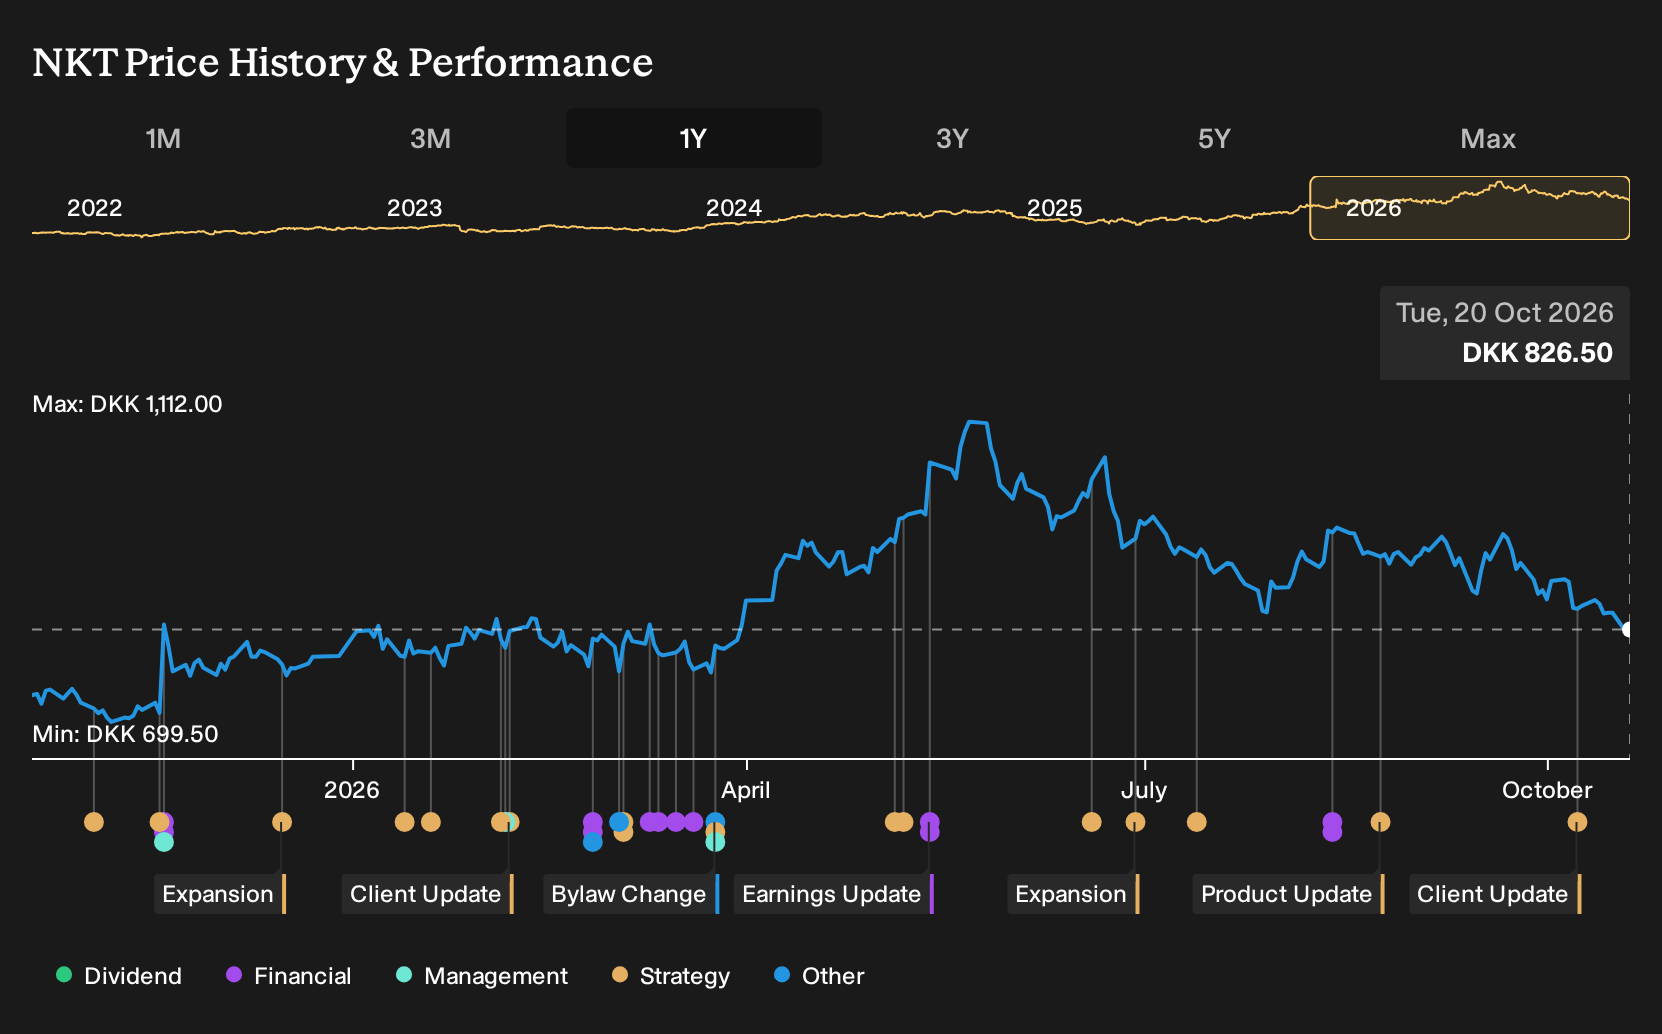
The Hamburg grid work connects directly with NKT’s broader expansion in high voltage production, especially at Cologne. Order visibility has already increased, with the high voltage backlog referenced at about €13.0b to €13.5b by mid 2026. A full scope contract that uses German and Czech plants is consistent with the trend of tying new physical assets to specific projects.
For you as a shareholder, the operational question is straightforward: can NKT convert this and similar onshore opportunities into steadier utilisation of factories, vessels and accessories after a year where transmission revenue is expected to decline by a mid single digit percentage? Execution on these contracted projects, including Hamburg, will be an ongoing test of that catalyst and of cost discipline.
NKT Forecasts Behind The Hamburg Contract Story
NKT's narrative projects €5.3b revenue and €471.0m earnings by 2029. This assumes 14.0% yearly revenue growth and an earnings increase of €203.0m from €268.0m today.
Analysts are effectively asking you to connect the Hamburg contract, the wider grid backlog and a fairly punchy revenue profile. The forecast points to 14.0% annual top line expansion over the next few years, alongside profit margins that are expected to move from 7.5% to 8.8%. That margin lift does a lot of work in the model, because it underpins the step up in forecast earnings from €268.0m today to €471.0m by 2029.
The implied earnings bridge matters for anyone weighing the Hamburg award. To get from €268.0m to €471.0m, NKT would need to add roughly €203.0m of extra profit over the period. Part of that gap is linked in analyst thinking to better utilisation of fresh capacity in places such as Cologne, cleaner execution on high voltage work and a richer mix of projects like Hamburg that bundle accessories and services with cabling.
Those same projections sit inside a valuation framework that uses a P/E reset. The consensus view looks for NKT to trade around 18.7x those 2029 earnings, compared with 22.4x today and about 22.3x for the GB Electrical peer group. That means the story analysts are sketching is not one of multiple expansion, but of the share price being supported by growth in earnings if the Hamburg type contracts and the broader €2b capex program deliver the forecast financial profile.
Uncover why NKT's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate, more optimistic angle on NKT focuses on earnings power rather than capacity risk. Bullish analysts were already sketching revenue of €6.0b and earnings of €503.8m by 2029 before this Hamburg win, assuming 18.6% yearly top line growth. You can treat this contract as a fresh reason to revisit those competing narratives.
Explore 3 other NKT fair value estimates, including one that suggests as much as 119% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NKT research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NKT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NKT's overall financial health at a glance.
Looking For More Ideas Beyond NKT?
If you want to put the NKT story in context, the next step is to line it up against other listed businesses that share similar qualities or offer very different risk profiles. The Simply Wall St Screener can help you do that in a structured way so you are not just reacting to headlines.
- For investors who prioritize quality at a reasonable entry point, consider screening for 188 high quality undervalued stocks that combine stronger fundamentals with more modest expectations baked into the price.
- If capital preservation and a smoother ride matter most to you, focus on a 228 resilient stocks with low risk scores that have lower risk scores based on balance sheet strength and earnings stability.
- When you want resilience in tough conditions as well as growth potential, filter for a list of solid balance sheet and fundamentals (202 results) that can fund expansion without stretching their finances.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com