
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Saab Holders Got Right
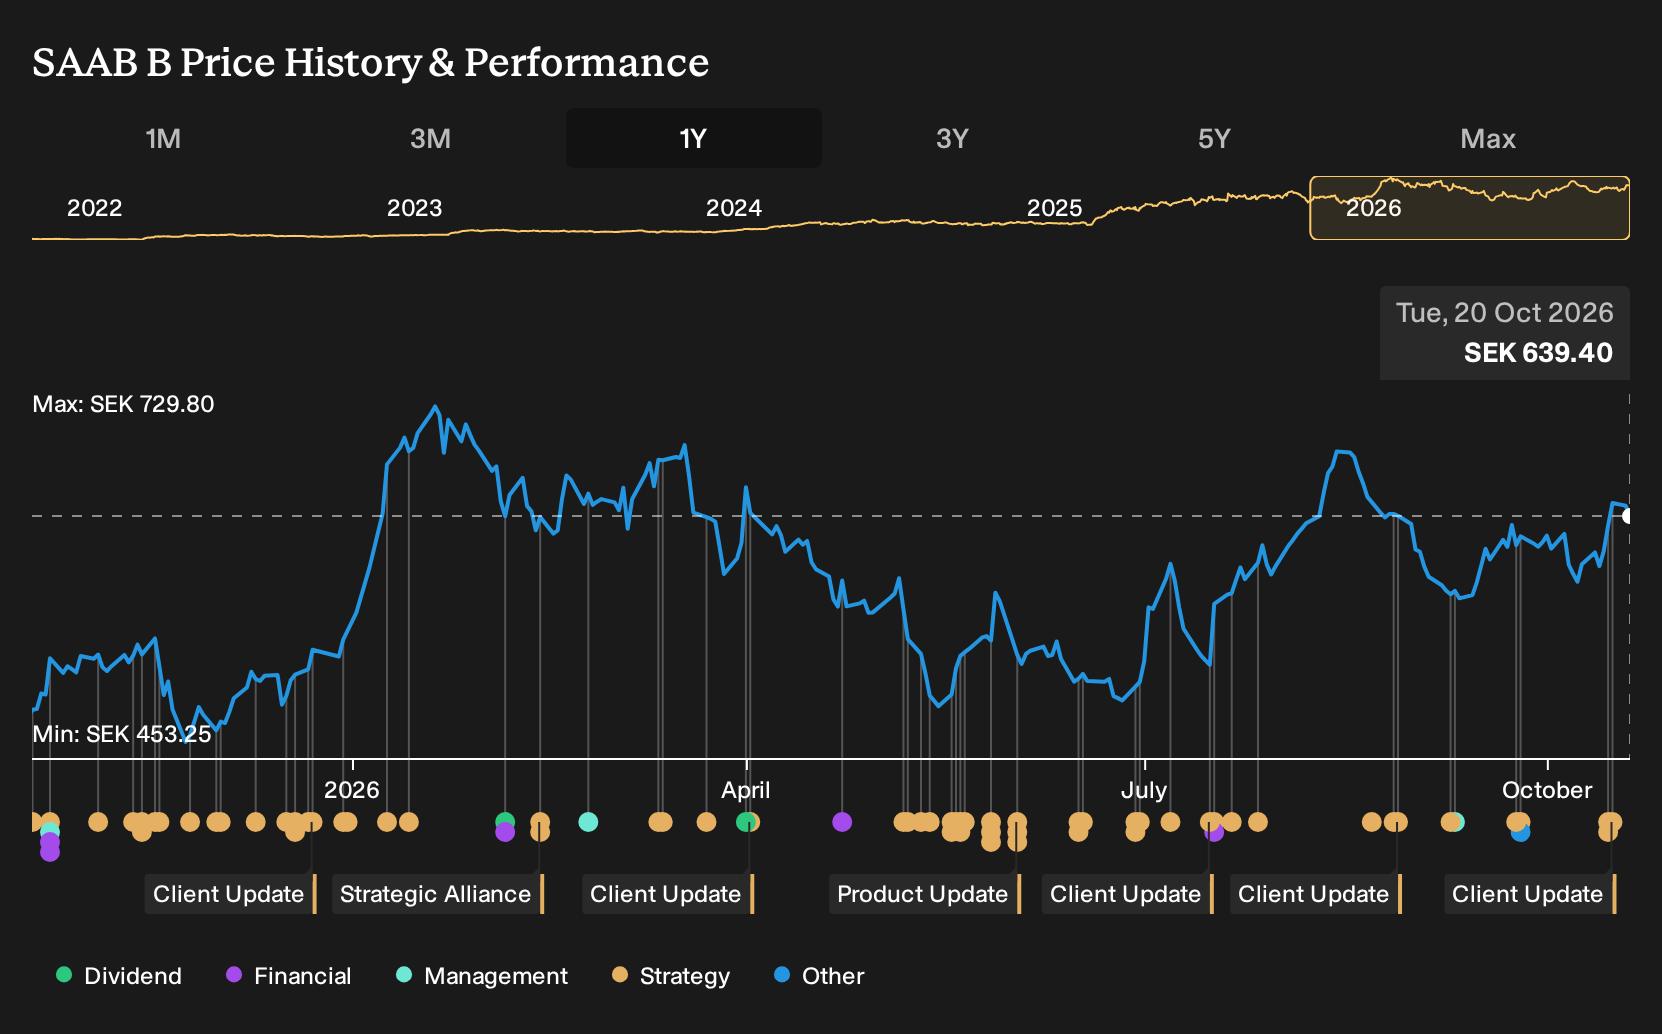
If you picked a defense stock for its order book rather than its headlines, Saab has just served up an interesting case study. For Saab shareholders, the return over the past year was 33.6%, including dividends. If you were weighing a purchase back on 20 October 2025, you had bullish analysts arguing for AI-powered Gripen jets and GlobalEye demand, while others warned about ESG pressure and government budget risk. Which of those competing stories looked sturdier on the information available then?
Saab has already moved. See which of 188 high quality undervalued stocks still trade below our estimates.
The Two Saab Stories Investors Had To Choose Between
The shares cost SEK480 at the start of the period, and anyone looking at Saab then had to decide which of two very different stories felt more realistic.
The bullish camp saw a Fair Value of SEK565, a price that would only make sense if Saab's advanced AI projects, including AI-enabled Gripen fighters and GlobalEye, helped it capture a larger share of rising modernization budgets. That view rested on revenue growing 17.8% a year and margins lifting from 7.4% to 8.8%.
The bearish side put Fair Value at SEK374, implying the market was already too optimistic even if revenue grew 15.9% annually and margins edged up to 8.5%. Their concern was that tighter climate rules, ESG pressure, export controls, and reliance on large government contracts could restrict future orders and leave earnings on a shakier footing.
What The Evidence Did To The Saab Argument
Saab reported Q2 2026 revenue of SEK25,453m and net income of SEK2,142m, with net margin rising to 8.4%. That combination of higher sales and thicker profitability, plus a record US$33b order backlog supported by the Polish A26 submarine award, lined up more closely with the bullish order book and margin story.
The useful lesson is to test any upbeat narrative about modernization against two things: order backlog growth in currency terms and the direction of net margin in the actual financials.
What Saab's Run Leaves You Paying For Today
Saab now trades at SEK639, and the selected Narrative sees its Fair Value below that level. The argument is that the share price has moved faster than the underlying ability to turn a record pipeline into delivered hardware.
If you pay SEK639, you are effectively assuming Saab can scale production smoothly enough that manufacturing capacity keeps pace with the current order flow.
"Given its diversified portfolio, solid balance sheet and consistent order growth, analysts see room for continued upside. A fair value range of SEK 650 to 700 per share appears reasonable if margins are maintained and new programs are executed as planned."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Saab And A Very Different Frontier
Saab shows how long contract cycles can reshape a defense supplier's path. You could also look at a place where launches, not jets, define most work.
Instead of fighters and submarines, this business focuses on putting hardware into orbit. It designs rockets and the satellites that ride on them.
That mix lets customers buy both the ride and the payload. The model depends on keeping launch costs controlled while still building reliable spacecraft.
If more activity shifts into orbit, those bundled services could matter more for buyers. The open question is how smoothly that shift can fund itself over time.
One Narrative has already put a figure on it. → Uncover the company trading 48% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com