
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
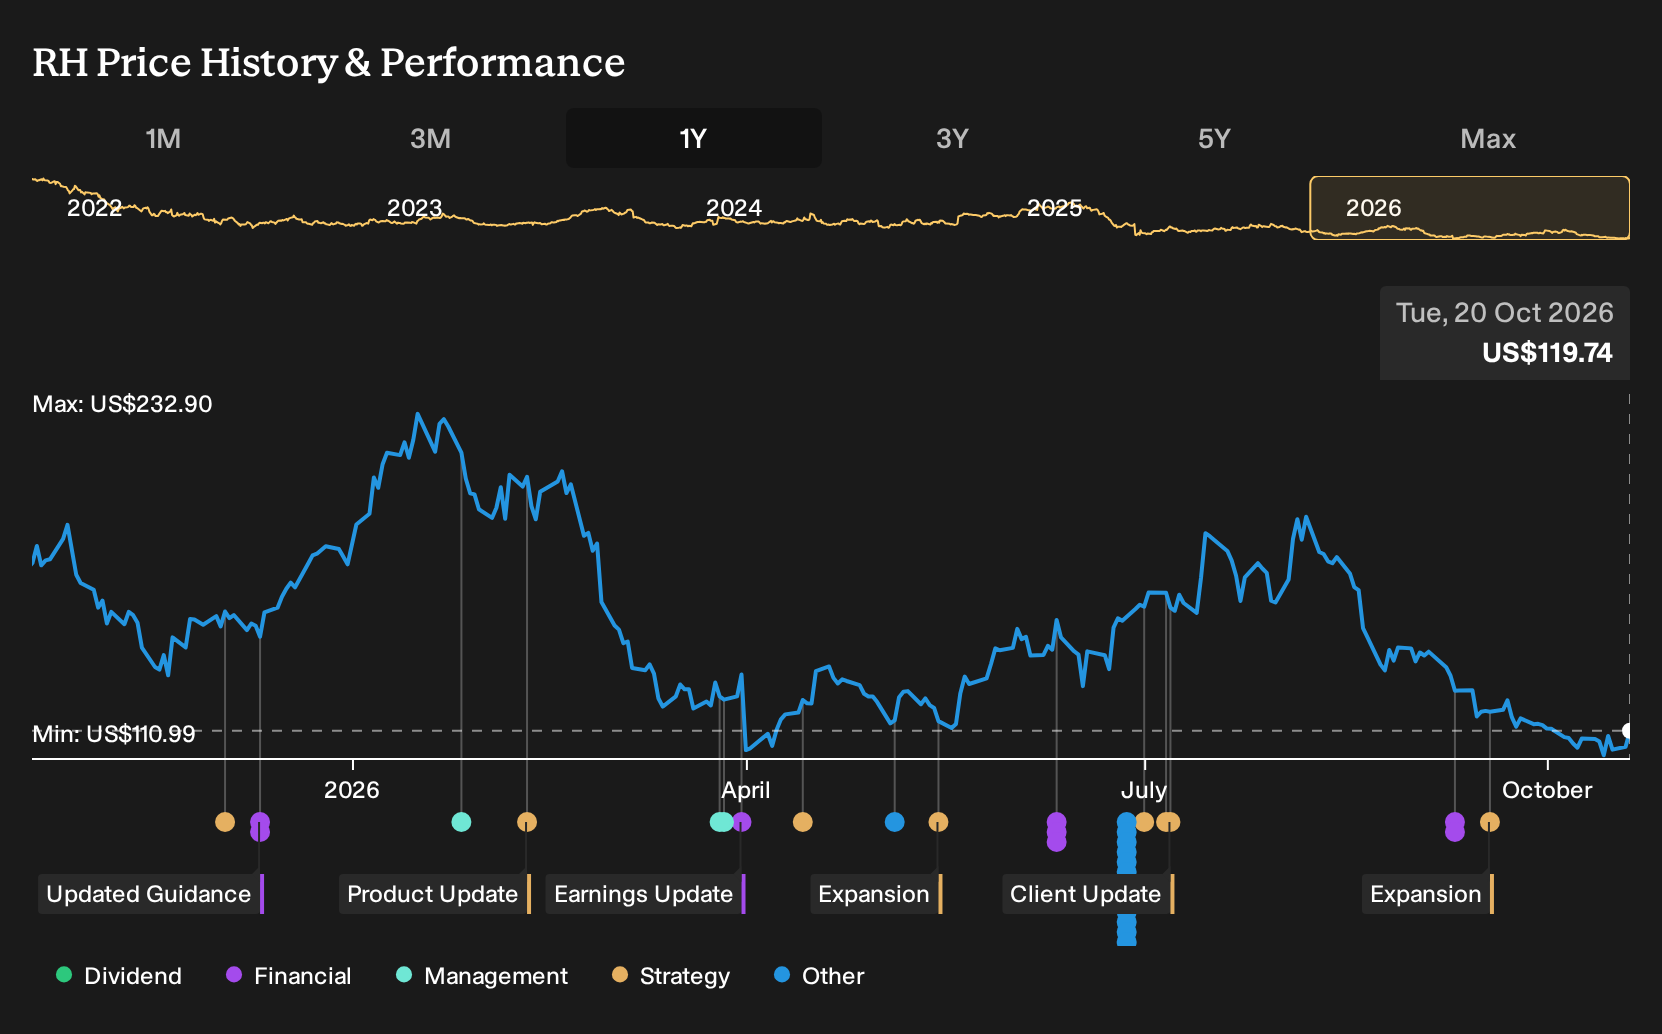
RH Stock Faces Funding Questions As Weak Growth And High Debt Test The Bull Case
- RH has faced weak sales expansion, a sharp drop in earnings per share, and a stretched net-debt-to-EBITDA position over the past three years, while trading on a forward P/E of 17.3x.
- The combination of softer operating results and higher leverage raises the risk that RH may eventually rely on equity funding that could dilute existing shareholders if lenders become less willing to extend credit.
- We will now look at how investor worries about RH's elevated net-debt-to-EBITDA ratio could reshape the broader investment narrative.
Broaden your watchlist beyond RH by reviewing a hand-picked 31 resilient stocks with low risk scores that may better align with the balance-sheet resilience you want in this kind of credit-sensitive story.
RH Investment Narrative Recap
To own RH, you need to believe the heavy investment in galleries, RH Estates and international flagships can translate into steadier demand and healthier margins, despite recent weak sales expansion and the drop in earnings per share. The short term swing factor is execution on that physical first model while the housing market and high ticket spending stay fragile.
The biggest near term risk is simple. Elevated net debt and interest that is not well covered by earnings limit flexibility if trading stays soft. The recent focus on leverage makes the balance sheet itself a catalyst, because any pressure from lenders could force RH to prioritize cash generation over growth projects.
With no fresh operational announcements tied to this update, the earlier plan to monetize roughly US$500 million of real estate matters most here. Management has guided to US$200 million to US$250 million of asset sales per year, which sits directly against worries about net debt and interest coverage.
If RH executes on those disposals and capital expenditure steps down from peak levels, the business gains more breathing room to let RH Estates, new galleries and the European flagships mature. That path keeps the equity dilution risk in clearer focus for you and turns cash conversion and asset sale progress into key data points to track quarter by quarter.
What The RH Forecasts Assume
RH's narrative projects US$4.5b revenue and US$308.5 million earnings by 2029. This implies analysts are baking in 9.6% yearly revenue growth and an earnings increase of about US$197 million from US$111.5 million today.
Uncover why RH's fair value indicates a 38% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic RH analysts focus on capital discipline as the key swing factor, rather than the housing or credit backdrop. Before this news, the bullish camp was assuming revenue of about US$4.8b and earnings near US$317.8 million by 2029. Those expectations could shift. Use this moment to compare several competing stories.
Explore 4 other RH fair value estimates, including one that suggests as much as 106% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RH research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for RH. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RH's overall financial health at a glance.
Looking For More Investment Ideas Beyond RH?
Once you are clear on how RH fits into your plan, it can help to set it alongside a few contrasting opportunities that offer different risk and income profiles.
- If you want potential mispricing combined with balance sheet support, review a curated 34 high quality undervalued stocks that may line up with your return and risk expectations.
- If reliable income is higher on your priority list, scan a focused 8 dividend fortresses that screens for companies offering stronger yields with supporting fundamentals.
- If capital preservation matters most, compare RH against a carefully filtered 31 resilient stocks with low risk scores that emphasizes resilience over aggressive upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com