
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Boyd Gaming (BYD) Stock Looks Below Fair Value At This Level
Boyd Gaming has given long term holders a mixed ride, with a 3 year gain alongside weaker recent returns, which naturally raises the question of whether today's US$71.62 share price still lines up with the earnings that support it. For anyone considering the stock now, the key issue is how much of the casino operator's profit power is already built into that tag.
- The share price has risen 21.0% over the past 3 years, which puts real weight on the question of how firmly its earnings can underpin that journey.
- The business leans heavily on cash flow from established gaming properties, so the durability of those earnings and the reinvestment needs of its venues can shape how much value investors ascribe to each dollar of profit.
- Your read on Boyd Gaming is one view; the desks covering it have another. See what analysts think Boyd Gaming's shares could be worth.
The issue now is whether Boyd Gaming's current share price is appropriately matched to the earnings power that shareholders are paying for.
If you are weighing whether Boyd Gaming's current P/E leaves enough upside on the table, it can help to compare that question across 34 high quality undervalued stocks.
Is Boyd Gaming a Bargain on Earnings?
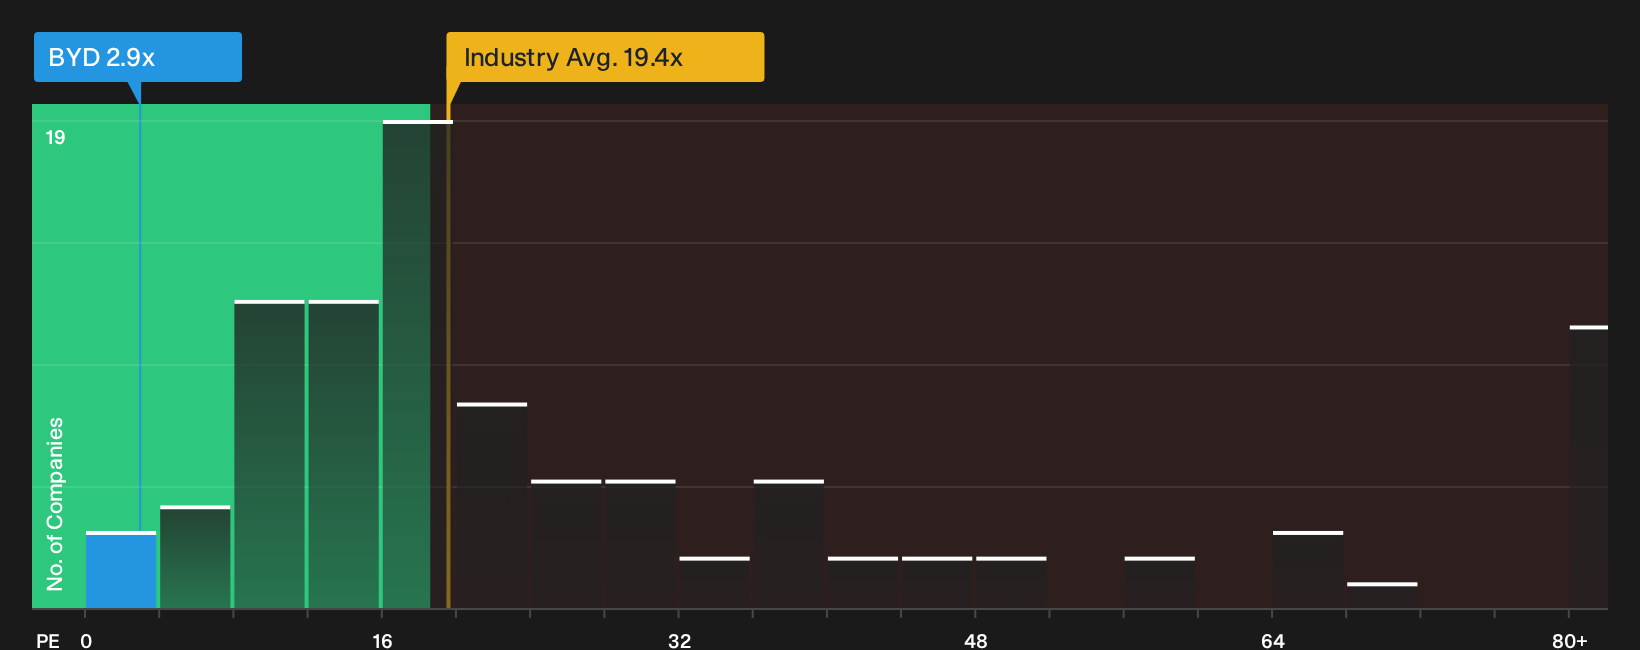
The P/E lens fits Boyd Gaming because earnings power is central to how investors usually look at casino operators. On this measure, Boyd Gaming trades on a P/E of 2.9x, which is far below the Hospitality industry average of 19.4x and well under the broader peer group on 16.0x. That is a wide gap for a business that is priced on its ability to convert gaming activity into profit rather than on speculative future projects.
The fair multiple model, which weighs Boyd Gaming's growth profile, profitability, size and risk, points to a higher P/E than the current market rating. That puts the present 2.9x level in undervalued territory on this framework, suggesting the market is assigning a cautious tag to each dollar of earnings compared with what this model would imply. For anyone weighing the stock today, the key question is whether that low earnings multiple reflects risks that are not easily captured in a single ratio, or whether sentiment has simply become too pessimistic. Explore the numbers behind Boyd Gaming's P/E valuation.
The Boyd Gaming Narrative: What Would Justify Today's Price?
Simply Wall St's Narratives for Boyd Gaming pick up where the valuation puzzle leaves off by explaining which views on future growth, profitability and earnings would need to hold for the shares to look meaningfully higher or lower than today’s price. Each narrative connects its number to a clear stance on how Boyd Gaming's growth, margins and risk profile might evolve, giving you a reference point you can revisit as new information becomes available.
One of the top community narratives on Boyd Gaming: 25% undervalued
"The current valuation implies the market is not fully crediting Boyd Gaming for its capital return program and emerging asset light earnings…"
Discover why this Narrative puts Boyd Gaming at 25% undervalued.
Boyd Gaming's price is only one piece of the decision
Before making any call on Boyd Gaming, it helps to look past the figures and focus on who is running the show and how their pay packets line up with your interests. See who runs Boyd Gaming and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com