
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Danone (ENXTPA:BN) Backs Ohio Biogas Project, Is The Stock Still A Bargain?
Danone (ENXTPA:BN) has come into focus after partnering with PurposeEnergy on a $40 million anaerobic digestion facility in Ohio, turning organic waste from its largest U.S. yogurt plant into renewable biogas and soil products.
Recent price action has been mixed for Danone, with the share price up 3.88% over the past week but down 19.75% year to date. The one year total shareholder return has declined 19.06%, while the three and five year total shareholder returns are 24.11% and 28.34% respectively. This suggests long term holders have seen gains even as shorter term momentum has faded.
Scan beyond Danone and this single project by sizing up companies with similar profiles on the 228 resilient stocks with low risk scores, which highlights resilient balance sheets and steadier risk scores.
Given Danone’s weak year to date share performance and long term gains, plus a sustainability story now backed by real capital, does the current valuation still tilt the risk reward balance toward buyers or toward patience?
Most Popular Narrative: 23% Undervalued
On the most followed valuation narrative, Danone’s fair value of €79.68 sits well above the last close of €61.02. This puts the current share price at a clear discount and raises questions about whether sentiment has swung too far toward caution.
Continued innovation and expansion in health-driven, functional foods and specialized nutrition such as high-protein, probiotic, and medical nutrition products positions Danone to capture above-market revenue growth as global consumers become increasingly focused on wellness and science-based nutrition.
Geographic broadening in emerging markets, especially across Asia, Africa, and Latin America, leverages rising urbanization and the growing middle class to expand Danone's addressable market and drive long-term revenue and volume gains.
See why 32 investors see Danone as 23% undervalued.
The narrative relies on a €79.68 fair value, a 23% gap to the current price that is built on a 6.47% discount rate and steady rather than rapid growth assumptions for both revenue and profit margins. Analysts behind this view are not baking in very high expansion in sales or earnings. They still see scope for earnings to improve from €1.8b to €2.7b by June 2029 under their scenario, with net margin expectations moving from 6.7% toward just above 9%.
That kind of outcome would leave Danone trading on a P/E multiple of around 22x those future earnings. The narrative notes this is above the current 12.3x level cited for the GB Food industry. The story here is less about explosive growth and more about a shift toward higher value categories in specialized nutrition, plant based products, and medical nutrition, combined with efficiency gains from supply chain upgrades and cost discipline.
Analysts also assume a small annual reduction in the share count of 0.54% over the next few years. If achieved, this would support earnings per share even if top line expansion stays in the mid single digit range. With a value score of 4 out of 6 and the SWS DCF model indicating Danone at €61.02 trades 47.7% below an estimated future cash flow value of €116.72, the broader valuation work aligns with the idea that the current price embeds a fair amount of skepticism.
It is important to stress that the narrative is not blind to risk. Commentary in the same framework points to reliance on legacy dairy and water, execution challenges in North America, integration risk around acquisitions like Kate Farms and The Akkermansia Company, and ongoing pressure from input costs and regulation. Those elements help explain why the required P/E for the 2029 earnings, 22.1x, sits above the sector reference and why analyst price targets span a wide range from €59.00 to €95.00 even though the consensus target is €79.68.
For investors weighing Danone today, the key question is how much confidence to place in that medium term shift toward higher margin categories and operational efficiency, versus the drag from debt, low forecast return on equity of 15.1% in three years, and revenue growth that is projected at 4.2% per year, slower than the wider French market. It is a classic case where the current share price reflects near term unease after a weak year to date return, while the most followed narrative leans on a gradual but consistent improvement story.
Result: Fair Value of €79.68 (UNDERVALUED)
Still, Danone’s reliance on legacy dairy and water, together with ongoing execution issues in North America, could quickly undercut that medium term improvement story.
Find out about the key risks to this Danone narrative.
Another View: Danone Looks Expensive On Earnings
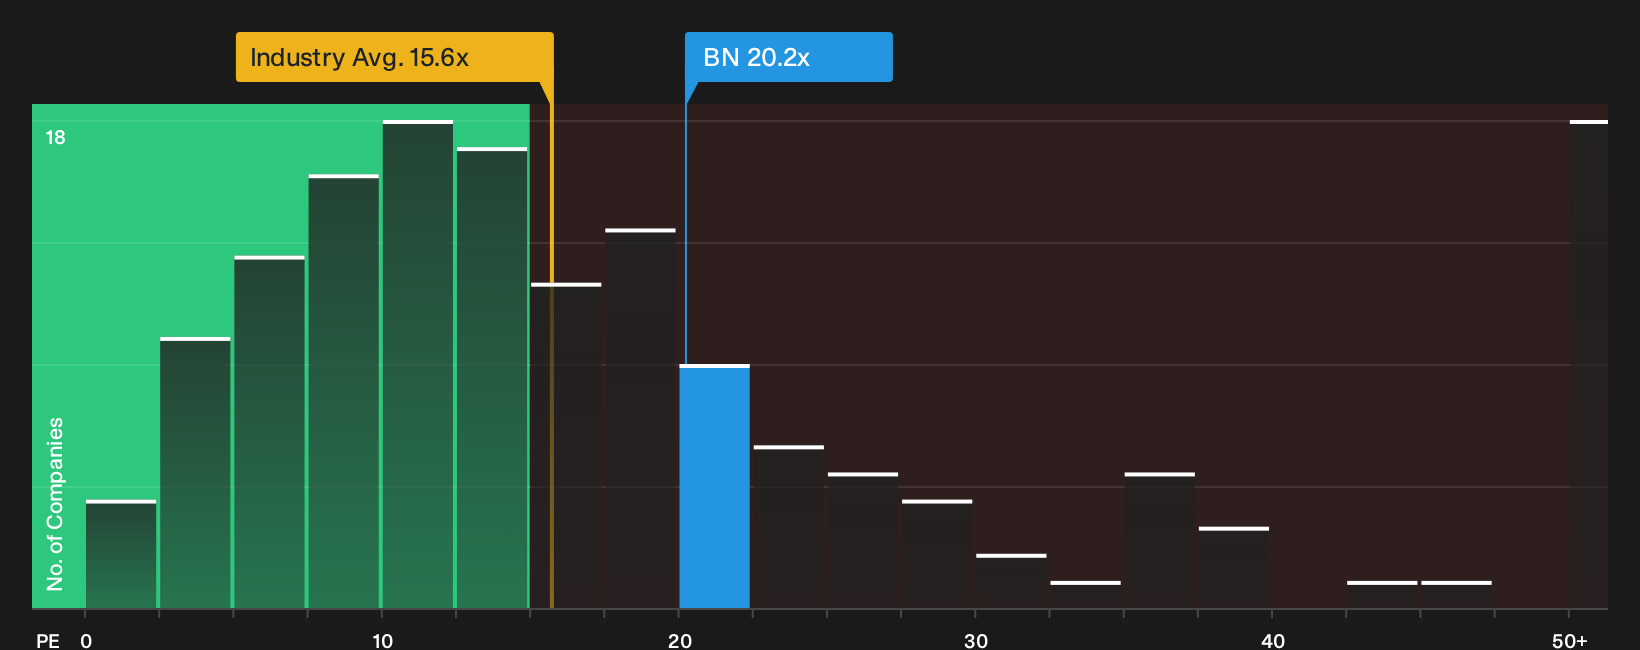
DCF work paints Danone as undervalued, yet the earnings multiple tells a different story. The current P/E of 20.2x sits well above both the European Food group on 15.6x and Danone’s own fair ratio of 22.4x that the market could move toward. Is that premium cushioning downside or narrowing future upside?
For anyone weighing this second lens on valuation, it is worth stress testing what would need to change in earnings quality or growth before paying more than both peers and the wider sector looks comfortable with. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if they sharpen your own thinking, so move quickly, check both sides of the story, then weigh the 5 key rewards and 1 important warning sign.
Looking for more ideas beyond Danone?
If Danone has sharpened your thinking, do not stop here. Fresh opportunities often sit just outside your current watchlist, waiting for a closer look.
- Target dependable balance sheets by scanning the list of solid balance sheet and fundamentals (202 results) to help anchor a portfolio when conditions get choppy.
- Hunt for mispriced quality by reviewing the 188 high quality undervalued stocks to combine stronger fundamentals with more conservative expectations.
- Stack potential income streams using the 221 dividend fortresses to focus on higher yields supported by sturdier financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com