
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Fagron (ENXTBR:FAGR) Issued New 2026 Revenue Guidance, Is It Still Undervalued?
Fagron (ENXTBR:FAGR) set the tone for trading on 8 October 2026 after issuing fresh guidance that points to expected 2026 revenue between €1,125 million and €1,150 million.
The fresh 2026 outlook has arrived after a year in which Fagron’s 1-year total shareholder return of 12.91% outpaced its year-to-date share price return of 8.28%, while the stock’s recent 7-day and 30-day share price gains suggest momentum has picked up again despite a slightly weaker 90-day patch.
Scan how Fagron’s fresh guidance compares with other potential opportunities by applying the same lens to our curated list of 188 high quality undervalued stocks.
Fagron now trades with a fresh 2026 revenue range on the table, and its share price still sits well below the average analyst target. Is the gap between price and fair value as wide as it looks, or already closing?
Most Popular Narrative: 17% Undervalued
Fagron’s most followed valuation narrative points to a fair value of €28.25 per share, compared with the last close at €23.55. This frames the fresh 2026 guidance against a market price that still trails that estimate.
The ongoing expansion into new regions including the recent entry into the APAC market via the Bella Corp acquisition and direct presence in the UK and Serbia positions Fagron to tap into growing global demand for personalized pharmaceuticals, supporting future revenue acceleration as demographic trends (aging populations, more chronic conditions) drive higher prescription volumes.
See why 14 investors see Fagron as 17% undervalued.
The narrative ties this outlook together using a 6.44% discount rate and assumes revenue growth of 11.67% a year and a net profit margin of about 10.47%. It also leans on analyst expectations that earnings could reach €138.8 million by 2029 with a future P/E of roughly 17.9x, which is slightly below the current sector benchmark cited in the narrative.
Under that framework, the share price gap to the €28.25 fair value hinges on investors agreeing that Fagron can convert its compounding services, automation spend and regional expansion into that earnings path. If those assumptions feel too optimistic or conservative to you, the key step is to adjust the growth, margin and discount inputs to reflect your own view of the business.
Result: Fair Value of €28.25 (UNDERVALUED)
Still, the story around Fagron can change quickly if regulatory scrutiny tightens on compounding activities, or if acquisition integrations drag on profitability longer than expected.
Find out about the key risks to this Fagron narrative.
Another View: What Fagron’s P/E Says
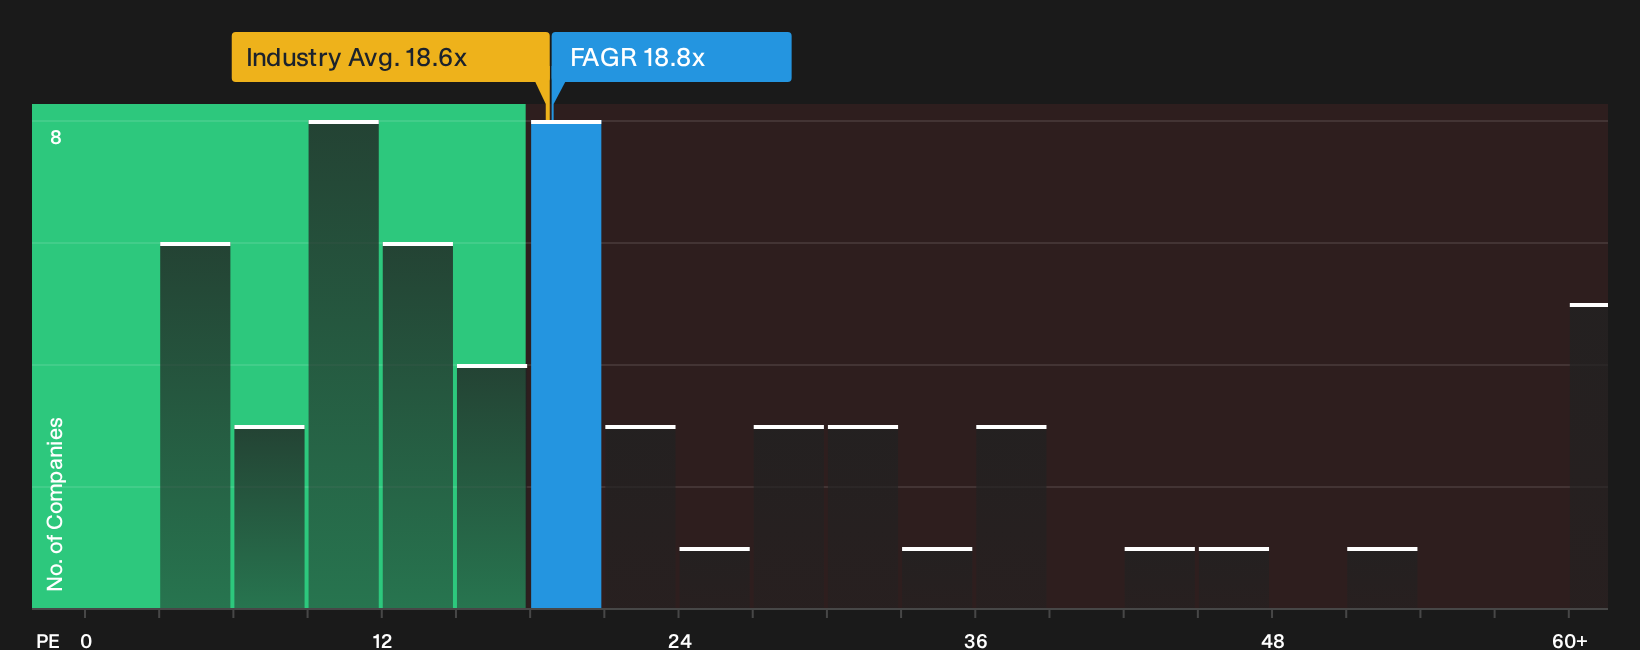
The DCF narrative presents Fagron as undervalued, yet the current P/E of 18.8x is above both the estimated fair ratio of 17.3x and the peer average of 17.6x. That richer earnings multiple can limit potential upside if growth or margins fall short of forecast. Which signal matters more to you?
To stress test this earnings based view against your own assumptions, take a closer look at the full valuation breakdown and how the fair ratio might change over time, then compare it with other healthcare stocks using similar checks. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of upside potential and clear risks around Fagron deserves your own filter, not just someone else’s model. Take a few minutes to review the evidence, test the assumptions that matter most to you, and then weigh up the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Fagron?
Do not stop with one stock. Broaden your watchlist using focused screeners that surface different types of opportunities, then decide which ones truly fit your plan.
- Target potential mispriced opportunities by scanning our curated 188 high quality undervalued stocks that pair quality fundamentals with a market price that still looks cautious.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (202 results) that can better withstand tougher conditions without stretching their finances.
- Boost your income focus by checking a hand picked 221 dividend fortresses that combine higher yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com