
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Lam Research (LRCX) Undervalued Following Record Results And Strong Guidance?
Lam Research (LRCX) just reported record quarterly results, including all-time highs in revenue, operating margin, and earnings per share. Strong demand tied to AI, 5G, and advanced automotive chips is driving that performance.
The strong quarter lands against a choppy tape. Lam Research’s share price is down 3.1% over the last day and 12.4% over the past week, extending a 17.4% decline across three months. However, the year-to-date share price return of 42.5% and 1-year total shareholder return of 82.6% show that momentum has been positive over a longer stretch.
Spot fresh AI infrastructure plays by checking out the hand picked 55 AI infrastructure stocks that echo the setup investors are watching around Lam Research.After a record quarter yet a sharp three month slide in the share price, Lam Research now forces a timing decision. Is this recent pullback enough of an entry, or does waiting for a deeper reset make more sense as valuation comes into focus?
Most Popular Narrative: 38% Undervalued
Lam Research closed at $263.64, while the most followed narrative pegs fair value at $423.85, which frames the recent pullback as a valuation gap rather than just a momentum swing.
The story behind this stock: Lam Research is the position I hold to be right about the AI memory bottleneck without having to be right about how long it lasts. That sentence is the entire thesis, so it is worth unpacking. Every direct memory holding such as Micron, SanDisk, or Seagate makes money while supply stays short and loses the argument the moment capacity catches up. Lam makes money on the shortage and makes money on the response to it, because the capacity that eventually relieves the shortage has to be bought from somewhere, and a very large share of it gets bought from Lam.
See why 37 investors see Lam Research as 38% undervalued.
Result: Fair Value of $423.85 (UNDERVALUED)
Still, the thesis around Lam Research can be knocked off course if memory makers suddenly cut capital spending, or if China export controls tighten further and restrict tool demand.
Find out about the key risks to this Lam Research narrative.
Another View: Multiples Say Lam Research Is Expensive
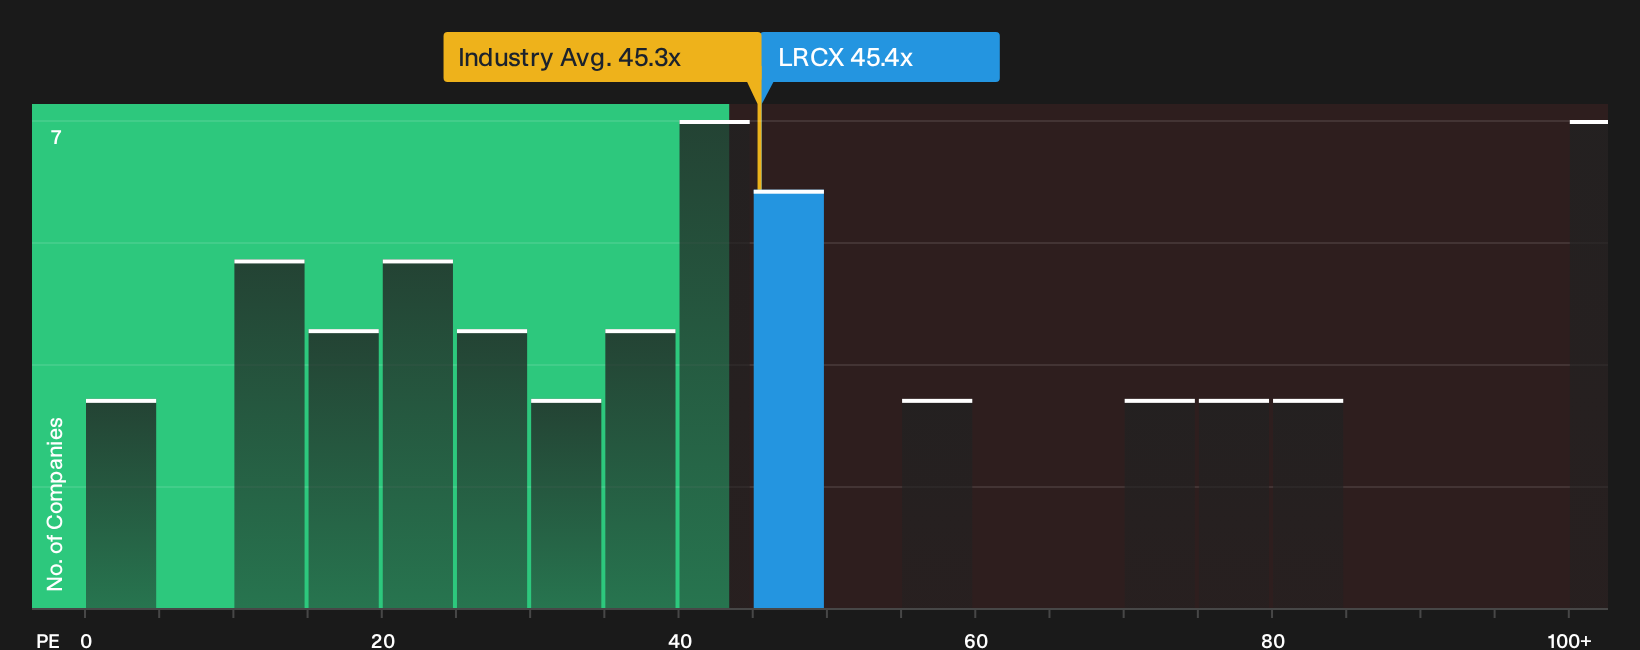
The fair value narrative frames Lam Research as 38% undervalued at $423.85, yet the current P/E of 45.4x tells a different story. That ratio is higher than the US Semiconductor industry at 45.3x, above peers at 41.6x, and slightly above the fair ratio of 44.5x. This implies less margin for error if expectations slip.
When a stock trades richer than both sector and peer averages and already sits above its own fair ratio, the risk is that strong execution is simply meeting the bar instead of beating it. The key question is how comfortable investors are with paying a premium for that level of precision.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Lam Research is split, and that is exactly when doing your own homework matters most. Move quickly, stress test both the upside and the downside, and weigh the 3 key rewards and 1 important warning sign.
Looking for more Lam Research style ideas?
If Lam Research has sharpened your focus, do not stop here. Cast a wider net with structured screeners that surface opportunities you might otherwise miss.
- Target financial strength first by running a list of solid balance sheet and fundamentals (25 results) that can highlight businesses with robust balance sheets and resilient fundamentals.
- Hunt for potential mispricing by scanning a 34 high quality undervalued stocks that filters for quality companies trading below their estimated worth.
- Lock in income-focused opportunities by reviewing a 8 dividend fortresses built around higher yielding payouts that may complement your growth holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com