
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nebius Group (NBIS) Stock Looks Reasonable As AI Spending Fears Deepen
Nebius Group has had a volatile run, with a strong multi year climb now meeting a sharp pullback and raising a simple question for investors. Does the current share price still line up with the company’s sales, especially after the recent AI infrastructure worries and funding concerns?
- Nebius has returned 124.9% over 5 years, which puts real weight on whether today’s valuation can be explained by the revenue the business generates.
- Gartner’s warning over potential impairment of trillions in AI infrastructure spending, together with questions around financing Nebius’s 600 MW Rotterdam data center, may reshape how investors think about the scale and timing of future sales and cash inflows.
- The analysts covering Nebius Group have run their own numbers. See what analysts think Nebius Group's shares could be worth.
The stock’s next move may depend on whether Nebius’s current market value is well supported by its sales base and the growth those sales can realistically deliver.
To pressure test Nebius Group's story against other AI infrastructure plays, compare it with companies in 55 AI infrastructure stocks
Does Nebius Group Look Fairly Valued on Sales?
P/S fits Nebius Group because investors are still mostly paying for future top line potential rather than current earnings power.
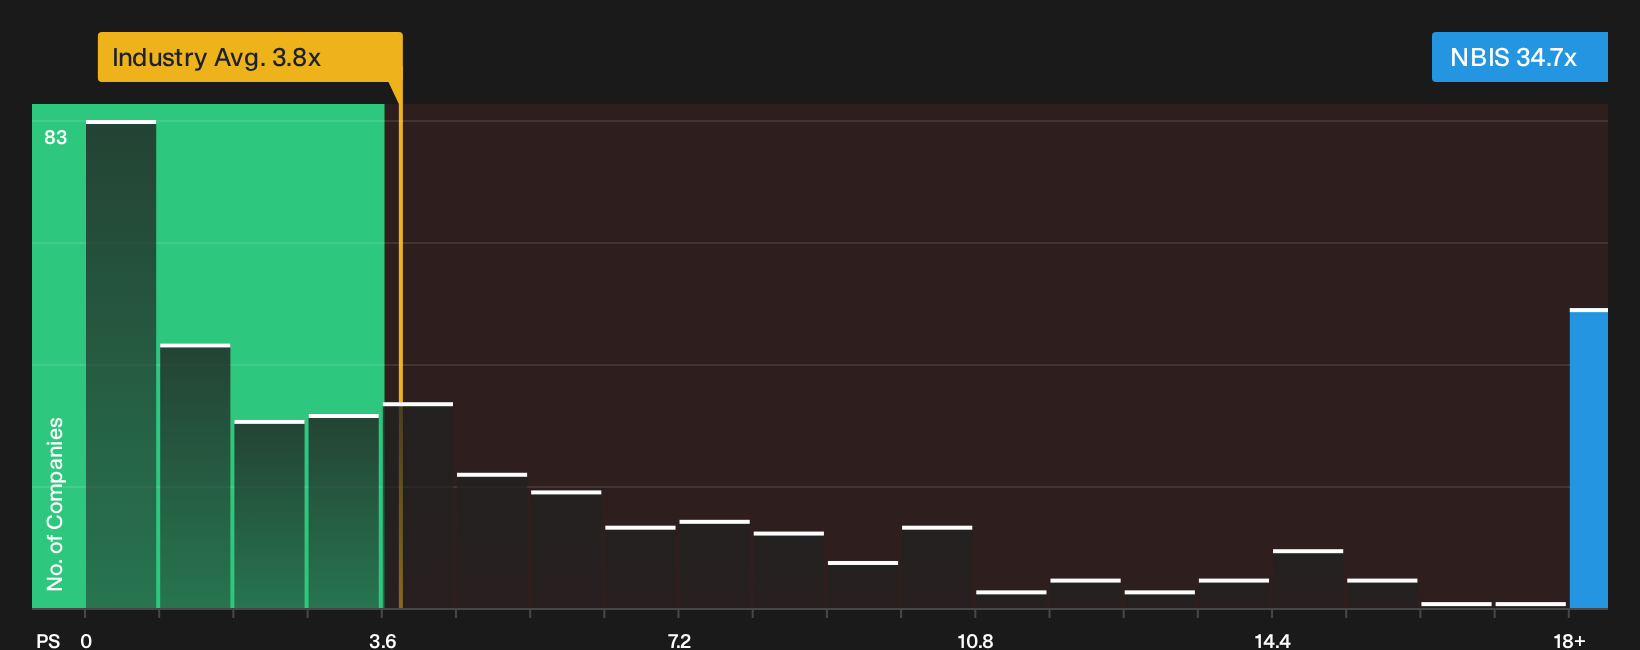
The stock trades on a P/S ratio of 34.7x, which is far above the Software sector average of 3.8x and also well above the 10.0x peer group level for AI infrastructure plays. On Simply Wall St’s fair multiple framework, which blends Nebius Group’s growth profile, margins, size and risk into a tailored benchmark, the current P/S sits close to the level that model would expect rather than dramatically above or below it. Because Gartner’s warning about possible impairment of trillions in AI infrastructure spend has already pressured Nebius’s share price, this valuation suggests the market still assigns a rich top line premium even after the pullback. Explore the numbers behind Nebius Group's P/S valuation.
The Nebius Group Narrative: What Would Justify Today's Price?
Nebius Group's valuation story only really comes into focus once you spell out the future that would need to unfold for the stock to be worth materially more or materially less than today’s price. This is where Simply Wall St Narratives on the Community page come in. Each scenario ties a fair value to a clear path for growth, margins and earnings, then links that to concrete catalysts and risks so you can track which version of events is actually playing out over time.
Community views on Nebius Group split sharply between those who see a premium AI asset and those who think expectations already stretch too far.
Bull case: 41% undervalued
"Nebius leverages rapid AI demand, global expansion, strategic partnerships, advanced technology, and strong funding to drive recurring revenue, margin growth, and long-term profitability…"
Discover why this Narrative puts Nebius Group at 41% undervalued.
Bear case: 48% overvalued
"Surging capital expenditures, as evidenced by the company's commitment to $2 billion in 2025 alone and a massive multi year plan to secure 1 gigawatt of power by 2026, will likely drive down free cash flow and pressure net margins for years…"
Explore why this Narrative puts Nebius Group at 48% overvalued.
Nebius Group’s price is only one piece of the decision
Shareholders are not just buying Nebius Group’s data centers and contracts. They are also backing the executives who allocate capital and the pay structures that shape their decisions. See who runs Nebius Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com