
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Curaleaf (TSX:CURA) Stock Looks Reasonable As Shares Fell 70%
Curaleaf Holdings has seen its share price under pressure in recent years, and the latest swings have put a fresh spotlight on what investors are really paying for its sales today. With a contentious takeover attempt for Aurora Cannabis now in the background, the central question is how well the current market value of Curaleaf lines up with the revenue it generates.
- Over the past 5 years, Curaleaf’s share price has fallen 70.3%, which puts a lot of weight on whether today’s valuation is properly anchored to its sales base.
- The dispute with Aurora over the adequacy of Curaleaf’s hostile offer highlights how differently parties can view the same revenue and potential synergies, which may shape how investors think about what Curaleaf’s own sales stream is worth on a standalone basis.
- The analysts covering Curaleaf Holdings have run their own numbers. See what analysts think Curaleaf Holdings's shares could be worth.
The stock’s next move may depend on whether Curaleaf’s current share price can be explained by its sales when measured against the Fair Ratio benchmark.
If you want a second reference point while you assess whether Curaleaf Holdings’ price lines up with its sales, it can help to scan other stocks using our 4 high quality undervalued stocks
Does Curaleaf Holdings Look Undervalued on Sales?
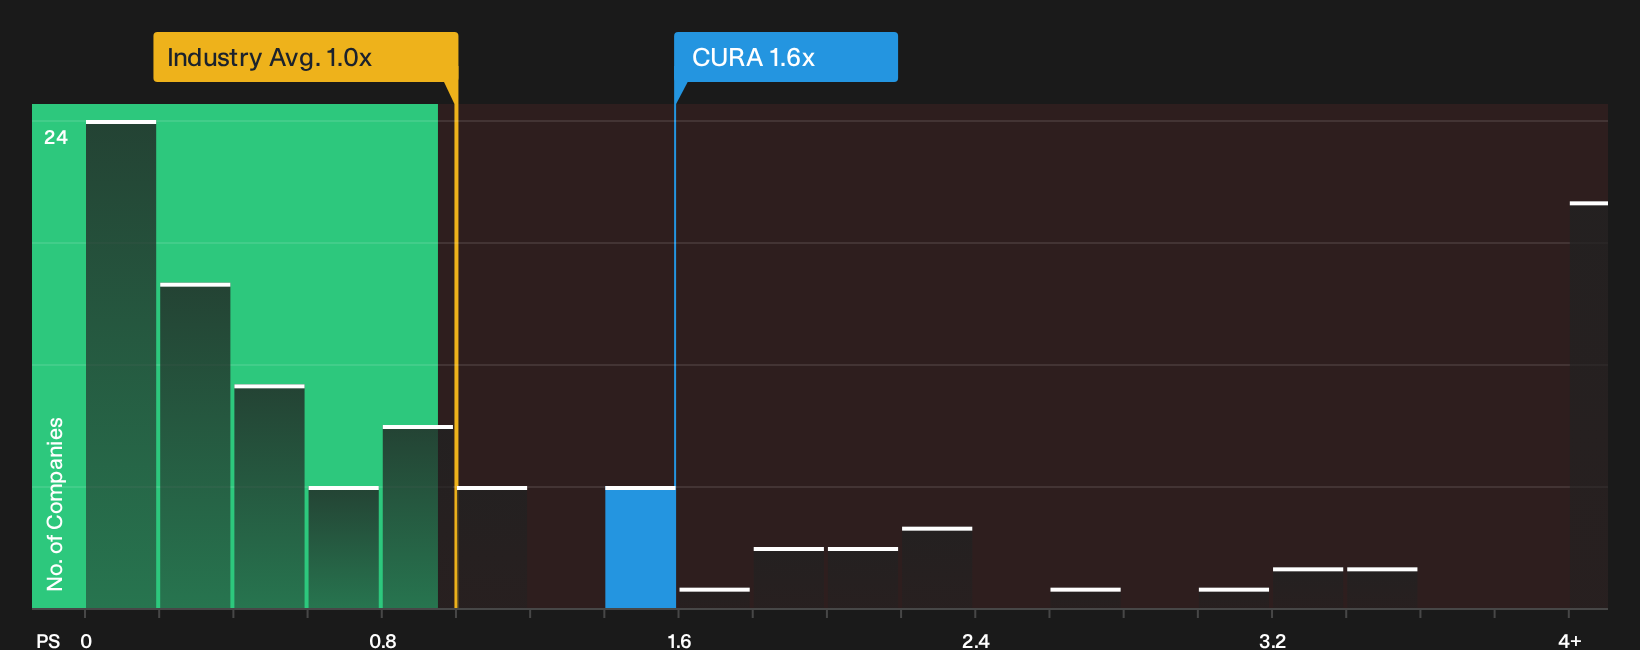
P/S fits Curaleaf Holdings because investors are currently paying more attention to its revenue line than to earnings, given the loss based P/E. Curaleaf trades on a P/S of 1.6x, which is above the wider Pharmaceuticals industry at 1.0x and beneath the 3.1x peer basket that includes more directly comparable cannabis operators.
The Fair Ratio, which blends the firm’s growth profile, margins, size and risk, points to a higher P/S than where Curaleaf is priced today, so the stock screens undervalued on this yardstick. Because Aurora has pushed back on Curaleaf’s valuation in the ongoing takeover dispute, the gap between this lower trading multiple and a higher implied Fair Ratio gives you a clear signal that the market is pricing Curaleaf’s own revenue stream cautiously. Explore the numbers behind Curaleaf Holdings's P/S valuation.
The Curaleaf Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Curaleaf Holdings build on this valuation puzzle and explain what kind of future growth, profitability and earnings profile would need to occur for the stock to be worth meaningfully more or materially less than today’s price. Each scenario links a fair value to a specific path of catalysts and risks, allowing you to track which version of Curaleaf Holdings' story seems to be taking shape over time on the Community page.
One of the top community narratives on Curaleaf Holdings: 40% undervalued
"Rapid expansion and regulatory breakthroughs in international markets, notably the strong sequential and yearly growth in Germany, new entry into Turkey…"
Discover why this Narrative puts Curaleaf Holdings at 40% undervalued.
Curaleaf Holdings’ valuation is only half the story
Price multiples tell you what the market thinks today, but recent insider transactions can hint at how people inside Curaleaf view the road ahead, including who has been selling and by how much. See the recent insider selling flagged for Curaleaf Holdings.

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com