
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Chewy (CHWY) Stock May Already Look Priced For Its Earnings
Chewy has seen its share price move around in recent years, and the current level raises a clear question for you as an investor. Is the price you see today adequately backed by the pet retailer's earnings power, or are expectations running ahead of what the business is currently delivering?
- Over the past 5 years the stock has fallen 68.3%, which puts the focus squarely on whether the present valuation is now more closely aligned with Chewy's underlying earnings profile.
- The business model leans on repeat spending from pet owners, and its ability to convert that customer loyalty into consistent profit margins can shape how much earnings support the current share price.
- There is a second opinion on Chewy worth weighing. See what analysts think Chewy's shares could be worth.
The stock's next move may depend on whether Chewy's current earnings base is strong enough to justify where the shares trade today.
If you want to test the same "is the price supported by earnings" question beyond Chewy, you can scan a wider field of 34 high quality undervalued stocks.
Does Chewy Look Pricey on Earnings?
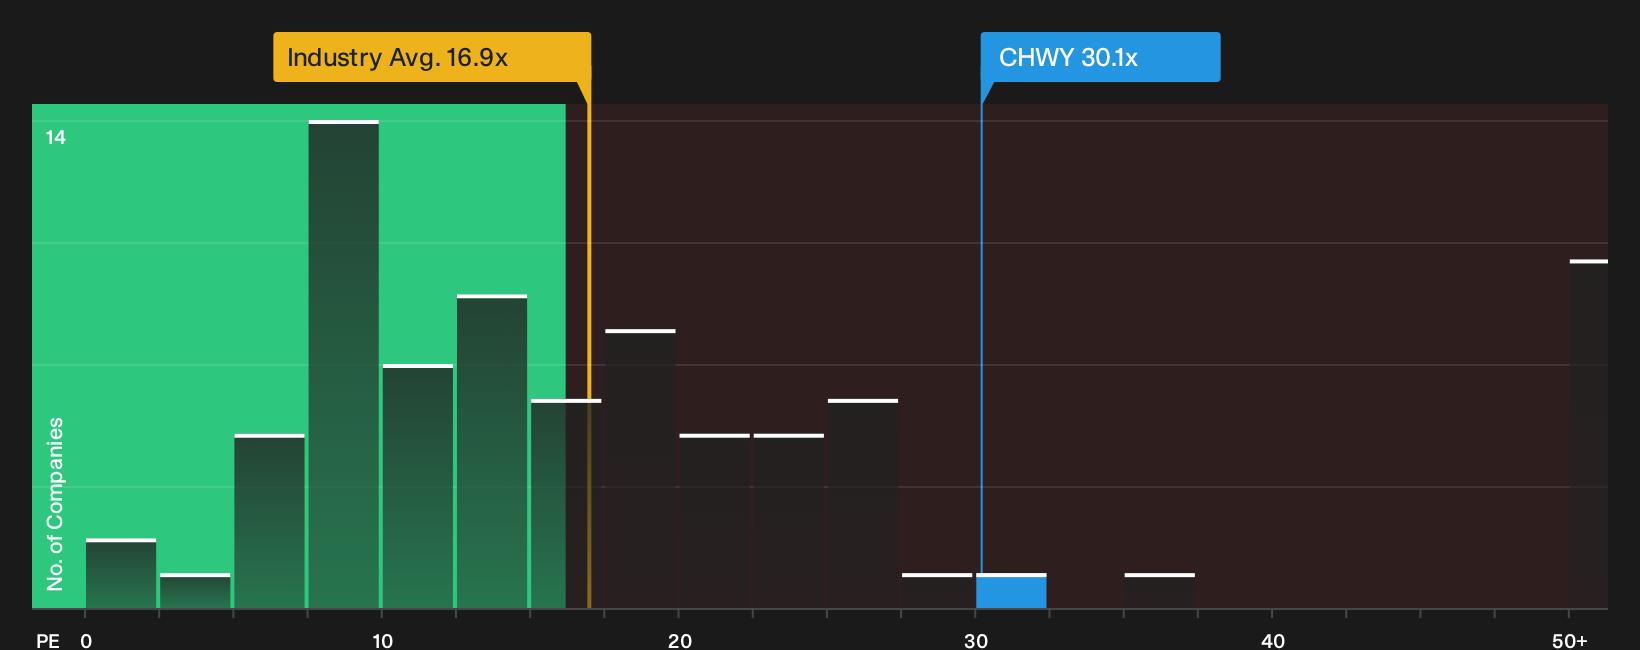
P/E suits Chewy because the market is already focused on its path from earnings to free cash flow. On this lens, the stock trades on a P/E of 31.6x, compared with a Specialty Retail average of about 16.9x and a peer group closer to 16.1x. That is a clear premium to both the sector and similar businesses.
The fair multiple implied by the valuation model is lower than where Chewy trades today, so the shares screen as overvalued on this earnings metric. For you as a holder or potential buyer, the gap asks a direct question. It implies the current price builds in stronger profitability or resilience than the typical retailer, and you would need to judge whether Chewy's earnings profile justifies that richer tag. Explore the numbers behind Chewy's P/E valuation.
The Chewy Narrative: What Would Justify Today's Price?
Chewy Narratives on Simply Wall St pick up where this valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today. Each Narrative sets out a fair value view as a clear, testable idea about how Chewy's business might develop over time, so you can track how that thesis holds up as new information arrives.
Community views on Chewy are split between those who see more upside in the recurring health and Autoship story and those who think the stock already prices most of that in.
Bull case: 25% undervalued
"The main thing that has to go right is that Chewy converts its Autoship base and Vet Care clinics into a durable, higher margin health and services ecosystem supported by automation, AI and sponsored ads..."
Discover why this Narrative puts Chewy at 25% undervalued.
Bear case: roughly fairly valued
"Although Chewy continues to gain share in a largely flat consumables market and reports mid teens hard goods growth compared with the broader category, management’s expectation that premiumization and discretionary categories remain pressured indicates mix could skew toward lower margin staples..."
Explore why this Narrative puts Chewy at roughly fairly valued.
One more Chewy angle that could matter a lot
Before stopping at the numbers, it is worth checking who is actually steering Chewy, how their pay is structured, and whether those incentives truly line up with the outcomes you care about. See who runs Chewy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com