
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DNOW (DNOW) Stock May Be A Bargain On Cash Flow
DNOW has delivered a solid multi year share price run, and recent earnings news has put fresh attention on whether that performance lines up with the cash the business can generate. With the stock around US$15.77, the question is how much of its future cash flows are already reflected in that quote.
- Over 5 years, DNOW has returned 114.6%, which puts real weight on whether that rise is matched by the cash the company is expected to produce.
- Management is investing in ERP conversions and efficiency projects that can influence future margins and the timing of cash flows, which matters directly for any cash flow based valuation.
- If you'd rather focus on sales, this one's for you. See what DNOW's 0.7x P/S says about the price.
The issue now is whether DNOW's current share price is supported by its cash flows when measured against an intrinsic value estimate using a Discounted Cash Flow (DCF) approach.
If you want to test the same cash flow question across a broader set of opportunities, compare DNOW with 34 high quality undervalued stocks next.
Is DNOW a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here takes DNOW's future free cash generation and discounts it back to today. On this view, the group is working from last twelve month free cash flow of about $139.5 million and analyst projections that lift free cash flow into the mid $200 million range over the next decade, then move into slower growth assumptions, which fits a business that is expected to mature rather than chase breakneck expansion.
Because the recent DCF projections put DNOW's estimated intrinsic value substantially above the current share price of $15.77, the model implies the market is not fully pricing in those cash streams. The Q2 2026 update, including higher EBITDA and ongoing ERP work, provides some support to the idea that management is backing that cash flow path with operational projects, even if execution risk on system rollouts still affects timing. That gap between modeled value and traded price is where long term investors tend to focus. Find out what DNOW could be worth using our Discounted Cash Flow (DCF) estimate.
The DNOW Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for DNOW pick up where the DCF puzzle leaves off by spelling out which assumptions on DNOW's growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price, and they sit on the Community page. Rather than a single valuation output, each narrative lays out the key drivers behind its fair value view so you can track those inputs against future results.
One of the top community narratives on DNOW: 16% undervalued
"The current valuation implies the market is still assigning limited credit to DNOW for its cash generation, share repurchases and progress on shifting toward gas infrastructure…"
Discover why this Narrative puts DNOW at 16% undervalued.
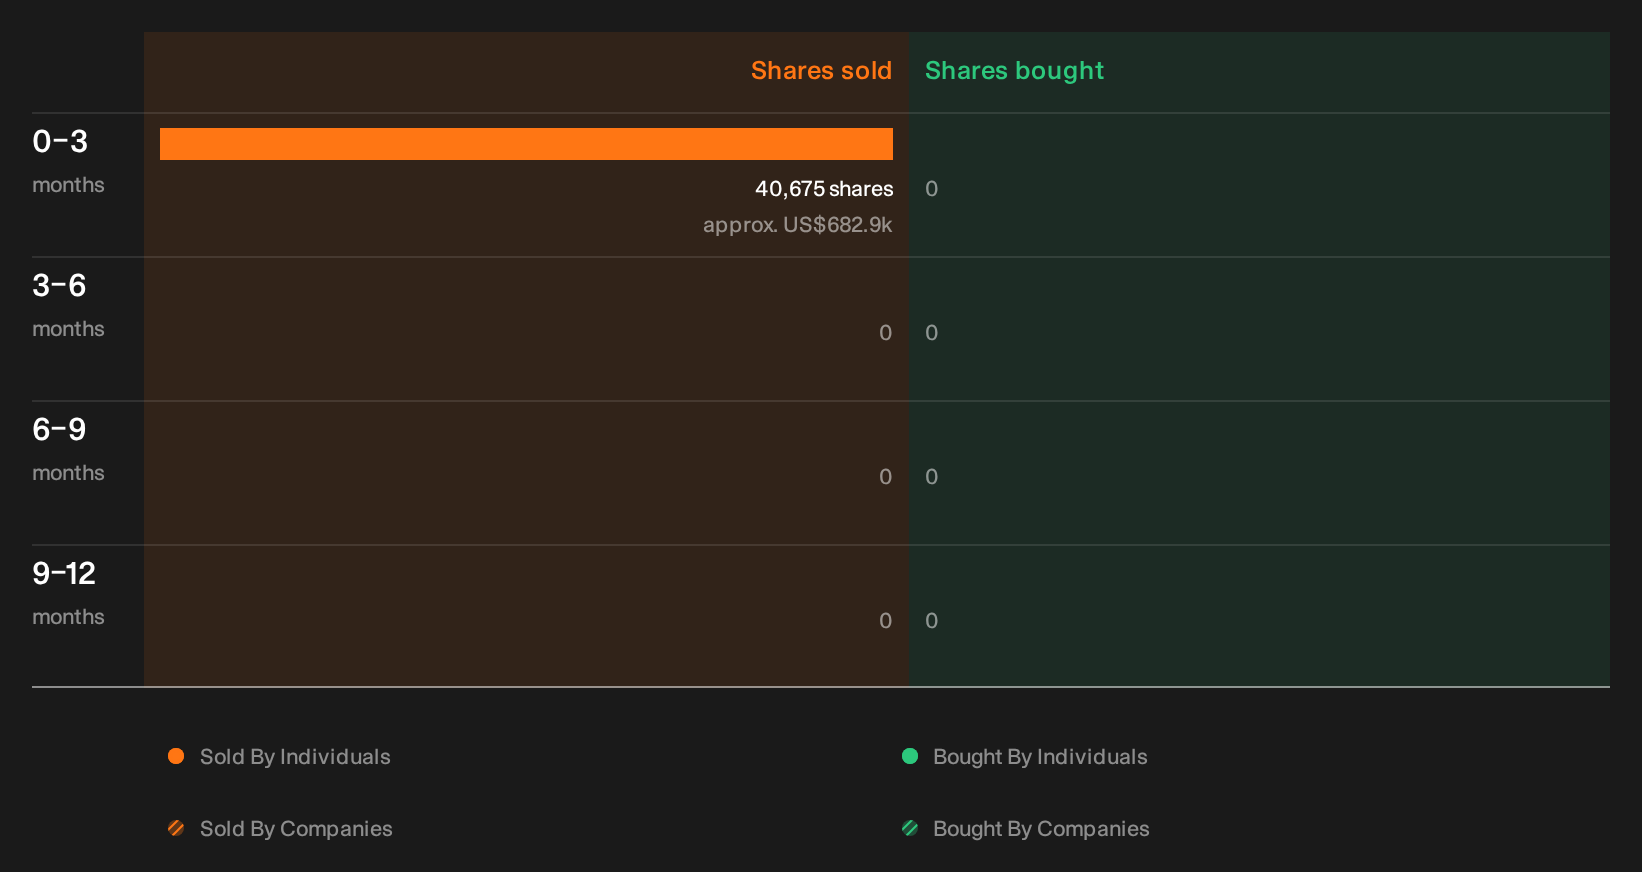
One unresolved question for DNOW: what are insiders doing?
Valuation work only goes so far if insider behavior is pulling in a different direction, and recent share disposals by DNOW executives or directors raise a fresh set of details for you to examine. See the recent insider selling flagged for DNOW.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com