
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Novartis (SWX:NOVN) Undervalued After Its Rhapsido Approval?
Novartis has delivered strong multi year gains. With fresh product news in immunology and neurology, the question for investors is whether the current share price is still in line with what its earnings support.
- Over the past 5 years the stock has returned 106.2%, which puts a lot of weight on whether the underlying earnings justify that kind of compounding.
- Recent FDA approval for Rhapsido in additional urticaria indications, together with progress in multiple sclerosis and cardiovascular assets like pacibekitug, can influence how investors think about future profit growth, margin potential and the timing of cash flows.
- The analysts covering Novartis have run their own numbers. See what analysts think Novartis's shares could be worth.
The issue now is whether the current price near recent highs is reasonable when lined up against Novartis' earnings and the Fair Ratio benchmark.
If you are considering Novartis in light of this FDA action and late-stage trial activity, it can help to compare it with companies that have a similar resilience profile using 228 resilient stocks with low risk scores.
Is Novartis Still Cheap on Earnings?
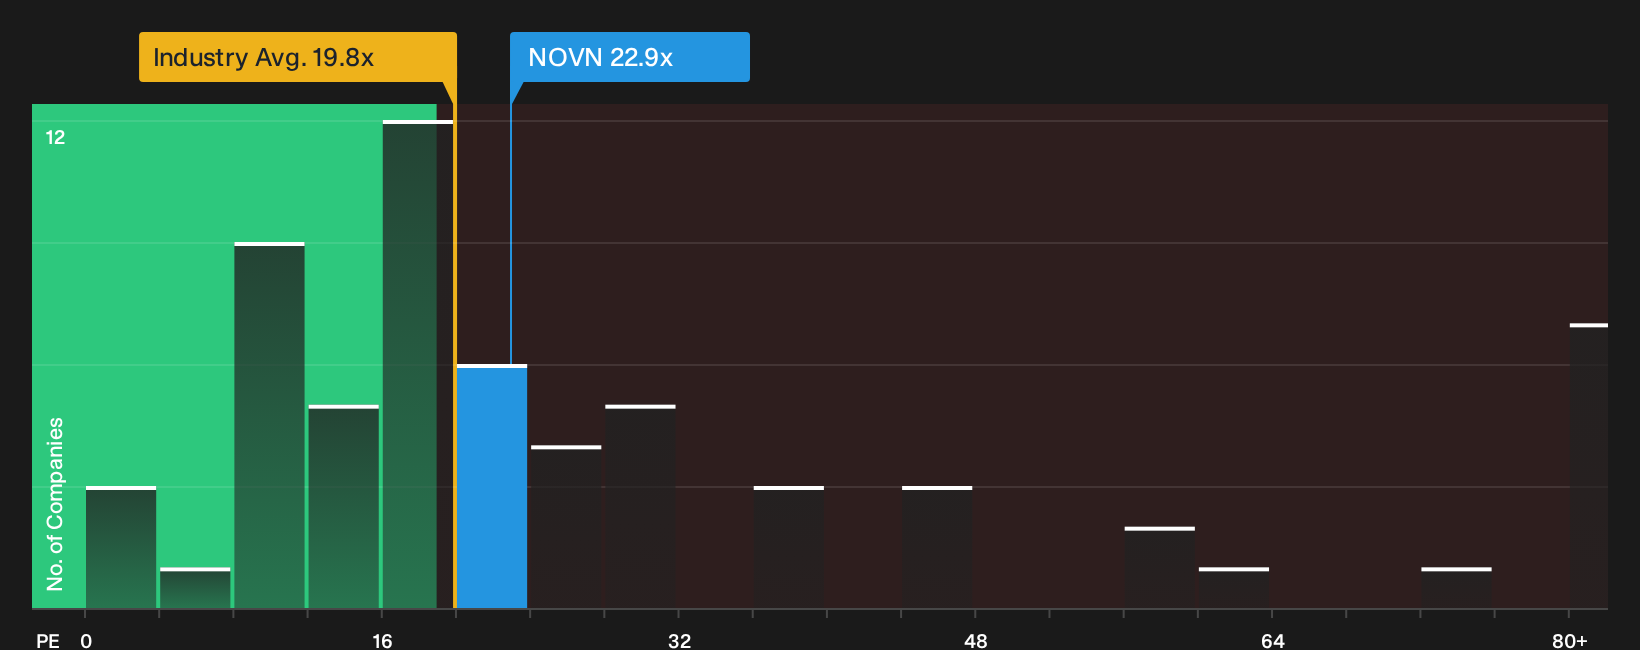
The P/E ratio fits Novartis because earnings remain the cleanest way to connect its research pipeline to what you are paying today. Novartis trades on a P/E of 22.9x, which sits slightly above the broader Pharmaceuticals sector average of 21.2x and well below the peer group at 45.5x.
Using a Fair Ratio that blends the firm’s growth profile, profitability, size and risk, the current P/E comes in below what that tailored benchmark suggests might be justified. This points to the shares screening as undervalued on this metric. Because the FDA approval of Rhapsido for additional urticaria indications and late stage work in multiple sclerosis and cardiovascular disease are already public knowledge, the fact that the valuation still trails this Fair Ratio implies the recent news has not fully closed that gap. Explore the numbers behind Novartis's P/E valuation.
The Novartis Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Novartis' P/E puzzle leaves off. They spell out, in plain terms, what trajectory for Novartis' revenue, margins and earnings would need to hold for the stock to be worth materially more or materially less than today's price, and they live on Simply Wall St's Community page. Instead of stopping at a single ratio or model output, Narratives unpack the future that number rests on so you can watch how reality compares over time.
Community views on Novartis are split between those who see additional potential in the pipeline and those who think expectations already appear well reflected.
Bull case: 15% undervalued
"Remibrutinib and ianalumab sit in a broad late stage pipeline with seven pivotal readouts expected in 2026 across cardiovascular risk reduction, immunology and neuroscience..."
Discover why this Narrative puts Novartis at 15% undervalued.
Bear case: roughly fairly valued
"Loss of exclusivity (LOE) and entry of generics for key blockbuster drugs like Entresto present a significant long-term revenue risk..."
Explore why this Narrative puts Novartis at roughly fairly valued.
The open question for Novartis, what are professionals assuming a few years down the line?
Earnings multiples only tell you what investors pay today. The next layer is how sector analysts map out Novartis’ revenue and profit profile several years ahead and how that compares with this pricing. Explore where analysts expect Novartis to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com