
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
IonQ (IONQ) Stock Looks Fairly Valued With Balance Sheet Changes Ahead
IonQ shares have pulled back sharply over the past year after a very strong five year run, which puts fresh attention on whether the current US$31.26 price still lines up with the company’s book value. With quantum computing projects, equity raises and an all stock cybersecurity acquisition all in play, the balance sheet is carrying more of the story than usual.
- Over the last 5 years the stock has returned about 197%, so a lot of the discussion now is about how much balance sheet support that long term gain really has.
- The planned US$2.0b equity offering and the up to US$1.3b all stock deal for Elisity both point to a capital heavy expansion path that can affect how investors relate IonQ’s share price to its net assets per share.
- The analysts covering IonQ have run their own numbers. See what analysts think IonQ's shares could be worth.
The issue now is whether that recent market value can be sensibly anchored to IonQ’s book value once you factor in these funding moves and expansion plans.
If you want a wider lens on quantum and AI hardware while you think through IonQ’s book value question, a focused stock screen built around 55 AI infrastructure stocks can be useful.
Is IonQ Fairly Priced on Book Value?
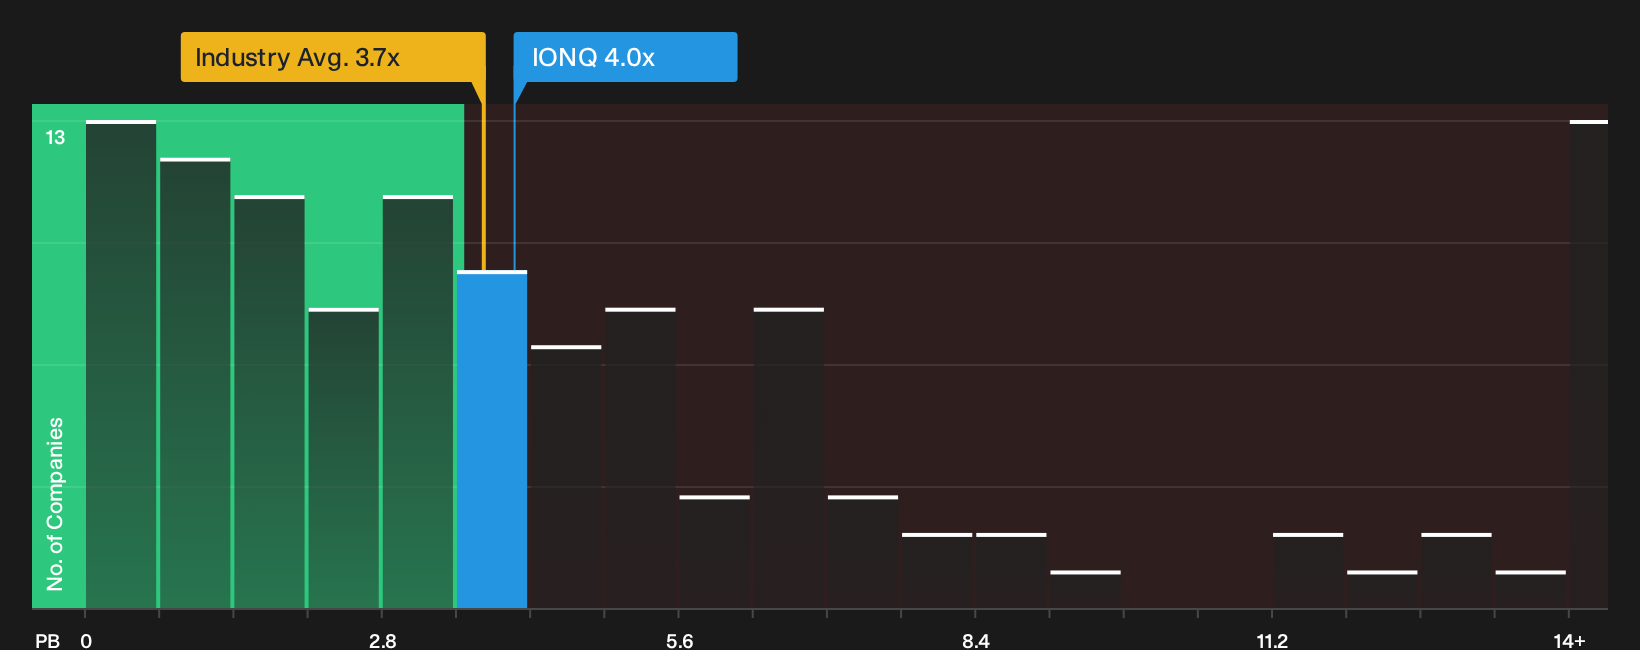
P/B is a clean yardstick for IonQ because investors are mostly paying for its balance sheet strength and accumulated R&D rather than current profits. On this measure, the stock trades on a P/B of about 4.0x, compared with a semiconductor industry average near 3.7x. That is a small premium to the sector, and far below the roughly 11.3x peer group level supplied for quantum focused comparisons.
Because the P/B gap to the broader industry is modest, the current multiple broadly lines up with what the sector as a whole is pricing in. The planned US$2.0b equity raise and the all stock Elisity deal mean book value is likely to change meaningfully over time, so the P/B ratio investors see today is tied closely to those capital decisions as much as to existing assets. Despite the stock reaction to the funding and acquisition headlines, the P/B still leaves IonQ valued roughly in line with semiconductor peers rather than at an extreme premium or discount. Explore the numbers behind IonQ's P/B valuation.
The IonQ Narrative: What Would Justify Today's Price?
IonQ's valuation story does not stop at the current P/B ratio. Simply Wall St Narratives on the Community page spell out which combinations of growth, profitability and earnings outcomes would need to materialise for the share price to sit meaningfully above or below today's level. Each scenario ties its numbers to a specific view on future growth, margins and risk, giving you a reference point you can revisit as fresh information comes through.
Community views on IonQ split sharply between a monopoly-in-the-making story and a valuation that already bakes in a best case future.
Bull case: 63% undervalued
"IonQ has systematically de-risked its thesis, and is now fully funded to execute a "winner-take-all" land grab, positioning it as the potential "Nvidia of Quantum"…"
Discover why this Narrative puts IonQ at 63% undervalued.
Bear case: 518% overvalued
"At current prices, IonQ trades at well over 100 times revenue, a level rarely sustained even among the fastest growing technology companies…"
Explore why this Narrative puts IonQ at 518% overvalued.
IonQ’s valuation still rests on one unanswered issue
Price tags and peer comparisons tell only part of IonQ’s story, because recent checks have also raised specific concerns that could matter just as much to long term holders. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com