
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Carpenter Technology (CRS) Stock May Be 19% Undervalued On Cash Flow
Carpenter Technology has seen a powerful long term share price rise, and after such a strong run the real question is whether the current valuation lines up with the cash the business can generate. With the stock no longer flying under the radar, investors are increasingly asking how much of its cash flow story is already reflected in the price.
- Over the past 5 years the share price has delivered a very large gain, which puts extra pressure on the underlying cash flows to support where Carpenter Technology trades today.
- The business depends heavily on turning specialized metal products into dependable free cash flow, so the durability of its margins and reinvestment needs may shape how much value those future streams truly carry.
- What if you looked at Carpenter Technology through its earnings instead? See why Carpenter Technology's 34.9x P/E tells a different valuation story.
The issue now is whether the current US$372.53 share price is justified by Carpenter Technology's cash flows when viewed through a Discounted Cash Flow (DCF) lens.
If you want a reality check on Carpenter Technology's cash flow driven story, it can help to line it up against a wider group of companies pulled from our 34 high quality undervalued stocks.
Is Carpenter Technology a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) approach here looks at the cash Carpenter Technology can return to shareholders over time and then adjusts that stream back to today. On the latest numbers, the group produced about $429 million in free cash flow over the last twelve months, and the model assumes that this cash generation continues to grow rather than shrink.
Analysts feeding into the DCF framework expect Carpenter Technology's yearly free cash flow to build from that base, reaching higher levels by the late 2020s before growth rates ease back in the 2030s. Those projections, when discounted, result in an estimated intrinsic worth that the model suggests is meaningfully above the current $372.53 share price. This implies the market is pricing the future cash stream more cautiously than the DCF does. Find out what Carpenter Technology could be worth using our Discounted Cash Flow (DCF) estimate.
The Carpenter Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Carpenter Technology DCF puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to look materially higher or lower than today’s price on the Community page. Rather than focusing on a single valuation output, each Narrative sets out the specific assumptions behind its view of fair value so you can refer back to those expectations as fresh results come through.
One of the top community narratives on Carpenter Technology: 31% undervalued
"The main thing that has to go right is that Carpenter Technology continues to convert its record SAO operating margins and brownfield capacity expansion into sustained high free cash flow…"
Discover why this Narrative puts Carpenter Technology at 31% undervalued.
One more Carpenter Technology check that belongs beside the cash flow story
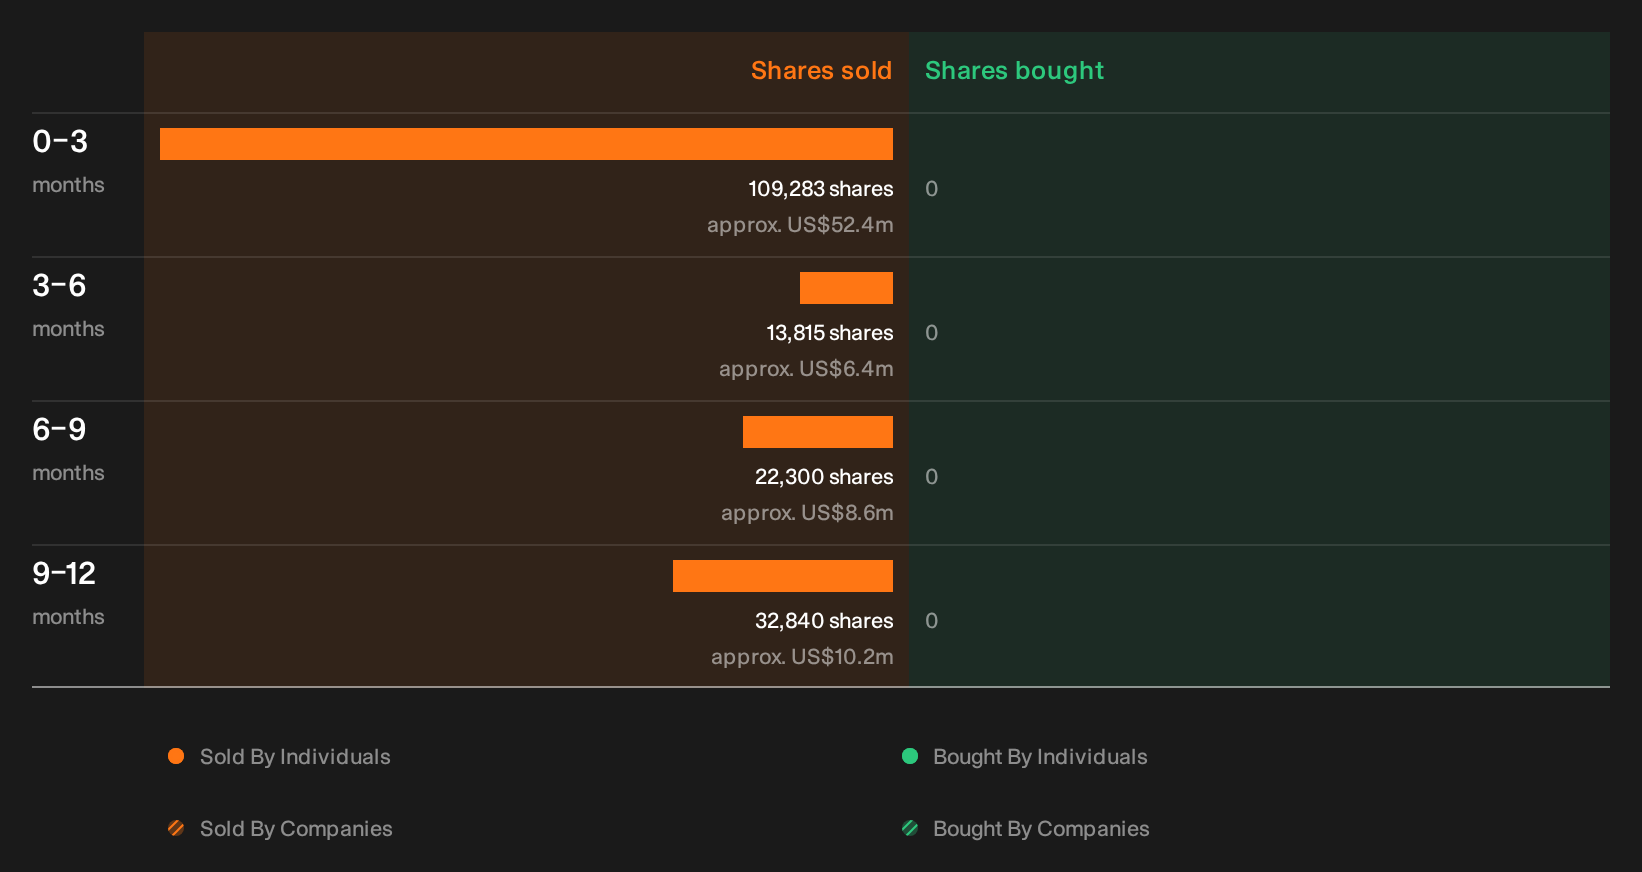
Price and cash generation are only part of the picture, because recent moves by people inside Carpenter Technology can quietly signal how those closest to the business are acting. See the recent insider selling flagged for Carpenter Technology.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com