
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Chubb (NYSE:CB) Reports Q3 2026 Earnings
Global insurance provider Chubb Limited (NYSE:CB) fell short of the market’s revenue expectations in Q3 2026, with sales flat year on year at $16.2 billion. Its non-GAAP profit of $7.66 per share was 12.7% above analysts’ consensus estimates.
Is now the time to buy Chubb? Find out by accessing our full research report, it’s free.
Chubb (CB) Q3 2026 Highlights:
- Net Premiums Earned: $14.92 billion vs analyst estimates of $14.99 billion (3.9% year-on-year growth, in line)
- Revenue: $16.2 billion vs analyst estimates of $16.94 billion (flat year on year, 4.4% miss)
- Combined Ratio: 84.1% vs analyst estimates of 87.4% (334.4 basis point beat)
- Adjusted EPS: $7.66 vs analyst estimates of $6.80 (12.7% beat)
- Book Value per Share: $191.43 vs analyst estimates of $216.12 (5.1% year-on-year growth, 11.4% miss)
- Market Capitalization: $138 billion
Company Overview
Dating back to when a Civil War veteran created a frost-proof water meter, Chubb Limited (NYSE:CB) provides commercial and personal property and casualty insurance, reinsurance, and life insurance products to a diverse client base across 54 countries.
Revenue Growth
Big picture, insurers generate revenue from three key sources. The first is the core business of underwriting policies. The second source is income from investing the “float” (premiums collected upfront not yet paid out as claims) in assets such as fixed-income assets and equities. The third is fees from various sources such as policy administration, annuities, or other value-added services. Thankfully, Chubb’s 9.8% annualized revenue growth over the last five years was solid. Its growth beat the average insurance company and shows its offerings resonate with customers.
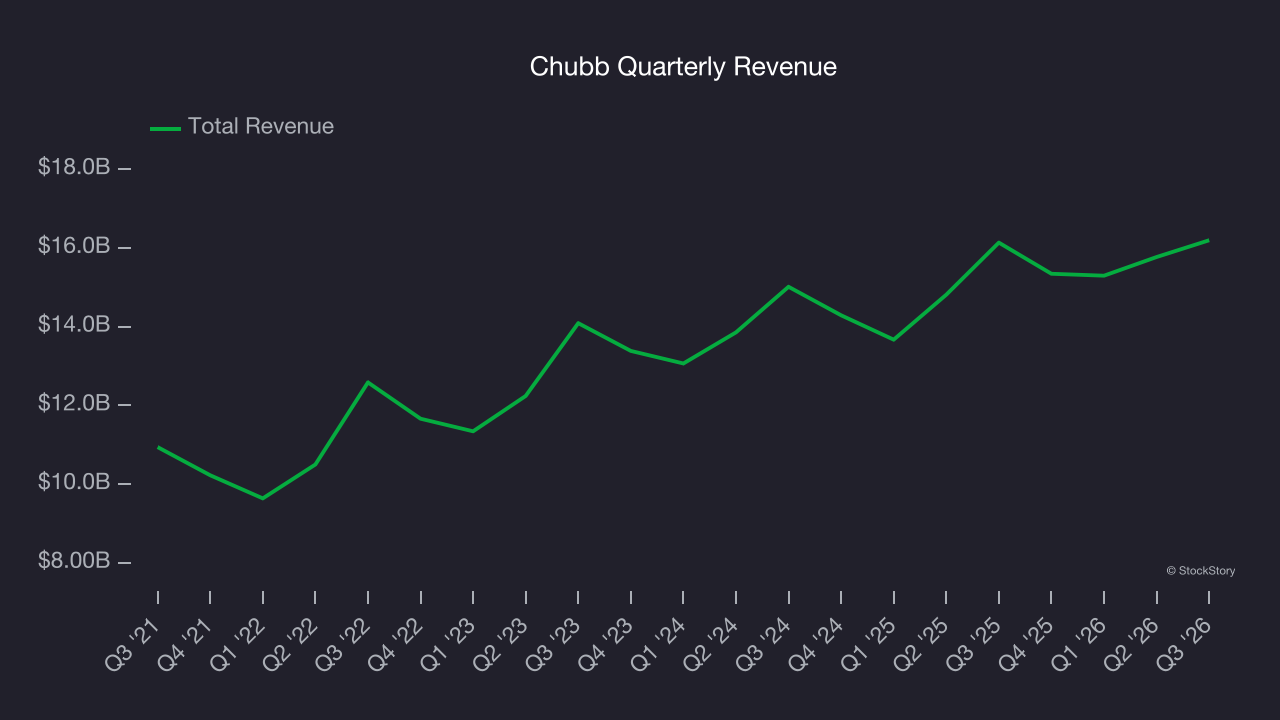
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Chubb’s recent performance shows its demand has slowed as its annualized revenue growth of 6.4% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 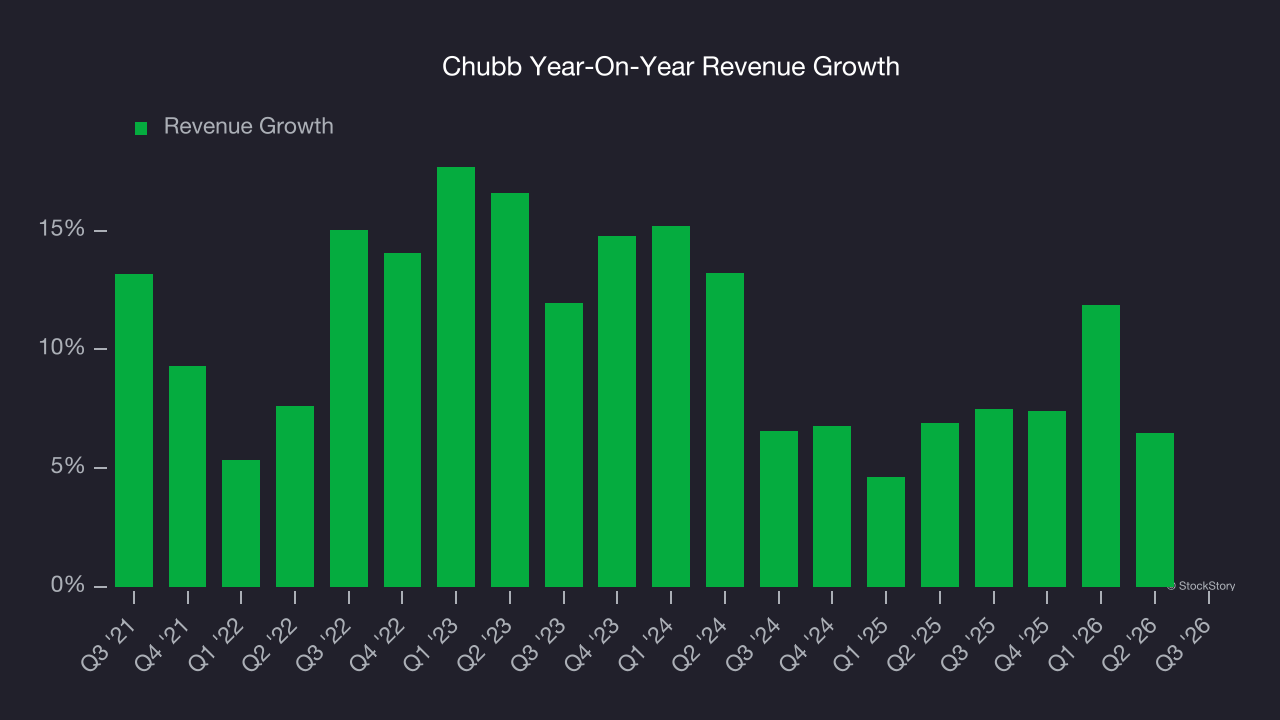 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Chubb’s $16.2 billion of revenue was flat year on year, falling short of Wall Street’s estimates.
Net premiums earned made up 89.4% of the company’s total revenue during the last five years, meaning Chubb barely relies on non-insurance activities to drive its overall growth.
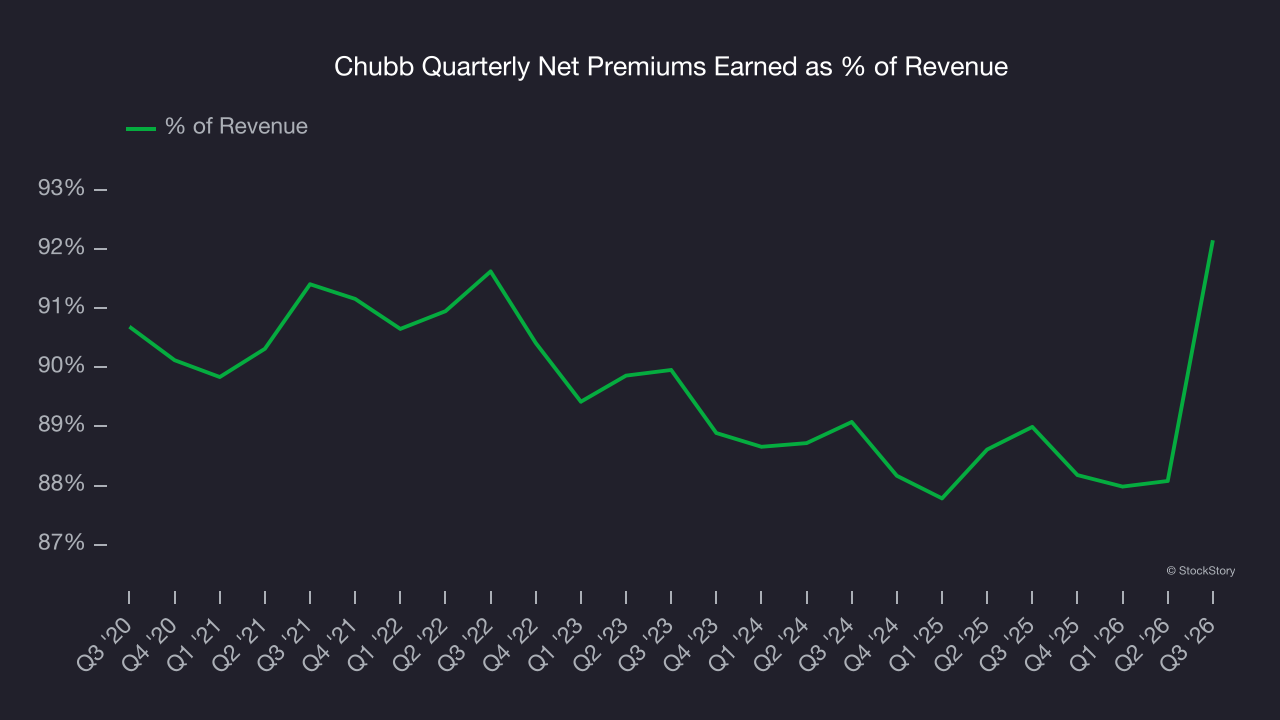
Markets consistently prioritize net premiums earned growth over investment and fee income, recognizing its superior quality as a core indicator of the company’s underwriting success and market penetration.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Book Value Per Share (BVPS)
Insurers are balance sheet businesses, collecting premiums upfront and paying out claims over time. Premiums collected but not yet paid out, often referred to as the float, are invested and create an asset base supported by a liability structure. Book value per share (BVPS) captures this dynamic by measuring these assets (investment portfolio, cash, reinsurance recoverables) less liabilities (claim reserves, debt, future policy benefits). BVPS is essentially the residual value for shareholders.
We therefore consider BVPS very important to track for insurers and a metric that sheds light on business quality. While other (and more commonly known) per-share metrics like EPS can sometimes be lumpy due to reserve releases or one-time items and can be managed or skewed while still following accounting rules, BVPS reflects long-term capital growth and is harder to manipulate.
Chubb’s BVPS grew at a mediocre 6.8% annual clip over the last five years. However, BVPS growth has accelerated recently, growing by 8.3% annually over the last two years from $163.16 to $191.43 per share.
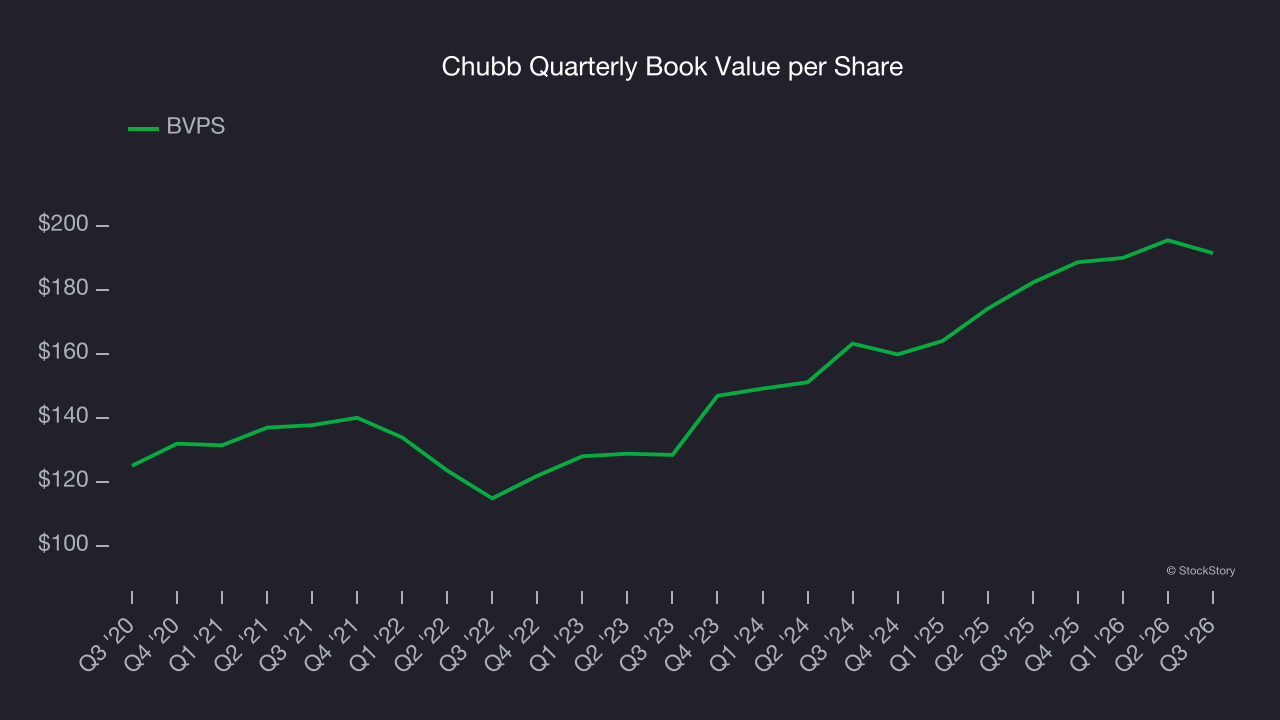
Over the next 12 months, Consensus estimates call for Chubb’s BVPS to grow by 25.5% to $216.12, elite growth rate.
Key Takeaways from Chubb’s Q3 Results
It was good to see Chubb beat analysts’ EPS expectations this quarter. On the other hand, its revenue missed and its book value per share fell short of Wall Street’s estimates. Overall, this was a softer quarter. The stock remained flat at $355.75 immediately following the results.
Chubb didn’t show its best hand this quarter, but does that create an opportunity to buy the stock right now? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).