
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lucid (LCID) Stock Still Looks Above Fair Value On A 99% Slump
Lucid Group has seen its share price fall sharply in recent years, which puts a spotlight on whether the current valuation is still supported by its sales base. With fresh expansion plans in Europe on the table, the key issue for you is how much of the revenue story is already baked into the stock.
- Over the past 5 years, Lucid Group shares have declined 98.8%, which raises hard questions about how much of the original sales ambition the market is still pricing in.
- The plan to open French retail and service locations from 2027, using Emil Frey France's network, may support expectations for higher future sales and influence how investors frame the timing of any potential scale up in revenue.
- Your read on Lucid Group is one view; the desks covering it have another. See what analysts think Lucid Group's shares could be worth.
The stock's next move may depend on whether Lucid Group's current share price is appropriately anchored to the sales it generates today and what investors reasonably expect it to produce in the future.
If you want a broader starting point alongside Lucid Group, a focused screen of 34 high quality undervalued stocks can help you compare how other businesses are currently priced against their fundamentals.
Is Lucid Group Getting Expensive on Sales?
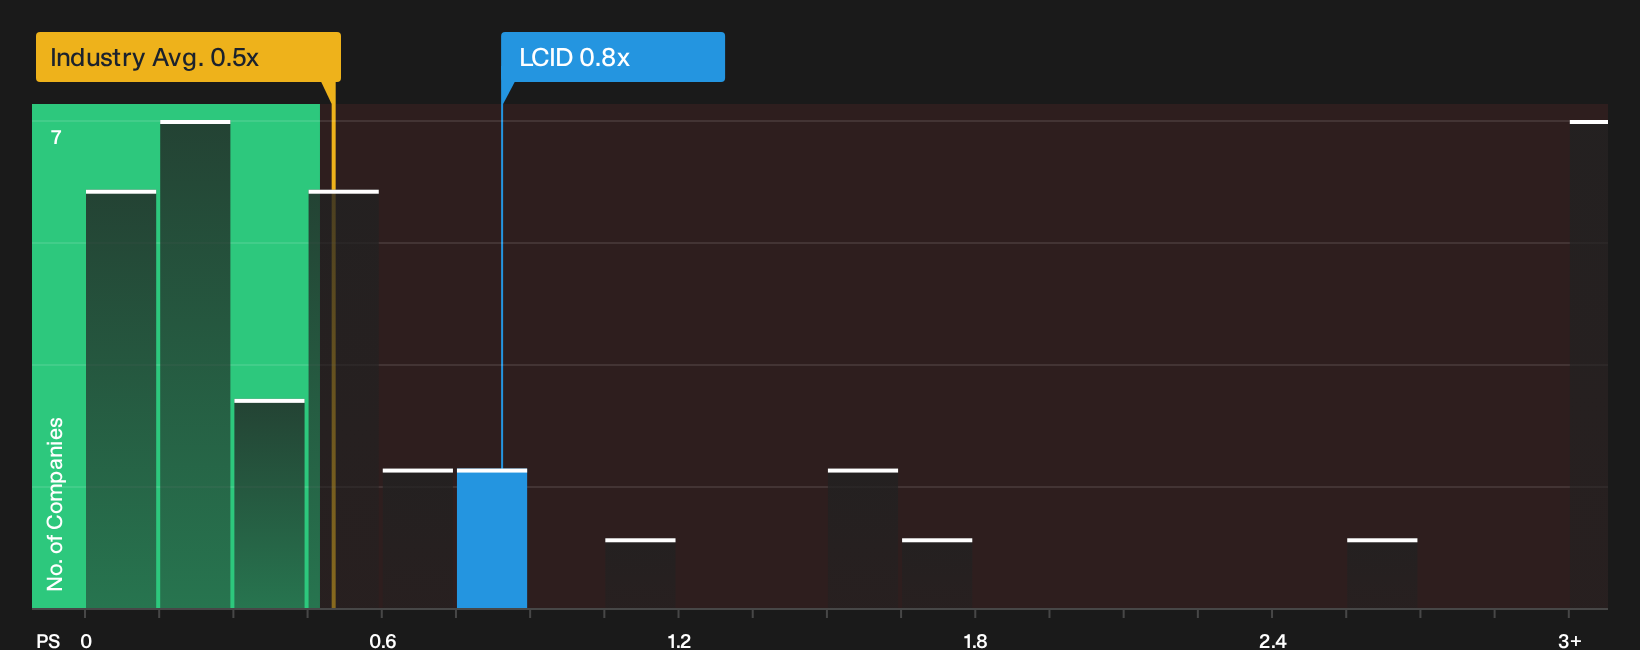
P/S works better for Lucid Group than P/E right now because revenue gives you at least a concrete base to compare against. On this measure, the shares trade on a P/S of 0.8x, which is higher than the Auto sector average of 0.5x and above the 0.3x peer group level. That tells you the market is assigning a richer value to each dollar of Lucid Group’s sales than to many other vehicle makers.
The model suggests a much lower P/S would be more in line with what you might expect given Lucid Group’s current scale, profitability profile and risk, and it penalises the business heavily enough that the gap looks extreme rather than precise. Despite the French expansion plan and partnership with Emil Frey setting up a bigger potential sales footprint, the current multiple still indicates the stock screens as overvalued on this framework. Explore the numbers behind Lucid Group's P/S valuation.
The Lucid Group Narrative: What Would Justify Today's Price?
Lucid Group's current P/S gap raises a simple question. What kind of growth path and margin profile would need to show up in the actual numbers for today's price to look either conservative or stretched when those results arrive? Narratives on Simply Wall St's Community page set out those building blocks clearly, with each one spelling out the assumptions behind its view of fair value so you can compare that framework with Lucid Group's reported performance over time.
One of the top community narratives on Lucid Group: 57% undervalued
"Advancements in powertrain and battery technology, such as the in-house Atlas Drive Unit and extended-range battery packs, position Lucid as a technology leader..."
Discover why this Narrative puts Lucid Group at 57% undervalued.
Lucid Group’s valuation still leaves one crucial issue unresolved
Price tags only tell part of Lucid Group's story, because our broader checks have highlighted specific concerns that investors may want to weigh carefully before drawing any firm view. Take a closer look at 4 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com