
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Investors Got Wrong About Take Two Before The Fall
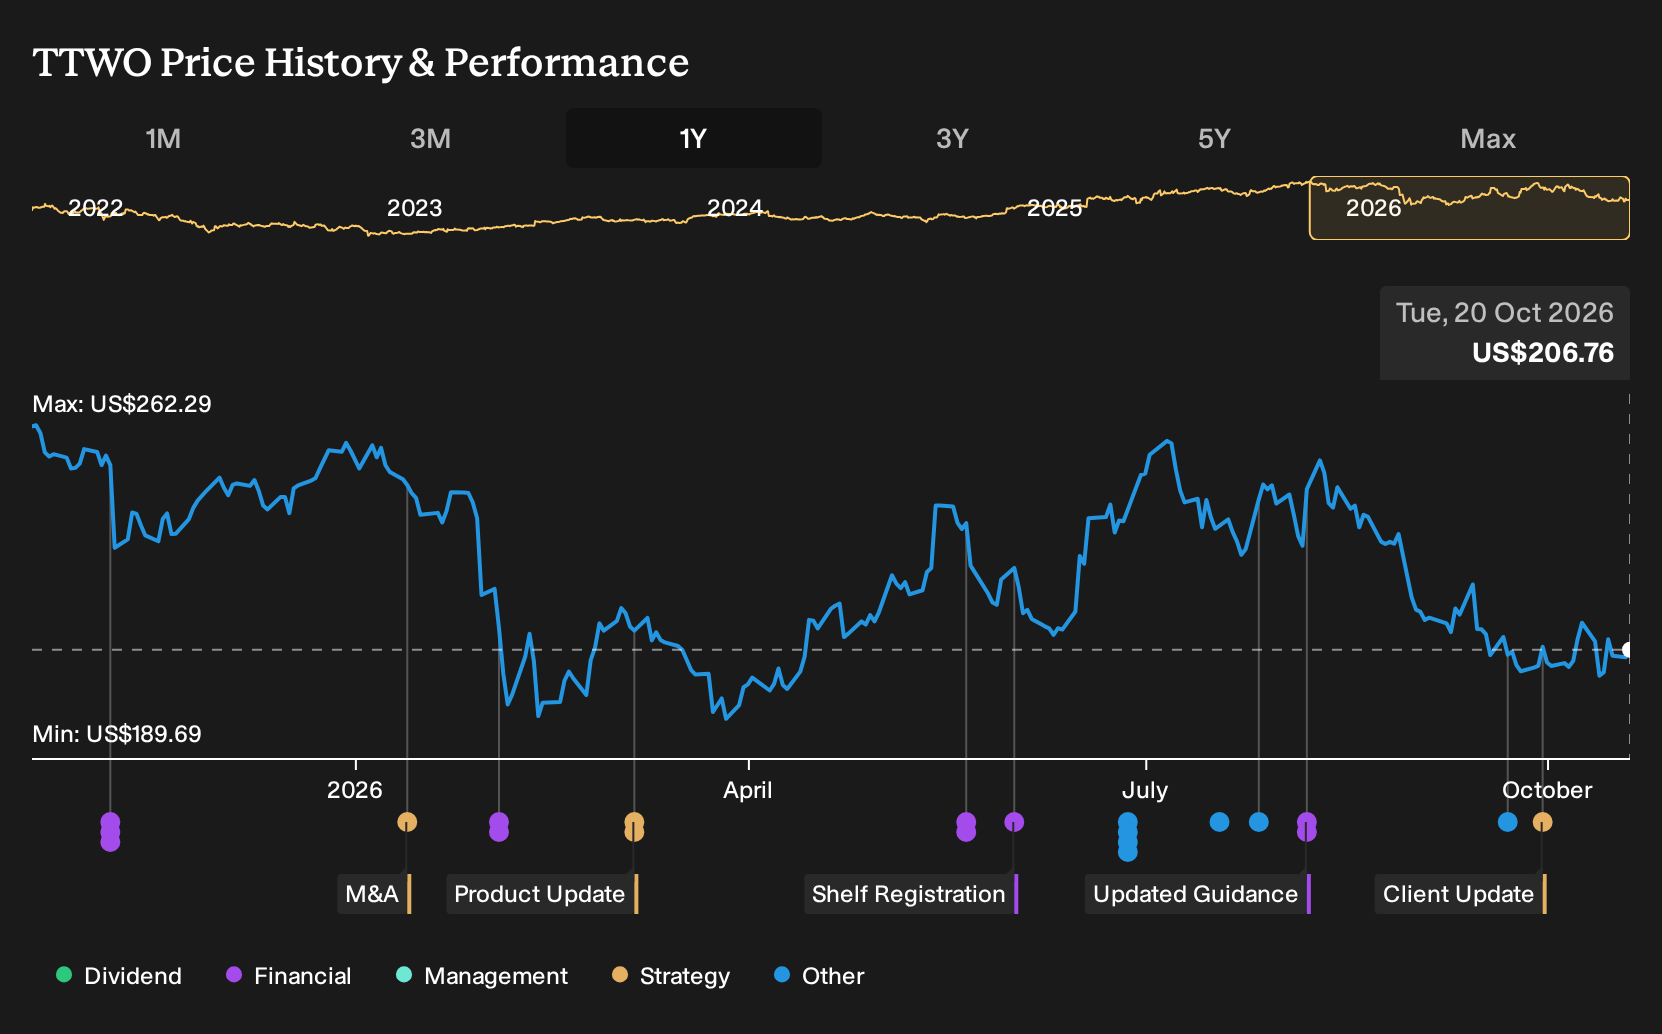
If you had paused in late 2025, looked at the excitement around Grand Theft Auto VI and the bullish analyst targets on Take-Two Interactive Software, and decided to stay on the sidelines, the past year might feel like a bullet dodged. Investors who held Take-Two Interactive Software over the past year are down 20.6%, including dividends. The real question is which expectations about bookings, margins and execution were already on record that you could have tested before that drop.
The easy part of this move is behind Take-Two Interactive Software. Zero in on 34 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Take-Two Interactive Software
The shares cost US$262 at the start of the period, so any view on Take-Two Interactive Software depended on which story about its future you found more convincing.
On the bullish side, analysts saw a Fair Value of US$278, effectively the price those optimistic assumptions pointed to, based on hits from Grand Theft Auto VI and other releases driving record net bookings and higher margins over time.
The bearish narrative pinned Fair Value at US$145, with the key worry that weak Zynga mobile trends and heavy marketing and development spending would keep net margins under pressure.
What The Results Changed For The Take-Two Interactive Software Debate
Grand Theft Auto VI moved from promise to scheduled product, with Take-Two Interactive Software confirming a 19 November 2026 launch and reporting Q1 2027 revenue of US$1,533.9 million. That backed the bullish focus on bookings and demand. The same quarter showed a deeper loss of US$34.1 million and a net margin that fell from -0.8% to -2.2%, which kept the profitability piece of the optimistic case unproven. Overall, the evidence cut both ways.
The episode turned on whether strong content can offset pressured earnings. For other stocks built around a big release, it may help to track two lines separately: compare guidance and reported bookings to the original growth story, and then match net margin moves to any statements about eventual profitability.
What You Would Be Paying For In Take-Two Interactive Software Today
With Take-Two Interactive Software now trading at US$207, the drop of 20.6% over the past year puts more weight on what buyers think the next phase of Grand Theft Auto VI and mobile bookings can deliver.
The Narrative’s Fair Value sits above the current price and leans on GTA VI demand plus a broad mobile and console slate. For the fall to look like an opportunity rather than a warning, a buyer today would need confidence that GTA VI can support durable bookings across consoles and online over several years.
"An important source of revenue for Take-Two continues to be from Grand Theft Auto 5. It''s been 13 long years since Grand Theft Auto V arrived on the scene. Thirteen years! It became the best-selling entertainment title of the entire decade. Even today it is still generating meaningful revenue for Take-Two Interactive."
The price and this Narrative do not agree. → Uncover what this Narrative says Take-Two Interactive Software is actually worth
Looking Past Take-Two’s Big Release
Take-Two Interactive pulls you in with blockbuster titles and headline launches. Nearby, another business quietly feeds a different everyday habit.
Where Take-Two trades in games, this other player trades in attention. It turns search boxes and video feeds into crowded digital storefronts.
Behind the scenes, its cloud tools support customers running heavier AI workloads. That helps teams analyse data, test ideas and refine products faster.
As more activity shifts online, that blend of ads, video and AI services could shape your watchlist as much as any single franchise hit.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 27% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com