
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Exploring Delijia Transmission Technology (Jiangsu)Ltd And 2 Other Undiscovered Gems In Asia
As global markets grapple with inflation pressures and shifting investor sentiment, Asia presents a dynamic landscape where small-cap stocks are gaining attention amidst broader market rotations. In this environment, identifying promising companies like Delijia Transmission Technology (Jiangsu) Ltd can offer insights into potential opportunities within the region's evolving economic framework.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Apex Mining | 22.02% | 24.39% | 37.14% | ★★★★★★ |
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Silvery Dragon Group Tianjin | 25.01% | 2.55% | 25.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
Delijia Transmission Technology (Jiangsu)Ltd (SHSE:603092)
Simply Wall St Value Rating: ★★★★★☆
Overview: Delijia Transmission Technology (Jiangsu) Ltd focuses on the development and manufacturing of automotive transmission systems, with a market cap of CN¥15.36 billion.
Operations: Delijia Transmission Technology (Jiangsu) Ltd generates revenue primarily from the development and manufacturing of automotive transmission systems. The company has a market cap of CN¥15.36 billion.
Delijia Transmission Technology, a vibrant player in the transmission sector, has shown promising growth with earnings increasing by 22% over the past year, outpacing the electrical industry’s modest 0.2%. Trading at nearly half its estimated fair value, it offers an attractive proposition for investors seeking undervalued opportunities. The company reported H1 2026 sales of CNY 2.56 billion and revenue of CNY 2.60 billion, reflecting steady growth from last year's figures of CNY 2.47 billion and CNY 2.48 billion respectively. Despite a slight dip in basic earnings per share to CNY 1.03 from CNY 1.09, Delijia remains financially robust with more cash than total debt and positive free cash flow standing at approximately US$135 million as of June this year.

Hengyi Petrochemical (SZSE:000703)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Hengyi Petrochemical Co., Ltd. is engaged in the production and sale of chemical fiber products both domestically and internationally, with a market capitalization of approximately CN¥46.99 billion.
Operations: Hengyi Petrochemical generates revenue primarily from its Chemical Fiber Industry segment, contributing CN¥66.55 billion, followed by the Petrochemical Industry at CN¥53.79 billion and Supply Chain Services at CN¥4.54 billion.
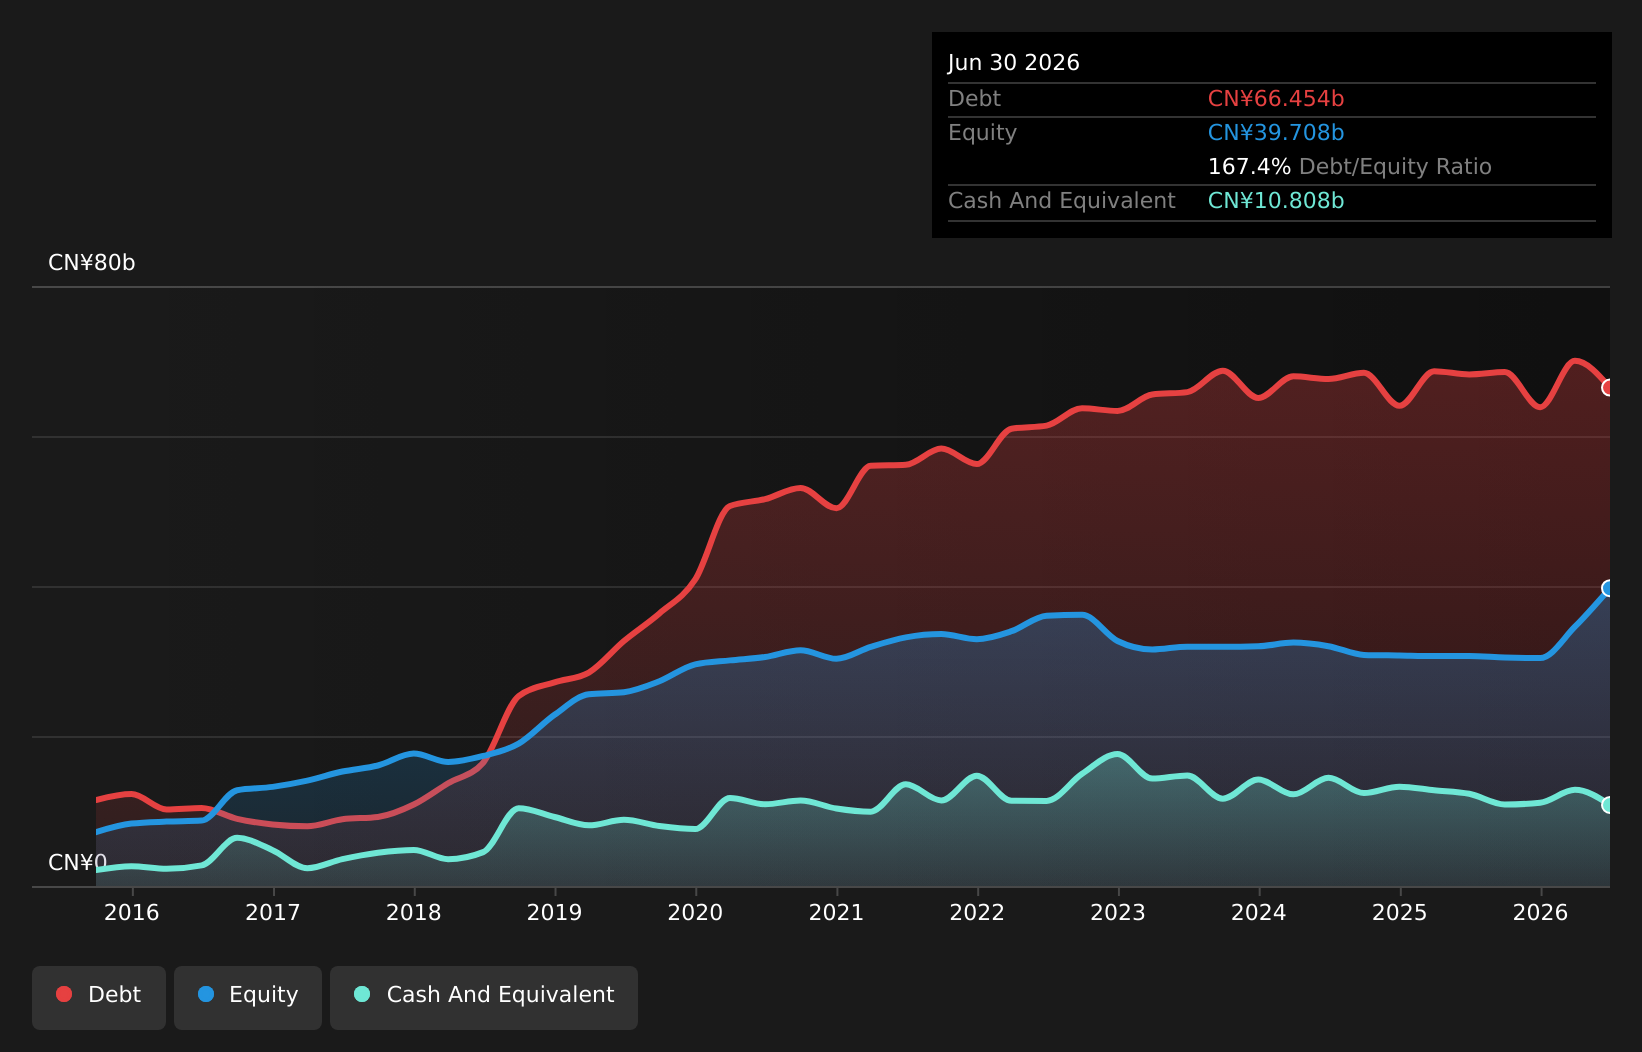
Hengyi Petrochemical, a notable player in the chemicals sector, has demonstrated impressive growth with earnings skyrocketing by 19,322% over the past year. Despite this surge, its net debt to equity ratio stands at a high 140.1%, indicating significant leverage. However, interest payments are well-covered by EBIT at six times coverage. The company is trading at an attractive value, being 52.6% below estimated fair value compared to industry peers. Recent amendments to its articles of association and a declared cash dividend of CNY 9 per ten shares highlight ongoing strategic initiatives and shareholder returns.
- Get an in-depth perspective on Hengyi Petrochemical's performance by reading our health report here.
Marketech International (TWSE:6196)
Simply Wall St Value Rating: ★★★★★★
Overview: Marketech International Corp. operates in the manufacturing, sales, importation, and trading of integrated circuits, semiconductors, electrical and computer equipment and materials across Taiwan, China, the United States, and other international markets with a market cap of NT$130.66 billion.
Operations: Marketech International generates revenue primarily through its Factory System and Electromechanical System Service Business Segment, contributing NT$41.70 billion, followed by the Equipment Materials Agent Sales Business Segment at NT$12.39 billion. The Customized Equipment Manufacturing Segment adds NT$10.19 billion to the company's revenue streams.
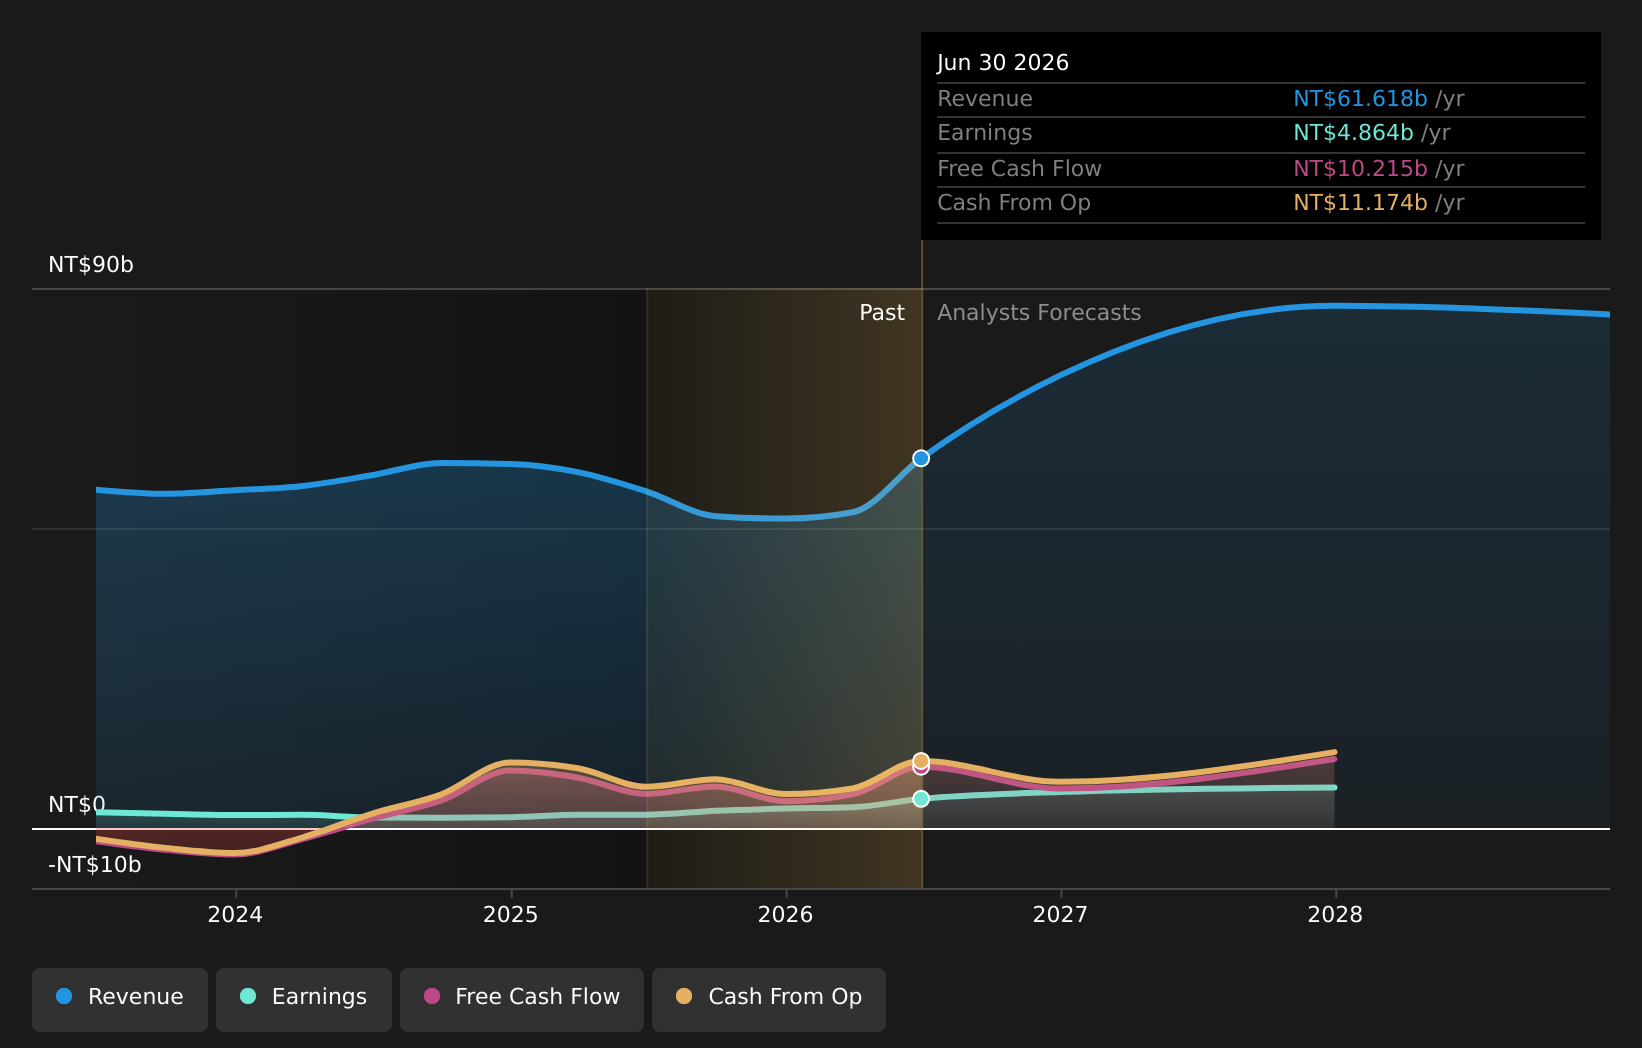
Marketech International, a dynamic player in the semiconductor industry, showcased impressive growth with earnings surging by 118.4% over the past year, outpacing the industry's 43.9%. Trading at 21.5% below its estimated fair value suggests potential upside for investors seeking undervalued opportunities. The company's debt-to-equity ratio has significantly improved from 57% to 18.2% over five years, reflecting prudent financial management. Recent earnings reports highlight robust performance with second-quarter sales reaching NT$21 billion and net income jumping to NT$1.8 billion from NT$396 million a year ago, indicating strong operational execution and profitability enhancements.
Next Steps
- Take a closer look at our Asian Undiscovered Gems With Strong Fundamentals list of 131 companies by clicking here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com