
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Mitie Group (LSE:MTO) Stock Looks Fully Priced On Current Earnings
Mitie Group has delivered a strong run in recent years, which puts a spotlight on a simple question for anyone looking at the shares today: Is the current price being asked in the market supported by the earnings power of the business?
- Mitie Group has returned 270.1% over the past 5 years, so a lot now depends on whether that gain lines up with what its profits can reasonably sustain.
- The group relies on converting long term service contracts into consistent earnings, which can influence how confidently investors treat its current profit base when they weigh the share price.
- The analysts covering Mitie Group have run their own numbers. See what analysts think Mitie Group's shares could be worth.
The stock's next move may depend on whether Mitie Group's current earnings profile is strong enough to justify where the shares trade now.
If you want a reference point for whether Mitie Group's earnings based story feels compelling, it can help to compare it with other companies in the 7 high quality undervalued stocks
Is Mitie Group Getting Expensive on Earnings?
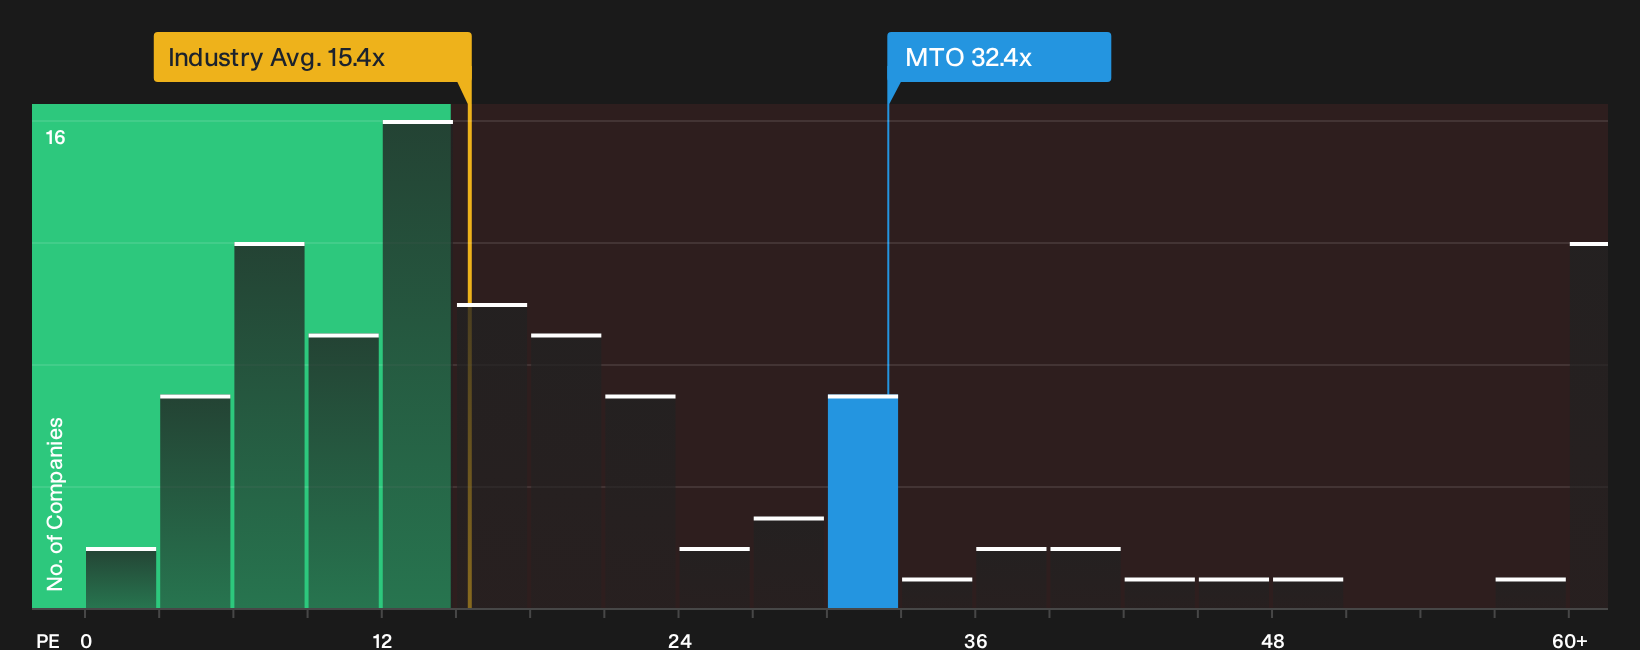
The P/E ratio fits Mitie Group because earnings remain a key yardstick for service based operators that rely on long term contracts. On this measure, the shares trade on roughly 32.4x earnings, which is well above both the Commercial Services sector average of about 15.3x and the peer group on roughly 19.6x. That places the stock on a clear premium tag relative to many listed service providers.
The fair value framework, which looks at factors such as growth potential, profitability, size and risk, points to a lower P/E than where Mitie Group currently trades. That gap suggests buyers today are paying up for the existing earnings stream and whatever stability or contract quality they believe is embedded in it. Anyone assessing the shares now needs to decide whether that richer multiple feels justified by the company’s contract base, cash generation and execution record, or whether it leaves less room for comfort if conditions change. Explore the numbers behind Mitie Group's P/E valuation.
The Mitie Group Narrative: What Would Justify Today's Price?
Mitie Group's valuation puzzle only really comes into focus once the assumptions behind it are laid out in plain language. Narratives on Simply Wall St's Community page try to do exactly that by spelling out what would need to happen to Mitie Group's future growth, earnings and margins for the shares to be worth materially more or materially less than they are today. This turns a single ratio or model output into a concrete set of expectations that you can follow over time.
Bulls see more headroom in Mitie Group than the cautious crowd, who view much of the story as already priced in.
Bull case: roughly fairly valued
"Integration of Marlowe, including procurement savings, property rationalisation, field force automation and IT consolidation, targets at least £30m of cost synergies by FY '28. This can support net margin expansion and cash generation if delivered as outlined…"
Discover why this Narrative puts Mitie Group at roughly fairly valued.
Bear case: roughly fairly valued
"The current valuation and agreed £3.1b cash offer imply that the share price already reflects a fair view of Mitie Group’s delivery on its plan and future cash returns…"
Explore why this Narrative puts Mitie Group at roughly fairly valued.
Mitie Group’s share price is only one side of the decision
Valuation tells you what the market is willing to pay today, but the analyst models looking a few years ahead offer a separate lens on where expectations sit for this business. Explore where analysts expect Mitie Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com