
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Fast Track Status Could Be A Key Moment For Astellas Pharma Stock (TSE:4503)
- Vir Biotechnology reported that the FDA granted Fast Track designation to VIR-5500, a PSMA-targeted dual-masked T-cell engager co-developed with Astellas Pharma for late-line metastatic castration-resistant prostate cancer, after Phase 1 data indicated the candidate was generally well tolerated with promising anti-tumor activity.
- The broad Phase 1 program for VIR-5500, spanning six dose-expansion cohorts including multiple combination regimens, points to meaningful clinical investment that could influence how Astellas Pharma allocates future R&D and positions its oncology portfolio.
- We will now assess how Astellas Pharma's Fast Track status for VIR-5500 might reshape the existing investment narrative around its pipeline.
Scan beyond Astellas Pharma and line up other late stage oncology opportunities using our curated 10 healthcare AI stocks that are pushing new approaches in targeted cancer treatments.
Astellas Pharma Investment Narrative Recap
Astellas Pharma asks you to believe that a shrinking XTANDI franchise can be replaced over time by a broader group of oncology and specialty drugs, supported by cost cuts and a more efficient R&D engine. The Fast Track status for VIR-5500 looks directionally helpful for that story, but the key near term swing factor still sits with existing strategic brands and cost execution.
The largest immediate risk has not changed. Pressure on U.S. pricing, including the scheduled XTANDI price cut from 2027 and future generic entry, could drag revenue and margins faster than new assets ramp. VIR-5500 is early, so setbacks here would hurt sentiment more than the near term income statement.
With no other fresh disclosures tied directly to this Fast Track move, the clearest comparison point remains Astellas Pharma’s own stated plan to start 10 or more Phase III or pivotal studies by FY2030. VIR-5500 currently sits in Phase 1, so the main read across is whether the collaboration with Vir helps fill that future late stage roster.
For you as a shareholder, the operational question is whether oncology programs like VIR-5500 can realistically grow into that post XTANDI gap while Astellas Pharma pursues about ¥200b of recurring cost savings and a 30% core operating margin structure. Execution on these productivity goals will likely matter more to cash flow than any single early stage asset.
What The Astellas Pharma Forecasts Are Really Saying
Astellas Pharma's narrative projects ¥1,953.3b revenue and ¥263.7b earnings by 2029. This aligns with analyst assumptions of a 4.9% yearly revenue decline and an earnings decrease of about ¥101.2b from ¥364.9b today.
Discover how Astellas Pharma's fair value indicates a 4% potential upside to its current price that may not last much longer.
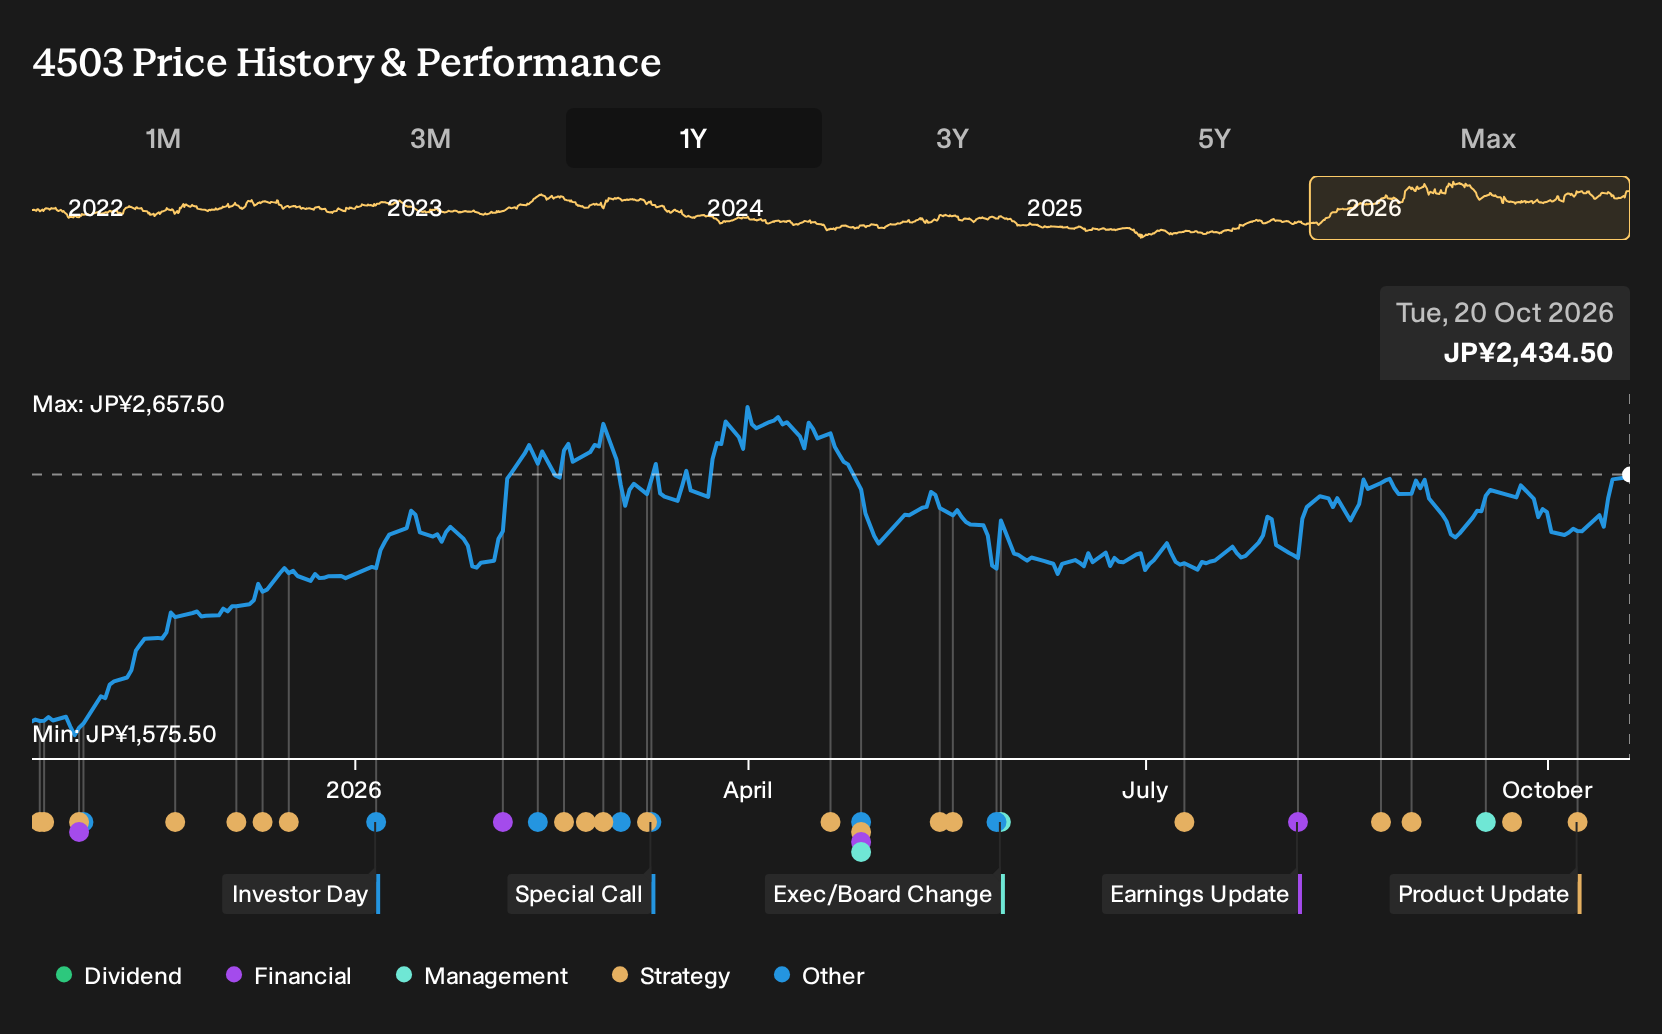
Exploring Other Perspectives
Some of the most optimistic analysts already framed Astellas Pharma as an underappreciated R&D engine, expecting 2029 earnings of about ¥341.2b instead of the ¥263.7b consensus. You can see how a potential cluster of oncology assets like VIR-5500 might push that story further or prompt a rethink, so it pays to compare several viewpoints.
Explore 2 other Astellas Pharma fair value estimates, including one that suggests as much as 85% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Astellas Pharma research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Astellas Pharma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Astellas Pharma's overall financial health at a glance.
Looking for more Astellas Pharma investment ideas?
If you want to stress test your view on Astellas Pharma, it can help to line it up beside other businesses with different risk, income, and balance sheet profiles. The Simply Wall St Screener lets you do that quickly by filtering for the traits you care about most.
- For investors who care most about resilience and fewer surprises, compare Astellas Pharma with 21 resilient stocks with low risk scores that pair steadier fundamentals with lower risk scores.
- If capital preservation and income matter more to you than rapid expansion, weigh Astellas Pharma against 29 dividend fortresses built around higher yielding payouts.
- When you want to hunt for less crowded ideas, set Astellas Pharma alongside 73 high quality undiscovered gems that combine solid financial quality with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com