
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Elastic Stock And 2 Cloud Reliability Plays For Always On Enterprise Demand
A single outage at a Google Cloud data centre just reminded big banks, logistics operators and governments how fragile always on really is, and investors how valuable reliability can become when screens go dark. When one provider stumbles, demand for sharper observability and incident tooling can shift quickly, and that can move expectations for the companies behind it. This article walks through three stocks whose businesses are closely exposed to this latest disruption story, and explains why that link could matter for your portfolio decisions.
The three stocks that follow are just a sample set. The full screen surfaced 16 more U.S. and U.K. software companies tied to cloud reliability and observability with equally compelling narratives that are not covered here. If you want to identify patterns across that broader group and analyze which tickers best fit your own risk and sector views, head straight into the Cloud Reliability & Observability Software for Regulated Industries screener.
Duos Technologies Group (DUOT)
Overview: Duos Technologies Group builds AI enabled monitoring and modular edge data center solutions that support real time inspection for infrastructure and logistics clients.
Operations: Duos Technologies Group generates about $18 million from services and consulting, with a smaller $0.1 million contribution from data center hosting.
Market Cap: $170 million
Duos Technologies Group fits this reliability focused screen because its edge data centers and monitoring platforms are built for always on, mission critical workloads where outages carry real economic and reputational cost.
"The rapid expansion of AI workloads and cloud services is pushing hyperscalers toward distributed, lower power Edge deployments. This positioning may allow Duos' modular data centers to pursue larger contracts and recurring site revenues, which may support sustained top line growth and improving gross margins."
The real swing factor is how one pressure on future profitability interacts with that capacity story and filters through to long term margins.
That margin tension is exactly what the full narrative for Duos Technologies Group unpacks, separating hype from where Duos Technologies Group’s economics could realistically accelerate or stall next.

Elastic (ESTC)
Overview: Elastic provides a search and AI based data platform that powers observability, security and search across hybrid and multi cloud systems for large enterprises.
Operations: Elastic generates about US$1.8b from software and programming, split between roughly US$976 million in the United States and US$826 million in the rest of the world.
Market Cap: US$9.6b
Elastic matters for this reliability focused screen because its observability stack turns raw logs, metrics and traces into a single control layer across clouds. This is exactly what regulated sectors look for when outages expose how fragile their monitoring really is.
"Ongoing consolidation of observability data such as logs, metrics and traces onto unified platforms with native Prometheus, PromQL and OpenTelemetry support, combined with Elasticsearch 9.5 columnar metrics storage that targets about 3 bytes per metric sample and faster queries, is designed to win replacements of fragmented observability stacks and can support sustained revenue growth and gross margin efficiency."
The real test will come if one silent shift in how large customers price that consolidated footprint hits both demand and long term margins.
That pricing shift is exactly what the full narrative for Elastic unpacks, showing where Elastic’s observability reach could accelerate, stall, or quietly decouple from headline demand.

FatPipe (FATN)
Overview: FatPipe provides SD-WAN, SASE, and network monitoring software that helps enterprises keep distributed networks secure, resilient, and observable.
Operations: FatPipe generates about $20 million from internet software and services, with roughly $20 million from the United States and under $1 million abroad.
Market Cap: $71 million
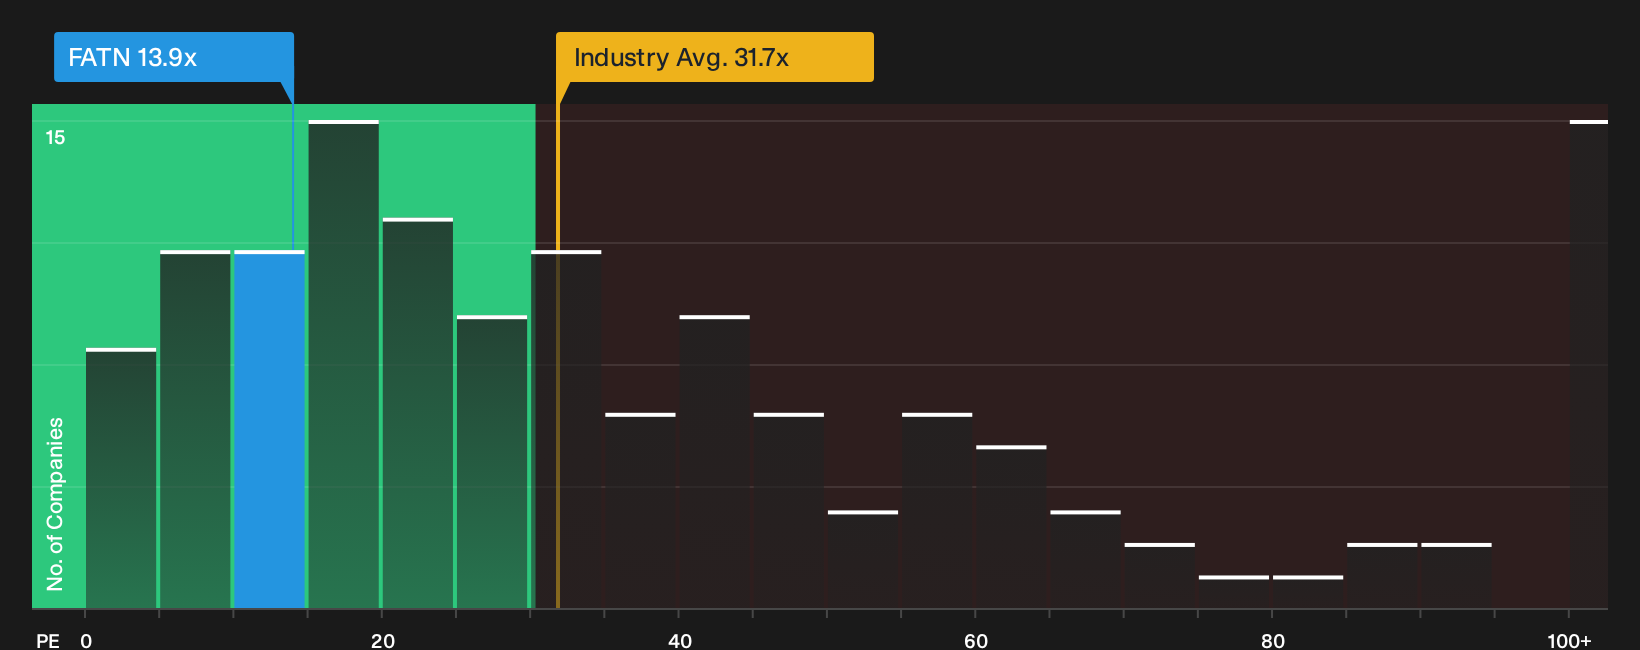
FatPipe fits this reliability screen because its SD-WAN, SASE, and monitoring tools sit on the path of every packet when regulated and distributed organisations try to keep branches, clouds, and data centres online during outages such as Google Cloud’s recent issue. Strong profitability and a relatively low P/E give that uptime story additional weight, depending on how one relatively quiet funding constraint shapes the next stage of growth.
That quiet funding constraint is the hinge, so go straight to the 4 key rewards and 2 important warning signs (1 is major!) to see how FatPipe’s profitability and growth ambitions could really interact.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every chart lights up, early entries are gone, spreads widen, and mispricing drops away. Scan new themes now and focus on potential early opportunities.
- Spot potential breakouts earlier by reviewing hand picked 20 high quality undiscovered gems that remain under the radar for now, before momentum screens start flashing the same tickers.
- Identify steady cash generators by scanning a curated list of solid balance sheet and fundamentals (25 results) so you focus on companies with balance sheets that can support staying power while it matters.
- Explore structural shifts in power demand by checking a filtered 42 power grid technology and infrastructure stocks and see which infrastructure owners could benefit if grid spend continues.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com