
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Liberty Energy (LBRT) Shares Just Moved, So What Is Drawing Attention?
Liberty Energy (LBRT) heads into its earnings release this Wednesday after the close with investors watching two things closely: the planned 3 GW distributed power buildout and utilization of its advanced fracturing fleets.
Recent trading has been choppy for Liberty Energy. The share price is at $17.09 after a 1-day share price return of 2.95%. However, it is down 31.31% over 90 days, even as the 1-year total shareholder return is 9.41%. This points to fading near term momentum and a market reassessing execution risk around earnings and the 3 GW buildout.
Scan how Liberty Energy compares with other capital intensive energy service plays by running the hand picked list of solid balance sheet and fundamentals (25 results) now that earnings risk is front and center.
The recent slide in Liberty Energy after a positive 1 year return leaves a simple fork in the road: Is most of the easy upside already spent, or does the current valuation still leave meaningful headroom?
Most Popular Narrative: 40% Undervalued
Liberty Energy is trading at $17.09, while the most followed narrative pegs fair value around $28.61. This frames the current slide as a valuation gap rather than a complete breakdown in the story.
The main thing that has to go right is Liberty Energy successfully executing its capital intensive pivot toward a 3 GW distributed power platform while keeping its frac fleets tightly utilized and cost efficient through digiTechnologies and AI driven tools.
The current valuation implies the market is discounting Liberty Energy’s plan to deploy roughly 3 GW of on site power with targeted 5 to 6 year cash on cash paybacks and double digit unlevered returns, while also questioning how much of the tight frac and energy security backdrop will translate into durable cash generation for shareholders.
See why 9 investors see Liberty Energy as 40% undervalued.
Result: Fair Value of $28.61 (UNDERVALUED)
Still, the Liberty Energy narrative could be knocked off course if the US$1.5b 2026 capex push strains free cash flow or if completions pricing softens further.
Find out about the key risks to this Liberty Energy narrative.
Another View: Liberty Energy Through The P/E Lens
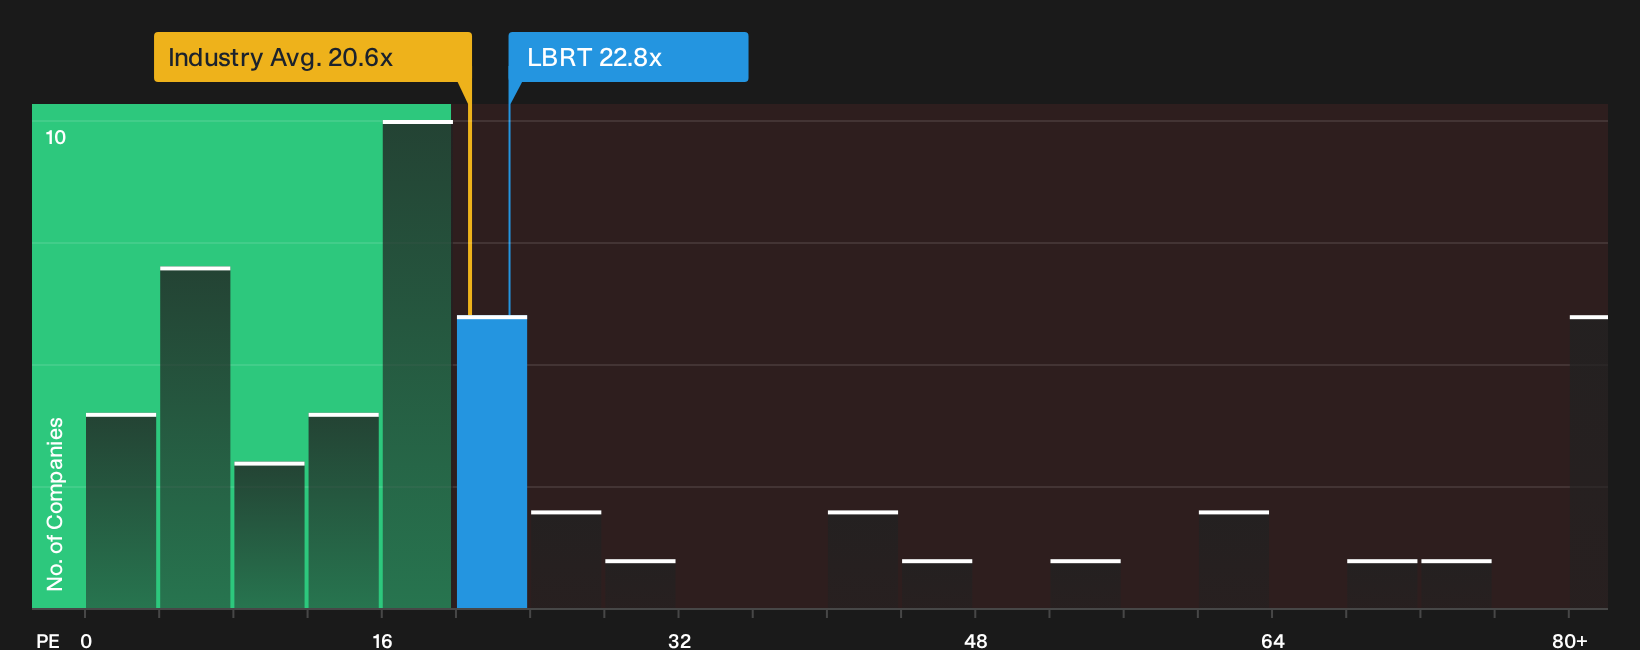
On plain P/E maths, Liberty Energy looks less generous. The stock trades around 22.8x earnings, above the US Energy Services sector on 20.4x and well ahead of a fair ratio of 12.9x that our model suggests the market could eventually lean toward. That gap points to real valuation risk if sentiment cools again. Is this a rerating that sticks? Or a premium that proves fragile around the next set of numbers?
To stress test that question against the detailed earnings and valuation breakdown, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Liberty Energy is clearly split right now. Treat this as your cue to move quickly, review the data for yourself, and weigh both the upside potential and the pressure points starting with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Liberty Energy?
If Liberty Energy has your attention but you want a wider watchlist, use this moment to broaden your opportunity set before the next wave of results hits.
- Target potential mispricings by scanning a curated pool of companies that screen as strong value opportunities through the 35 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with robust finances using the 32 resilient stocks with low risk scores.
- Identify quality opportunities before they gain wider attention through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com