
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
PG&E (PCG) Faces A Valuation Split, Is The Stock Still Cheap?
PG&E (PCG) shares closed at US$13.13 on 16 October 2026 after recent trading that left the stock down over the past month and the past 3 months, sharpening focus on valuation and fundamentals.
PG&E’s recent slide has been steep, with a 90 day share price return down 24.9% and the year to date share price return lower by 19.3%. However, the 5 year total shareholder return of 15.0% shows a very different long run experience for investors.
Scan how PG&E compares with other utilities under pressure by reviewing the hand picked 42 power grid technology and infrastructure stocks that are shaping tomorrow's energy infrastructure.
Bulls interpret PG&E’s lower share price relative to its earnings and cash flows as an opportunity, while bears point to long-running risks and recent losses. Which story do the current valuation markers appear to support next?
Most Popular Narrative: 30% Undervalued
PG&E’s most followed valuation narrative pegs fair value around $18.69, well above the latest $13.13 close. This puts the recent share price slide in a different light for anyone focused on long term cash generation and grid investment.
Expanding opportunities for capital investment in grid modernization, wildfire mitigation, and resilience remain in focus, with PG&E reiterating a US$73b capital plan through 2030 and advancing large undergrounding programs and grid-edge sensing deployments. This supports future regulated earnings and rate base growth even after the announced US$2b reduction to 2027 capital spending.
See why 26 investors see PG&E as 30% undervalued.
Result: Fair Value of $18.69 (UNDERVALUED)
Still, the narrative can unravel quickly if wildfire liability rules tighten or if pressure from California legislation limits PG&E’s ability to recover grid and safety spending.
Find out about the key risks to this PG&E narrative.
Another View: PG&E Through A Cash Flow Lens
First impressions suggest PG&E looks inexpensive on earnings, with a P/E of 9.5x against a US Electric Utilities average of 20.1x and a peer average of 22x. Yet the SWS DCF model tells a different story, with an estimated future cash flow value of $9.60, implying the shares trade above that level today.
When earnings multiples flag value while a cash flow model points to overvaluation, it raises a simple question for investors: Which set of assumptions about PG&E’s future cash generation feels more realistic to you?
Look into how the SWS DCF model arrives at its fair value.
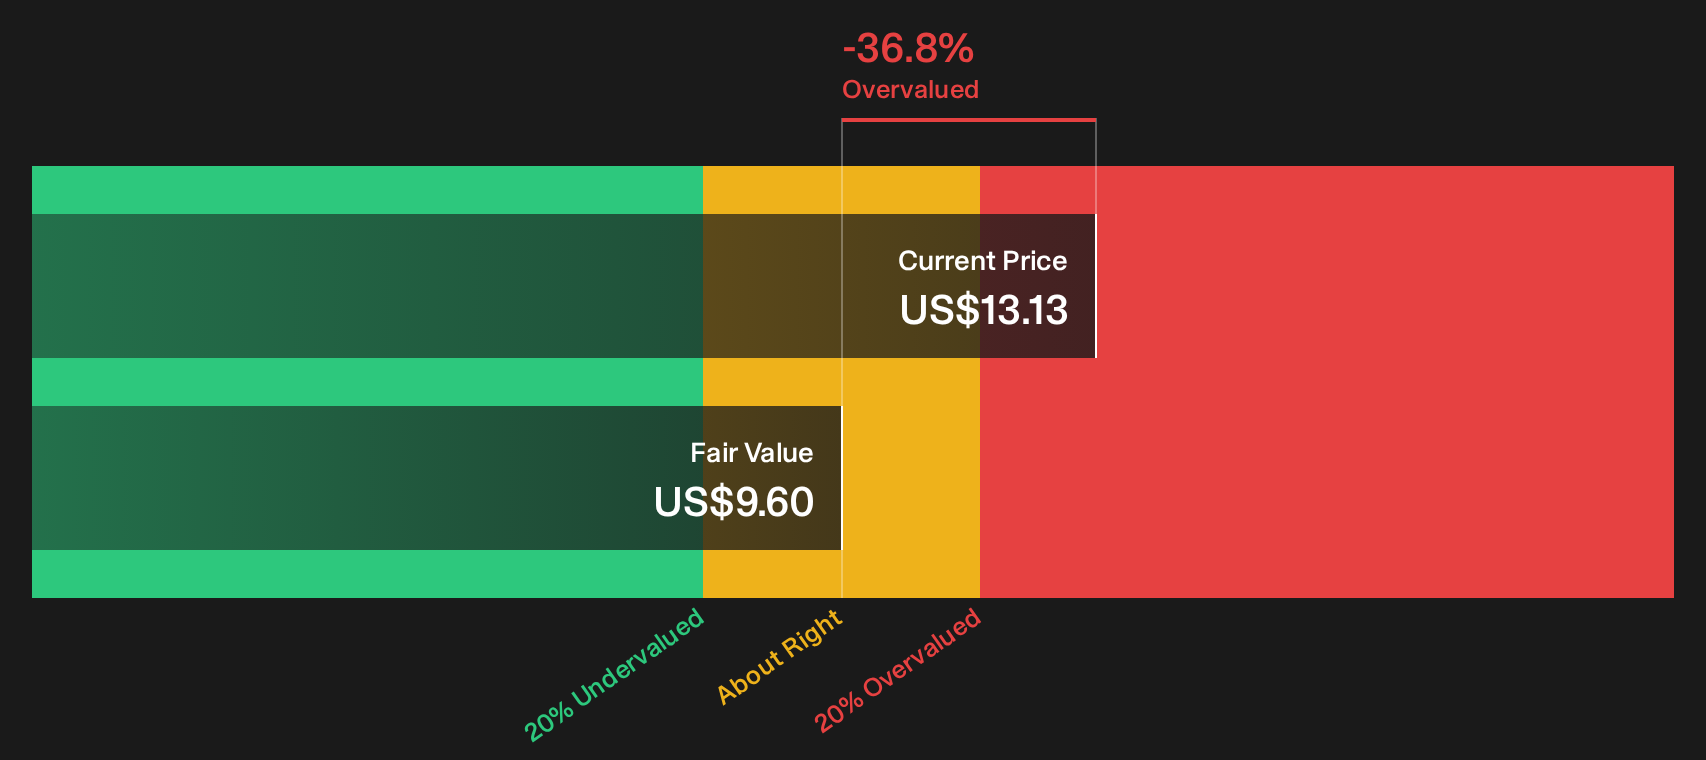
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PG&E for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With mixed signals around PG&E’s valuation story, it pays to move quickly, pull up the underlying data, and pressure test both the risk and reward angles for yourself. To frame that decision, start with the 4 key rewards and 3 important warning signs.
Looking for more PG&E alternatives and investment ideas?
If PG&E has your attention, consider broadening your watchlist with a few focused stock ideas that may help you compare risk, income, and value.
- Explore resilient compounding potential with a 35 high quality undervalued stocks that screens for quality businesses trading below their assessed worth.
- Emphasize capital preservation by reviewing a 32 resilient stocks with low risk scores that filters for companies with more robust risk profiles.
- Identify fresher opportunities early by scanning a 20 high quality undiscovered gems built around under-the-radar stocks with stronger fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com