
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Comstock Resources (CRK) Could Be 7% Undervalued After Cautious Analyst Commentary
Analyst caution and recent price moves
Comstock Resources (CRK) is back in focus after recent analyst commentary highlighted weak long term growth trends, softer EBITDA margins, and ongoing negative free cash flow, all against a backdrop of natural gas price volatility.
Recent trading has been more upbeat, with a 10.9% 1 month share price return and a 7.23% 3 month share price return. However, Comstock Resources is still down 39.61% on a year to date share price basis, and its 1 year total shareholder return has declined 21.2%. This points to short term momentum improving while longer term performance remains weak as investors reassess growth prospects and balance sheet risks in light of gas price swings.
Scan analyst-favored gas producers with stronger trends than Comstock Resources by reviewing our handpicked 35 high quality undervalued stocks, which balance growth ambitions with more resilient financial profiles.
Comstock Resources has real scale in Haynesville gas and a fresh bump in the share price. The harder part is judging whether that mix of assets, risks, and recent cash burn is already reflected in the valuation.
Most Popular Narrative: 7% Undervalued
Comstock Resources last closed at $14.24, while the most widely followed narrative places fair value closer to $15.23, implying a modest discount that depends on how investors view its Haynesville growth options and capital intensity.
The company's proactive development of Western Haynesville-specific midstream infrastructure (such as a major new gas treating plant) is expected to allow for higher production levels, improved price realizations, and increased ability to capitalize on expanding U.S. LNG export capacity, thereby supporting revenue growth.
The recently announced strategic collaboration with NextEra Energy for potential gas-fired power and data center projects near Western Haynesville leverages proximity to major demand centers and existing infrastructure; this could create new high-margin, long-term sales channels and provide additional stable cash flows.
See why 10 investors see Comstock Resources as 7% undervalued.
Result: Fair Value of $15.23 (UNDERVALUED)
Still, the Comstock Resources story hinges on Haynesville concentration and heavy capital needs, either of which could pressure cash generation and challenge the current fair value narrative.
Find out about the key risks to this Comstock Resources narrative.
Another View on Comstock Resources Valuation
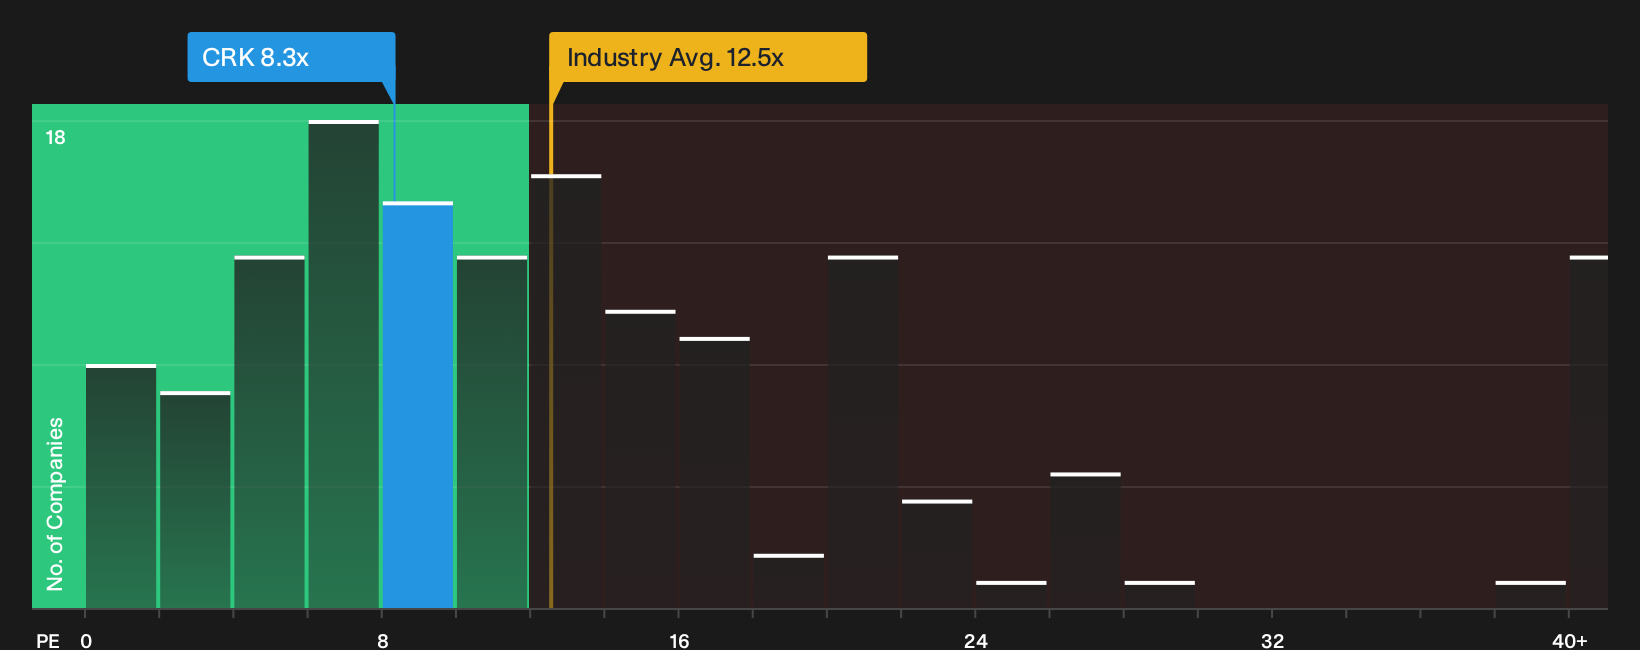
The first narrative paints Comstock Resources as modestly undervalued. The earnings multiple tells a different story. CRK trades on a P/E of 8.3x, while the fair ratio points closer to 6.2x, which implies the shares could be priced a bit rich if the market moves toward that level.
That gap, even though the current P/E is below the 12.5x industry average and below peers at 9.6x, raises a practical question for investors. Is the risk that expectations get reset down to the fair ratio more important than the apparent discount to the broader oil and gas group See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of cautious metrics and modest optimism around Comstock Resources feels finely balanced, consider reviewing the numbers yourself. Start by weighing its 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Comstock Resources?
Do not stop your research with Comstock Resources. Broaden your watchlist now, or you risk missing opportunities that better match your risk tolerance and return goals.
- Target resilient balance sheets by checking companies on the list of solid balance sheet and fundamentals (25 results) that pair sturdier finances with room for future growth.
- Hunt for under-the-radar potential across the 20 high quality undiscovered gems that combine quality fundamentals with lighter market attention.
- Dial back volatility by screening for 32 resilient stocks with low risk scores that aim to keep drawdowns and fundamental risks in tighter check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com