
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Western Alliance (WAL) Stock Could Trade Below Fair Value On Fresh Q3 Earnings
Western Alliance Bancorporation has seen its share price move around in recent years, and the question now is whether the current US$73.63 level is adequately supported by the bank's earnings power. With fresh profit news in the mix, the valuation debate has shifted from price action alone to what those earnings really justify.
- Over the past 3 years the stock has gained 87.9%, which puts real pressure on the earnings story to explain how that kind of return stacks up.
- Recent profit growth, helped by lower funding costs and firmer asset quality, can support arguments that Western Alliance's earnings profile may carry more weight in the valuation discussion than it did a few years ago.
- There is a second opinion on Western Alliance Bancorporation worth weighing. See what analysts think Western Alliance Bancorporation's shares could be worth.
The stock's next move may depend on whether Western Alliance Bancorporation's current earnings are strong enough to justify the price investors are paying today.
If you want a wider earnings cross check alongside Western Alliance Bancorporation, a focused stock screen is a useful next step. A good place to start is 35 high quality undervalued stocks
Is Western Alliance Bancorporation Still Cheap on Earnings?
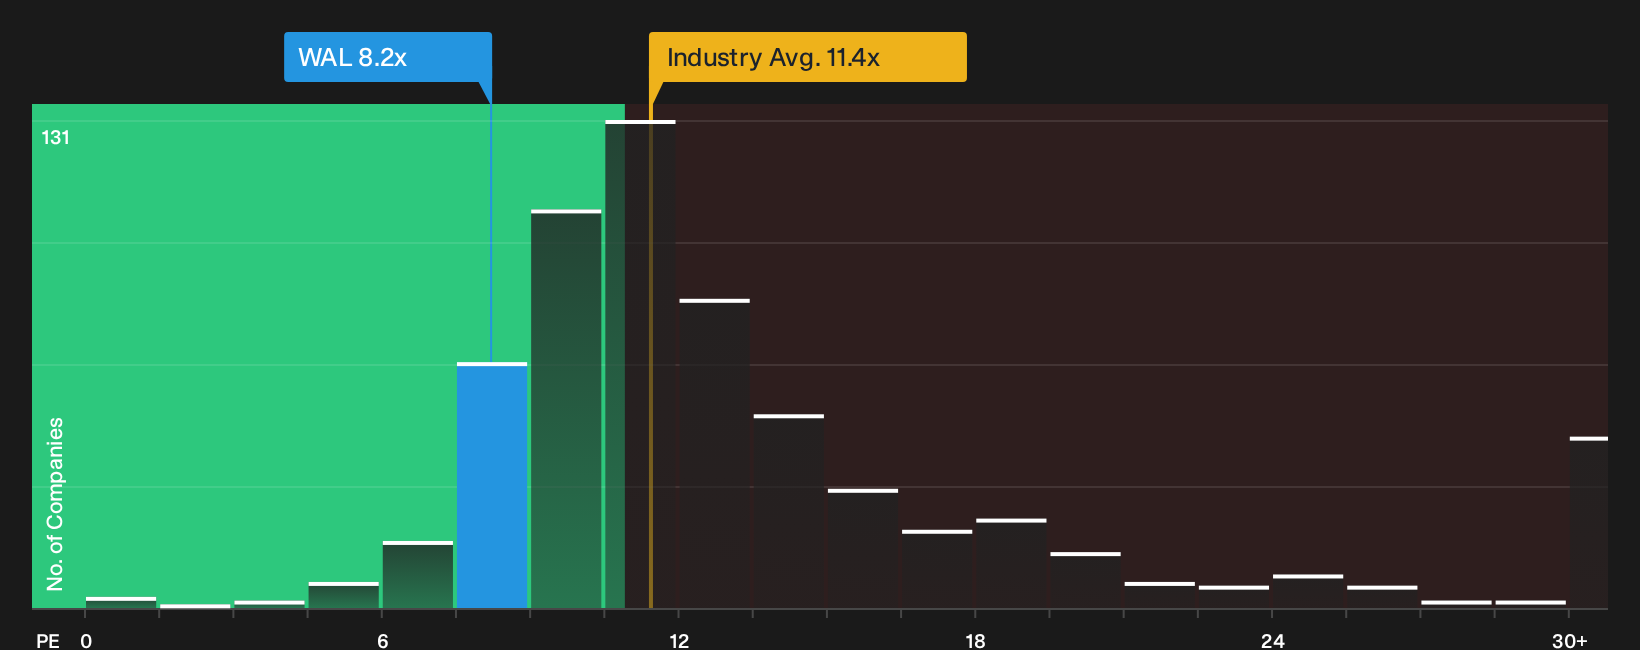
P/E is usually the cleanest way to compare banks, because earnings already reflect funding costs, credit charges and fee income in one figure. Western Alliance Bancorporation trades on a P/E of about 8.2x, which sits below the Banks industry average of around 11.4x and under the peer group near 12.7x.
That gap appears wider once you factor in the fair multiple implied by Western Alliance Bancorporation's own growth, margins, size and risk profile. This framework points to a higher P/E than the market currently assigns. Because the Q3 2026 update highlighted firmer profitability and asset quality, the current 8.2x still prices the stock at a level that this framework suggests could be lower than the valuation it implies. Explore the numbers behind Western Alliance Bancorporation's P/E valuation.
The Western Alliance Bancorporation Narrative: What Would Justify Today's Price?
Narratives for Western Alliance Bancorporation pick up where the P/E puzzle leaves off by spelling out which paths for future growth, profitability and earnings would need to occur for the current share price to look meaningfully high or low. Each scenario links a fair value estimate to a clear story about Western Alliance Bancorporation's possible catalysts and key risks, so you can track over time which version of events appears closest to reality on Simply Wall St's Community page.
One of the top community narratives on Western Alliance Bancorporation: 21% undervalued
"The main factor that has to go right is that Western Alliance Bancorporation executes on building and scaling its specialized, low cost deposit and fee businesses..."
Discover why this Narrative puts Western Alliance Bancorporation at 21% undervalued.
One more angle on Western Alliance Bancorporation that could change the story
Balance sheets and P/E ratios only go so far if the people in charge are not aligned with shareholders, so it pays to look at who runs Western Alliance Bancorporation and how they are rewarded. See who runs Western Alliance Bancorporation and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com