
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Venture Global (VG) Stock May Be Undervalued As AI Power Plans Expand
Venture Global has seen its share price surge year to date, and fresh headlines around massive energy investments for AI data centers put an extra spotlight on whether that move lines up with what its earnings can support. With the stock now reset at a higher level, the key issue for you is whether current profits and profit potential really stack up against today’s valuation.
- The share price is up 82.0% year to date, which puts a lot more weight on the question of how much earnings strength the current P/E can reasonably reflect.
- The company’s US$17.2b equipment commitment to build gas-fired power capacity for AI data centers may reshape future earnings power, but it also concentrates a large amount of capital on projects whose cash flows will take years to arrive.
- Your read on Venture Global is one view; the desks covering it have another. See what analysts think Venture Global's shares could be worth.
The issue now is whether Venture Global’s current share price is justified by the earnings the business already produces, together with what its existing operations can realistically add over time.
If you want a broader starting point for research around themes like Venture Global’s AI power build out, a focused stock screen such as 55 AI infrastructure stocks.
Does Venture Global Look Undervalued on Earnings?
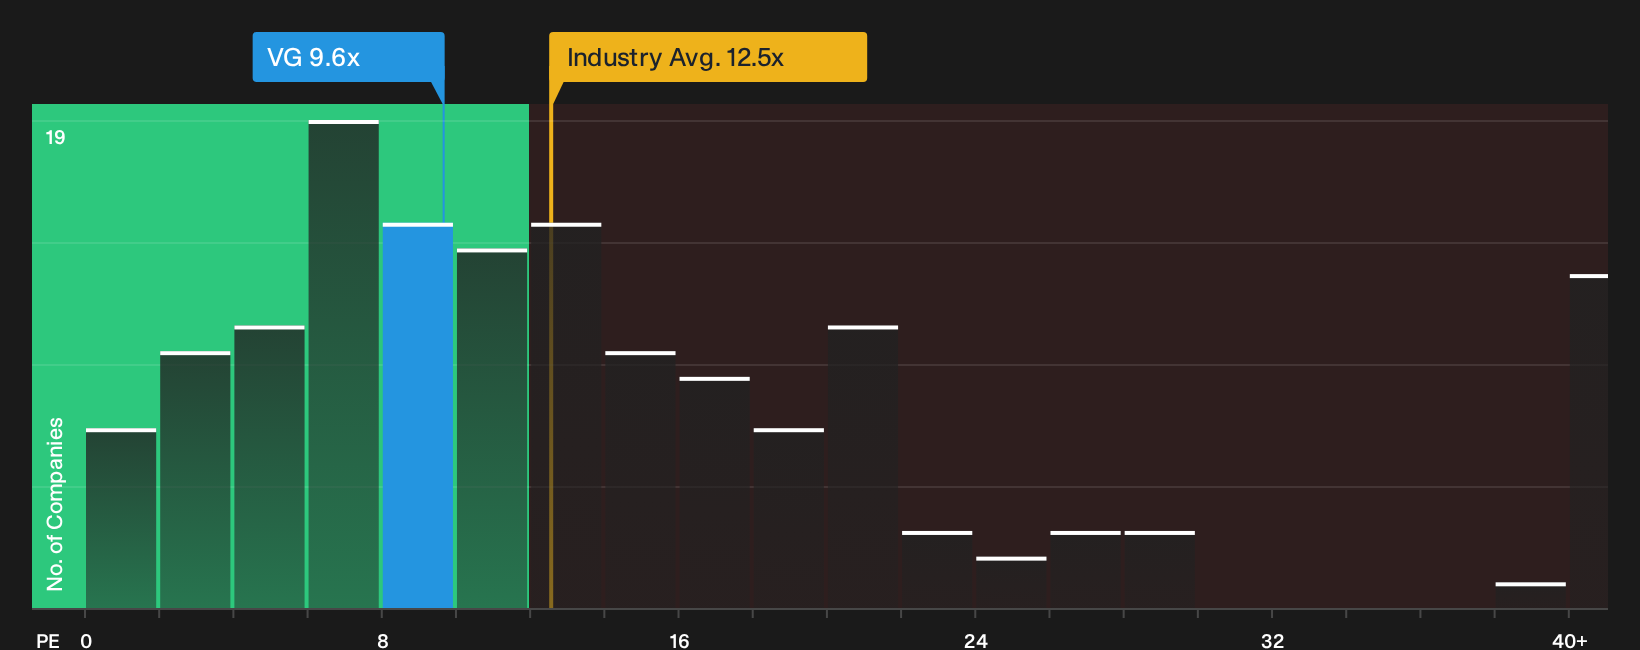
The P/E ratio works well for Venture Global because investors are already focused on how quickly its earnings can support the recent share price reset. On this yardstick, the stock trades around 9.6x earnings, which is below the broader oil and gas sector on roughly 12.5x and also below the peer group near 20.3x. That places the current valuation at a visible discount to both direct comparables and the wider industry, even after the sharp year to date move.
A tailored fair P/E that blends Venture Global’s growth profile, margins, size and risk points to a higher multiple than where the shares trade today, so the current P/E screens as undervalued on this model. Because the new US$17.2b AI power build out is capital heavy and long dated, the present gap suggests that the market is not fully pricing those earnings into the P/E yet. Despite that large project lifting interest in the stock, the earnings multiple still reflects a discount to what this framework suggests could be justified. Explore the numbers behind Venture Global's P/E valuation.
The Venture Global Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Venture Global valuation puzzle leaves off. They spell out which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price, and each one links a fair value estimate to a clear story about Venture Global’s possible catalysts and risks, so you can track over time which version of events appears to be unfolding on the Community page.
One of the top community narratives on Venture Global: 8% undervalued
"This narrative explores a more pessimistic perspective on Venture Global compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts..."
Discover why this Narrative puts Venture Global at 8% undervalued.
One more piece of the Venture Global story you should not ignore
Valuation only tells part of the story for Venture Global, since Simply Wall St’s checks have also highlighted specific areas of concern that you may want to weigh for yourself. Take a closer look at 3 warning signs (3 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com