
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DICK'S Sporting Goods (DKS) Stock May Still Look Cheap Despite Dividend Pressure
DICK'S Sporting Goods has seen its share price move sharply in both directions over recent years, which puts a spotlight on a simple question for you as an investor: Is the current valuation supported by the earnings power the retailer is generating today?
- Over the past 3 years, the stock has gained 45.9%, which puts past buyers in a comfortable position but makes it more important to test whether profits still justify the current tag.
- Pressure on cash flow and gross margins following the Foot Locker acquisition may reshape how much of DICK'S Sporting Goods' earnings can be retained in the business versus paid out to shareholders.
- There is a second opinion on DICK'S Sporting Goods worth weighing. See what analysts think DICK'S Sporting Goods's shares could be worth.
The stock's next move may depend on whether the current price fairly reflects what DICK'S Sporting Goods is earning today and is likely to earn over time.
You can test the same earnings versus price question you are asking about DICK'S Sporting Goods across a broader group of stocks using our 35 high quality undervalued stocks.
Is DICK'S Sporting Goods Still Cheap on Earnings?
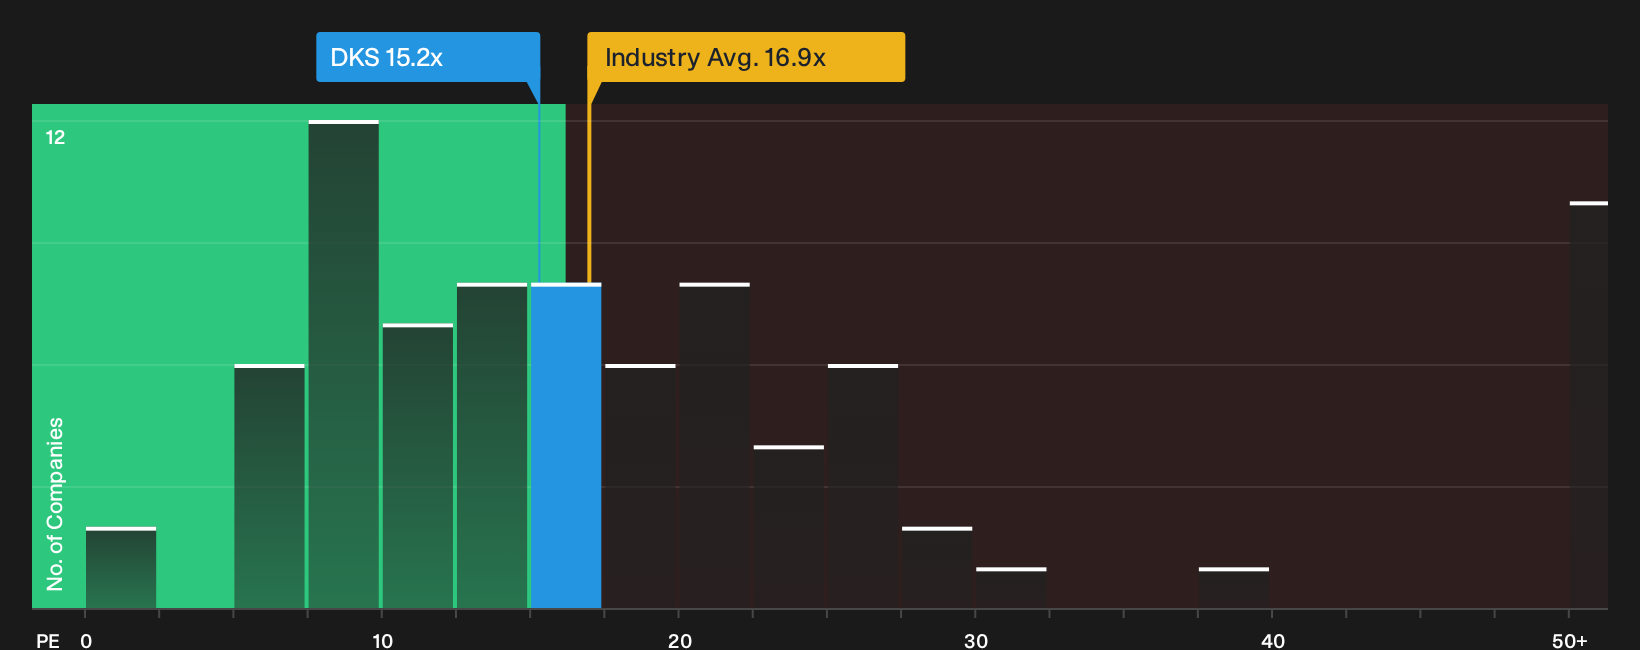
The P/E ratio is a useful way to assess DICK'S Sporting Goods, as earnings remain the clearest anchor for how the market is weighing the retailer's cash generation against the Foot Locker deal. On this measure, the stock trades at about 15.2x earnings, which is below both the Specialty Retail average near 16.9x and the broader peer group around 22.0x. That gap indicates the market is applying a lower earnings multiple than it does to many comparable retailers.
Because analysts’ fair multiple model points to a higher P/E than where DICK'S Sporting Goods currently trades, the shares appear undervalued on this earnings yardstick. Recent concerns about dividend pressure and margin strain after acquiring Foot Locker help explain why sentiment is cautious. However, the current P/E still sits below what the fair value framework suggests might be justified for the business. Explore the numbers behind DICK'S Sporting Goods's P/E valuation.
The DICK'S Sporting Goods Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E discussion leaves off for DICK'S Sporting Goods' stock by spelling out which future paths for sales, profitability and earnings would need to play out for the current price to look meaningfully high or low. Rather than relying on a single valuation output, each Narrative lays out the assumptions that sit behind its view so you can compare those expectations with the actual numbers as they are reported over time on the Community page.
Community views on DICK'S Sporting Goods split around how much execution risk is baked into the current price versus how much the ecosystem around experiential stores and Foot Locker can still deliver.
Bull case: 9% undervalued
"The current valuation suggests that the market is heavily discounting the Foot Locker risks and the recent guidance cuts, and is not fully recognizing DICK'S Sporting Goods for the contribution from high-ROI store formats, ancillary platforms, and the potential benefits of the combined athletic footwear ecosystem..."
Discover why this Narrative puts DICK'S Sporting Goods at 9% undervalued.
Bear case: 27% overvalued
"Full-year Foot Locker pro forma comp guidance moved from 1.5% to 3% growth to a range of 2% growth to flat, and the operating income expectation shifted from a profit of $110M to $150M to a loss of $40M to $80M..."
Explore why this Narrative puts DICK'S Sporting Goods at 27% overvalued.
The DICK'S Sporting Goods share price is only one piece of your decision
Price and current earnings tell part of the story, but the projections for where DICK'S Sporting Goods could be a few years from now give you another reference point to weigh against today's valuation. Explore where analysts expect DICK'S Sporting Goods to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com