
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ACM Research (ACMR) Rebounds As China Growth Story Puts Fair Value Back In Focus
ACM Research (ACMR) is back in focus after a 6.1% move to US$56.35, as part of a broader lift in semiconductor equipment stocks that drew institutional money into the group.
That sharp move in ACM Research comes after a choppy spell, with the 7 day share price return down 17.6% and the 90 day share price return down 41.1%, even as the year to date share price return is 25% and the 1 year total shareholder return is 41%. This indicates that momentum has recently cooled after a strong multi year run that delivered a very large 3 year total shareholder return and a 57% 5 year total shareholder return.
Surface other potential breakouts in the same space by scanning our hand picked 55 AI infrastructure stocks alongside ACM Research.The latest jump in ACM Research could point to investors refocusing on the business after recent volatility, or it could simply reflect renewed enthusiasm for semiconductor equipment stocks. The valuation now needs a closer look.
Most Popular Narrative: 51% Undervalued
ACM Research is being framed as significantly undervalued in the most widely followed narrative, with a fair value of $115 versus a last close near $56. That gap only holds if the business delivers on the growth and margin profile embedded in the long range forecasts that underpin this view.
Multiyear capacity buildouts at mainland China fabs, with the local equipment market projected to move from more than US$50b in 2025 to above US$80b by 2029 and ACM Research already reporting strong positions in cleaning and electroplating, give the company room to convert its growing order book and backlog into higher revenue and earnings.
See why 90 investors see ACM Research as 51% undervalued.
Result: Fair Value of $115 (UNDERVALUED)
Still, heavy reliance on Mainland China and ongoing exposure to U.S. China export controls could quickly challenge the bullish ACM Research valuation story if conditions tighten.
Find out about the key risks to this ACM Research narrative.
Another View: ACM Research Through The P/E Lens
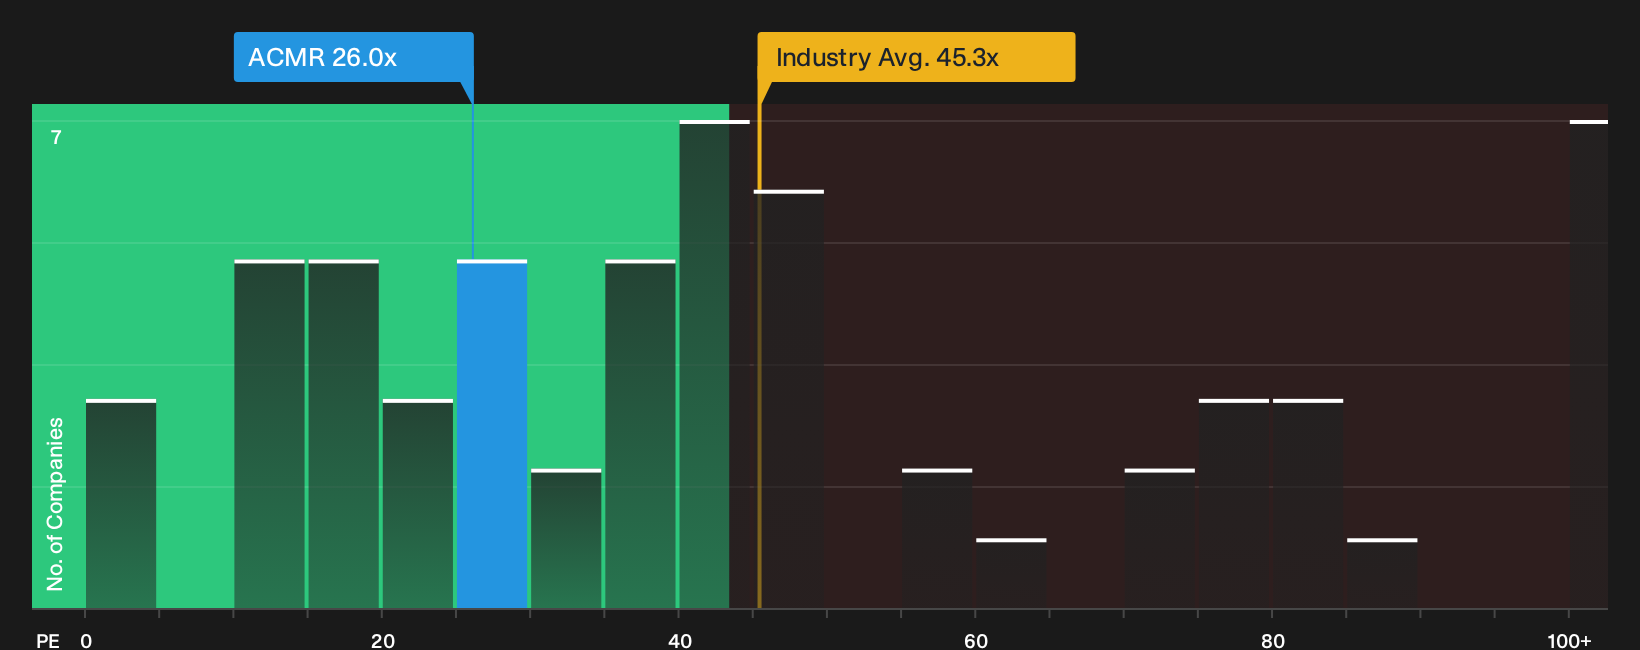
ACM Research looks very different when you move away from the 51% undervalued fair value story and focus purely on its P/E ratio. The stock trades on 26x earnings, while direct peers sit near 87.1x and the broader US Semiconductor group around 45.3x. The fair ratio for ACM Research is 34.1x, which suggests the multiple could shift higher if sentiment aligns with that benchmark, or compress further if earnings quality and China risk dominate the conversation. Which side of that gap do you think the market will price in over time?
For a closer look at how those P/E gaps stack up in practice, including how much of this discount may reflect risk rather than opportunity, See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ACM Research for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the bullish and cautious threads in the ACM Research story feel balanced to you right now? Act while sentiment is still in flux and weigh the trade off yourself by checking the 4 key rewards and 2 important warning signs.
Looking for more ACM Research style ideas?
If ACM Research has your attention, do not stop here. Broaden your watchlist now and give yourself more ways to react when conditions shift.
- Target resilient compounding potential by scanning a curated set of rock solid balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced potential by reviewing a focused group of quality companies trading at attractive levels using the 35 high quality undervalued stocks.
- Build a portfolio that works harder for you by zeroing in on income opportunities with the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com