
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Haemonetics (HAE) Below Fair Value On PerQseal Elite Approval?
FDA approval of PerQseal Elite puts Haemonetics in focus
Haemonetics (HAE) is back on investor radar after U.S. regulators cleared its PerQseal Elite vascular closure system for large bore arterial procedures, expanding the firm’s structural heart tools.
PerQseal Elite lands at a moment when momentum around Haemonetics has been building. The share price is up 52.1% over the past 90 days and 48.5% year to date, while the 1-year total shareholder return of 134.1% points to investors re-rating the business as recent product approvals and the Vivasure Medical acquisition reshape expectations for its structural heart portfolio.
Scan beyond Haemonetics and discover other health-focused companies with similar momentum by reviewing the hand picked list of list of solid balance sheet and fundamentals (25 results).
Haemonetics now trades with a very different profile after a 134.1% 1 year total return and renewed product momentum. Is that surge grounded in business fundamentals, or mostly in changing sentiment as investors reassess valuation?
Most Popular Narrative: 5% Undervalued
Haemonetics closed at $118.73, compared with a widely followed fair value estimate of $124.50 that uses a 7.92% discount rate and incorporates detailed earnings forecasts.
Enterprise wide portfolio transformation that has already lifted adjusted gross margin to 60.3% and adjusted operating margin to 25.4%, together with free cash flow conversion above 100% of adjusted net income over the last twelve months, supports the idea that a richer mix of disposables and software can help maintain net margin resilience and cash generation.
See why 8 investors see Haemonetics as 5% undervalued.
Result: Fair Value of $124.50 (UNDERVALUED)
Still, the Haemonetics story can change quickly if competition in vascular closure affects pricing or if tariff and self-insured medical costs continue to squeeze margins.
Find out about the key risks to this Haemonetics narrative.
Another View: Haemonetics Looks Expensive On Earnings
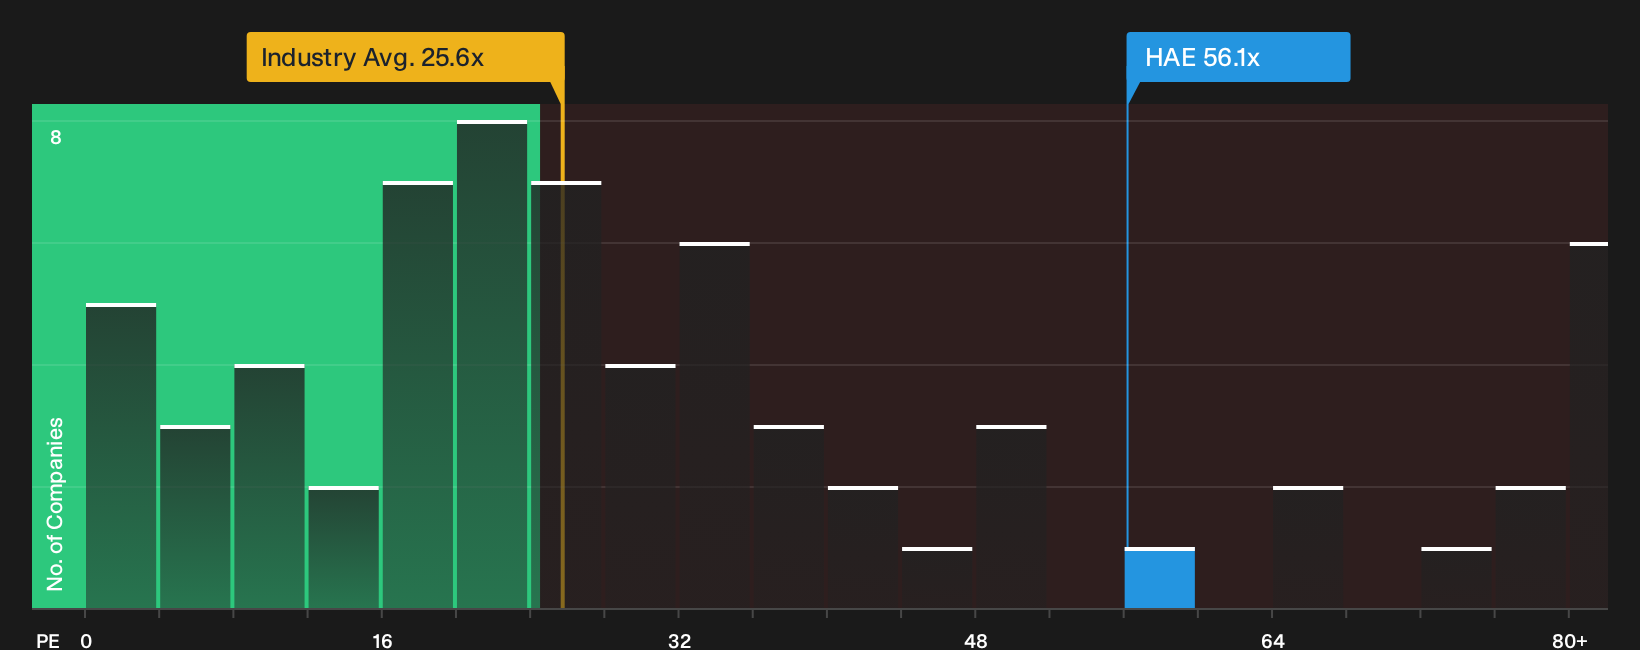
Haemonetics may screen as 34.1% below an estimated fair value using future cash flows, yet the current P/E of 56.1x is more than double the US Medical Equipment industry on 25.3x and sits above both peers at 55x and a fair ratio of 33x. Is the premium multiple a cushion or a vulnerability if sentiment cools?
To see how this earnings based view lines up against a richer set of valuation checks, including that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Haemonetics is clearly strong, yet the mix of risks and rewards behind that optimism deserves your own fresh read before the next move. To see the specific issues investors worry about alongside the upside they are watching, review the 2 key rewards and 3 important warning signs.
Looking for more Haemonetics sized opportunities?
If Haemonetics has your attention, do not stop here. Broaden your watchlist with fresh ideas so you are not relying on a single story.
- Target quality at a discount by scanning companies that combine strong fundamentals with attractive pricing through the 35 high quality undervalued stocks.
- Build a sturdier core to your portfolio by focusing on resilient balance sheets using the 32 resilient stocks with low risk scores.
- Get ahead of the crowd by tracking financially solid businesses that receive less attention through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com