
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Everyone Is Watching OGE Energy (OGE) Today
OGE Energy (OGE) is in focus after its earlier divestment of a 25.5% stake in Enable Midstream, which refocused the group on its regulated utility operations, serving roughly 900,000 electricity customers.
Over the past year OGE Energy has moved more on long term compounding than on short bursts of momentum, with the share price at US$46.72 after a 30 day share price return of 2.66% and a three year total shareholder return of 58.96%. This reflects how investors have responded to its tighter focus on regulated electricity operations and perceived changes in both growth potential and risk since the Enable Midstream exit.
Scan beyond OGE Energy and size up a hand-picked 43 power grid technology and infrastructure stocks that is tightly linked to the same regulated power and grid investment story.
After a steady run to about US$46.72, OGE Energy now raises a practical question for investors. Is it worth stepping in at this level or waiting for a cheaper shot at the same utility story?
Price-to-earnings of 20.7x: Is it justified?
On the valuation side, the current OGE Energy share price of $46.72 lines up with a P/E of 20.7x, which screens as richer than both its estimated fair level and the broader utilities group in the United States.
The P/E ratio compares what investors are paying today for each dollar of earnings. It is especially watched for regulated utilities where growth is usually steady rather than rapid. For a business like OGE Energy that generates, transmits and sells electricity across roughly 30,000 square miles, that earnings multiple effectively signals how the market weighs its earnings profile, regulatory framework and perceived risk against other listed utilities.
OGE Energy trades on a higher multiple than the US Electric Utilities industry average of 20.5x, and it also sits above an estimated fair P/E of 19.1x. That combination points to investors assigning a premium that may be difficult to justify based on this framework alone and it implies a level that valuations could revert toward if sentiment cools.
Explore the SWS fair ratio for OGE Energy.
Result: Price-to-earnings of 20.7x (OVERVALUED)
Still, the OGE Energy story can be knocked off course if regulators tighten allowed returns or if higher borrowing costs reduce what investors are willing to pay.
Find out about the key risks to this OGE Energy narrative.
Another view: OGE Energy through a cash flow lens
The P/E multiple presents OGE Energy as expensive. The SWS DCF model also prices future cash flows at about $36.29 per share versus the current $46.72. That gap suggests investors are already paying a premium for the story, so how comfortable are you with that margin?
Look into how the SWS DCF model arrives at its fair value.
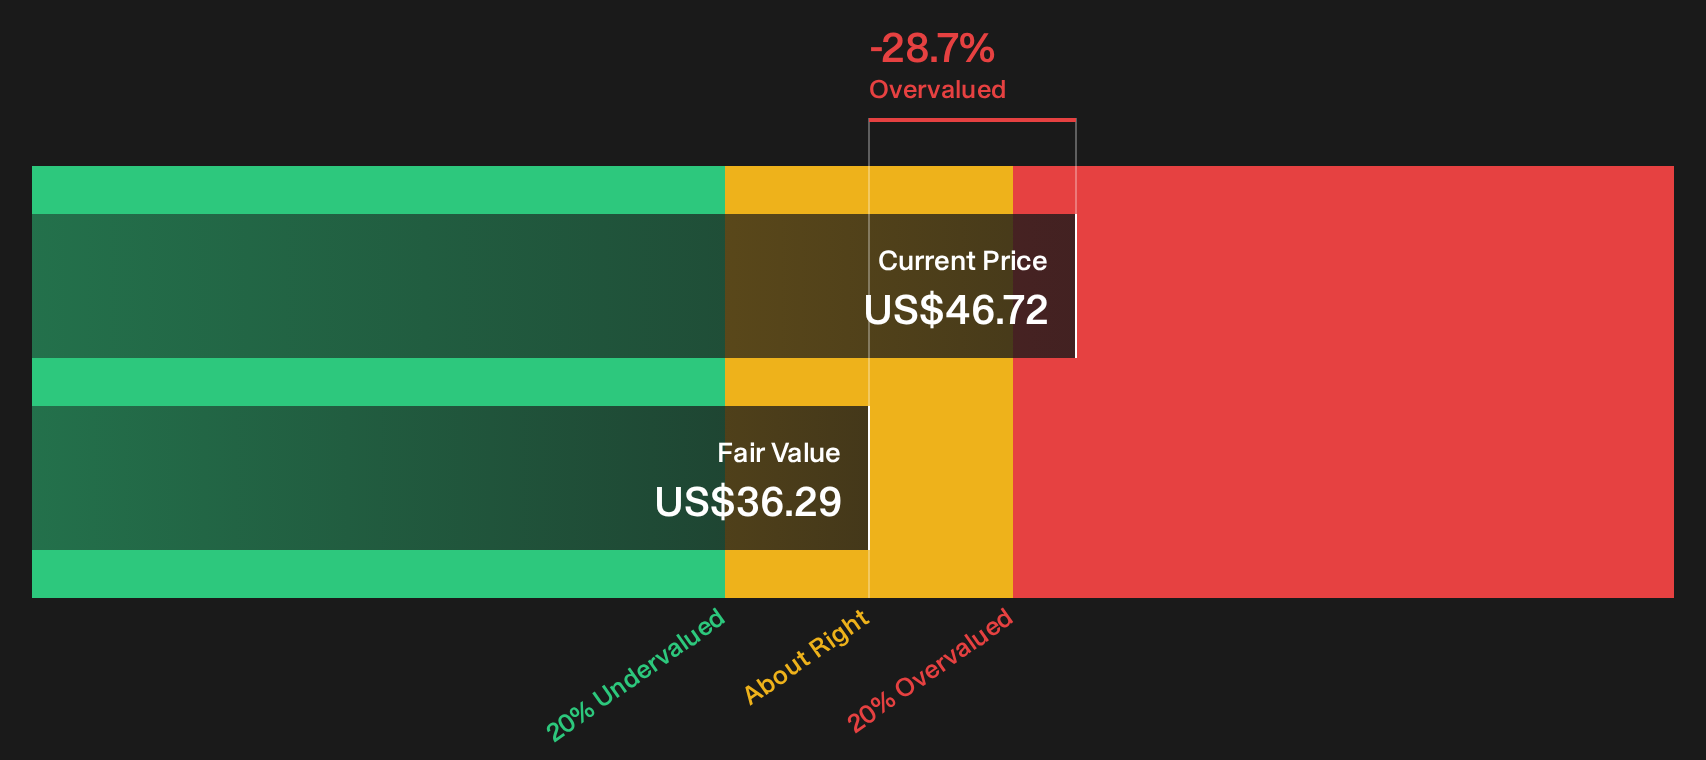
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out OGE Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the data can be useful if you act on them. Weigh OGE Energy's risks against its potential rewards and stress test your own thesis with the 1 key reward and 2 important warning signs.
Looking for more OGE Energy style investment ideas?
If OGE Energy has sharpened your focus on quality utilities, do not stop there. Broader watchlists often surface rewarding ideas before they hit everyone else's radar.
- Target resilient companies with healthy balance sheets and fundamentals through a curated list of solid balance sheet and fundamentals (25 results) that is tailored to investors who care about financial strength first.
- Hunt for quality at a reasonable price by scanning a 35 high quality undervalued stocks that filters for strong businesses trading below their implied worth.
- Prioritise stability and cash returns by reviewing a 8 dividend fortresses built around higher yielding payers with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com