
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
BWX Technologies (BWXT) Could Be 35% Undervalued After Fresh Earnings Optimism
BWX Technologies: Earnings Momentum Draws Investor Attention
BWX Technologies (BWXT) has been getting fresh attention after recent analyst commentary highlighted its long-term sales growth, stronger free cash flow margins, and the possibility of another earnings beat in the upcoming November 2, 2026 report.
The recent excitement around BWX Technologies comes against a sharp pullback in the stock, with the share price down 7.9% over the past month and 21.5% over 90 days. The 1-year total shareholder return has declined 34.2%, yet the 5-year total shareholder return is still up 146.1%. This suggests long-term holders have seen strong gains even as short-term momentum has faded and sentiment adjusts to evolving expectations for growth, risk, and valuation.
Compare BWX Technologies with a curated set of nuclear energy infrastructure peers by reviewing the 16 nuclear energy infrastructure stocks now that earnings expectations and cash flow trends are firmly in focus.
BWX Technologies appears to be a solid nuclear specialist on the business side, yet the share slide and premium to intrinsic estimates point in a different direction. Is the quality already fully baked into today’s price?
Most Popular Narrative: 35% Undervalued
BWX Technologies last closed at $135.83, while the most followed narrative anchors fair value around $209.44. This frames the recent share pullback as a gap between contract visibility and current pricing.
Record backlog of about US$8.4b, supported by a trailing 12 month book to bill ratio of 1.7x and roughly nine quarters of revenue coverage, points to continued conversion of awarded work into higher revenue and earnings for BWX Technologies.
Large long term contracts in special materials, including the US$1.63b high purity depleted uranium award and the US$1.5b Defense Fuels Enrichment program, create a multi year base of work that can support growth in revenue and EBITDA from this national security franchise.
See why 95 investors see BWX Technologies as 35% undervalued.
Result: Fair Value of $209.44 (UNDERVALUED)
Still, BWX Technologies faces real pressure points if U.S. defense budgets reset or if investment in Commercial Operations keeps margins stuck closer to guidance for a longer period.
Find out about the key risks to this BWX Technologies narrative.
Another View: BWX Technologies Through The P/E Lens
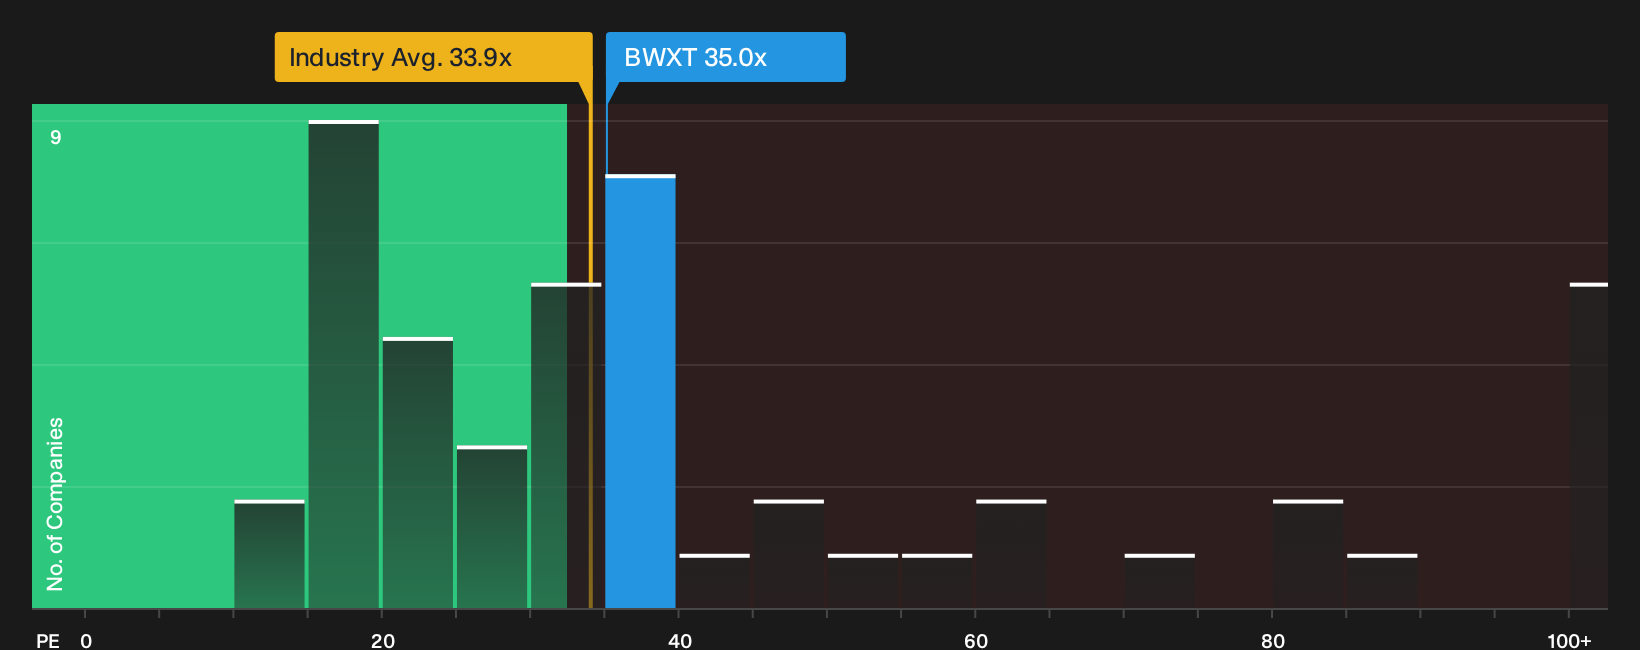
On the flip side of that 35% undervalued narrative, BWX Technologies trades on a P/E of about 35x. That is richer than the US Aerospace & Defense industry at 33.9x, peers at 22.6x, and a fair ratio of 25.3x. Does that premium signal quality or valuation risk?
Our ratios tool lines all of this up in one place so you can judge whether this higher P/E feels justified for your own return hurdles. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on BWX Technologies after all this. If you want to move fast and base your view on data, not headlines, review the 2 key rewards and 1 important warning sign
Looking for more BWX Technologies investment ideas?
Do not stop at BWX Technologies alone. A few minutes with the right stock lists can surface opportunities that match your risk tolerance and income goals more closely.
- Target stronger quality at sensible prices by reviewing the 35 high quality undervalued stocks that pair constructive fundamentals with more modest expectations baked into their valuations.
- Build resilience into your portfolio by scanning the 32 resilient stocks with low risk scores and focusing on businesses with sturdier financial profiles and fewer red flags.
- Hunt for fresh opportunities off the beaten path by checking the 20 high quality undiscovered gems before others start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com