
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Commerzbank Holders Saw Early
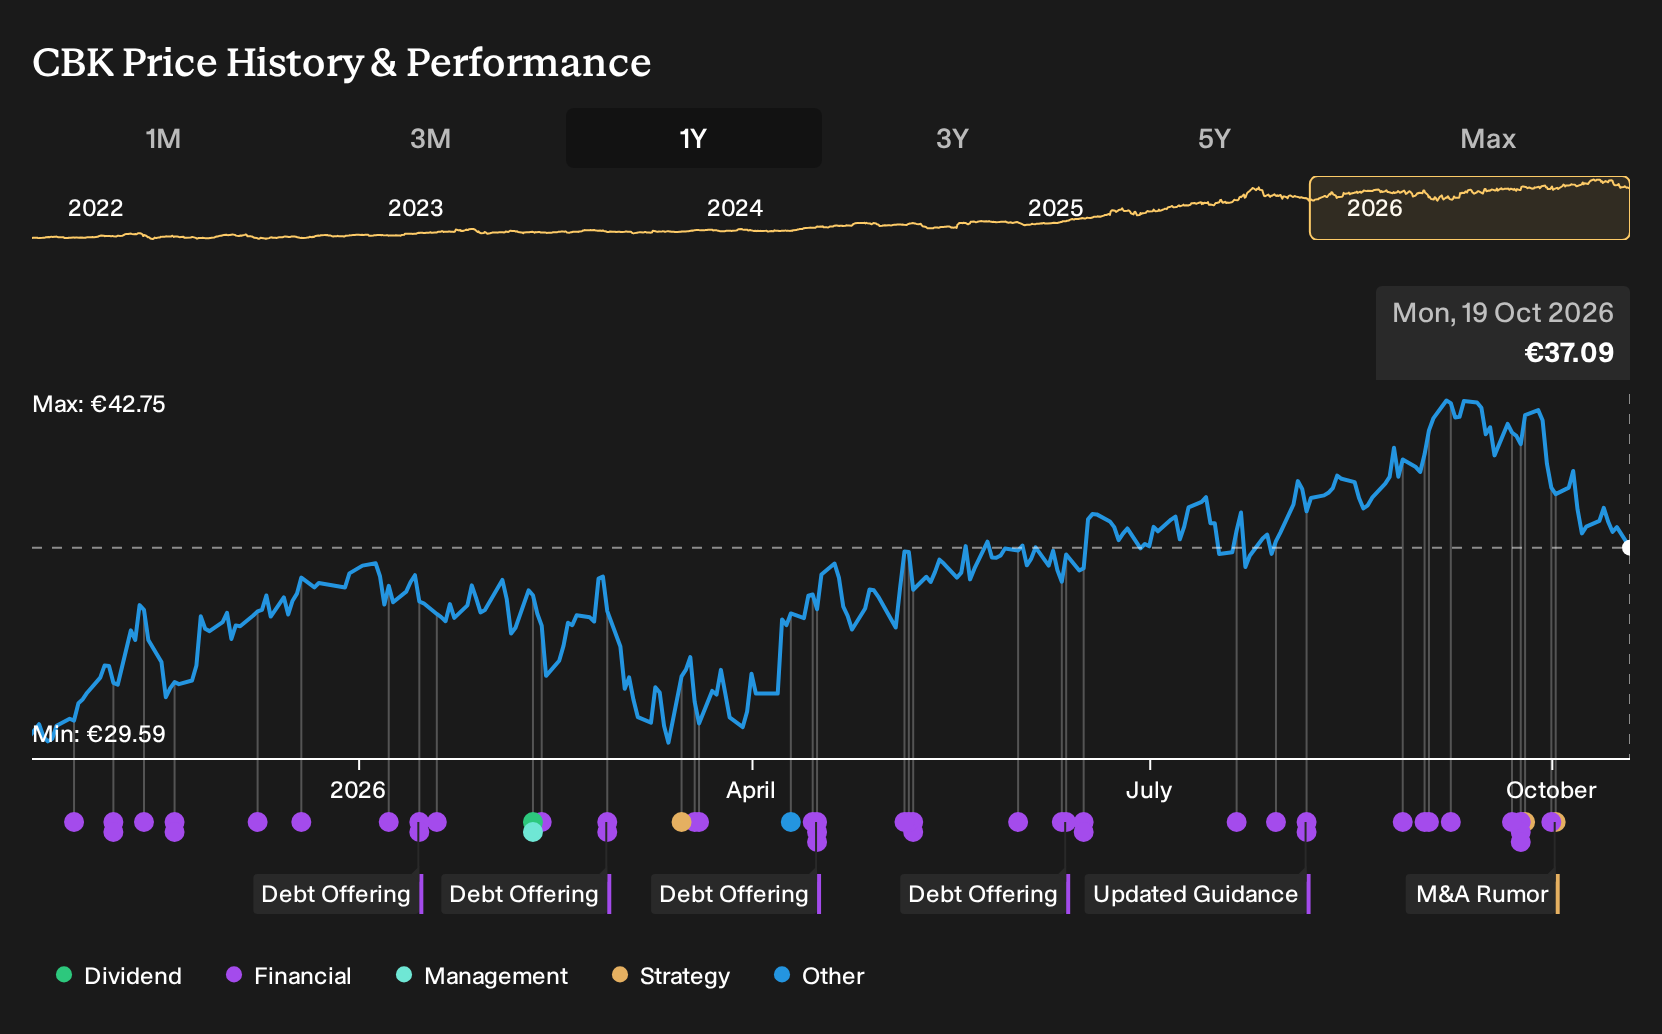
UniCredit’s push to lift its Commerzbank stake beyond 30%, and now toward effective control, turned a long running takeover saga into a concrete path to a merger. Investors who held Commerzbank over the past year are up 26.1%, including dividends. If you had been deciding on 19 October 2025 whether to buy, you would have had to judge one thing: was this contested bank really positioned to earn that kind of outcome before any bid became real?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Commerzbank has already moved. See which of 198 high quality undervalued stocks still trade below our estimates.
The Two Stories Commerzbank Investors Had To Choose Between
The shares cost €29.66 at the start of the period, so any decision on Commerzbank began with that entry ticket in mind. From there, you were really choosing which story about its future you trusted more.
The bullish narrative put Fair Value at €34.62, or 17% above the start price. That camp leaned on rapid digital transformation and faster cost/income ratio improvements, with Commerzbank’s Momentum programme and AI adoption expected to cut costs and support wider net margins.
The bearish view pinned Fair Value at €21, or 29% below the start price. This side focused on fintech competition and heavier Basel IV style regulation as ongoing threats to fee income and profitability, with higher compliance spending seen as a drag on long term returns.
What The Results And Takeover Steps Did To The Commerzbank Story
Record Q2 2026 figures gave Commerzbank bulls real support. Revenue reached €3,131m and net income €681m, with net margin at 21.8% versus 7.3% a year earlier. UniCredit’s stake climbing above 40% and then near 50%, alongside ECB approval for control, challenged the pure standalone bear case. The evidence cut both ways.
The whole decision hinged on whether profitability and efficiency targets were real. For any other bank, track the net margin trend against its cost/income promises and check whether takeover headlines align or clash with management’s stated plan.
What Commerzbank’s One Year Run Already Prices In
Commerzbank now trades at €37.09, after a 26.1% gain over the past year from €29.66. The selected Narrative’s Fair Value sits below the current price, which frames today’s quote as paying up for strong recent earnings and generous capital return plans.
The Narrative’s argument turns on whether deposit pricing, AI driven cost work and UniCredit deal mechanics can support that level. Anyone buying today would be assuming Commerzbank can hold deposit funding together while converting heavy technology and integration spending into lasting efficiency and fee income.
"The current valuation implies the market is pricing Commerzbank as if recent record earnings, high payout plans and capital relief will support a sustained level of shareholder distributions. This narrative views that expectation as too optimistic."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 47% below our estimate - accelerate higher grade ore feed and expand low cost mines to lift cash generation.
- Company 2 - 46% below our estimate - add flagship stores and omnichannel capacity as international shoppers spend more online.
- Company 3 - 43% below our estimate - sell hardware agnostic oncology software as clinics adopt AI driven radiation treatment planning.
Three companies from the same screener. Open the full list of 202 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com