
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Aegon (ENXTAM:AGN) Stock Looks Hard To Call On Redomiciliation News
Aegon has delivered a strong multi year share price run, yet the recent pullback and corporate reshaping now put a sharper spotlight on whether the current valuation lines up with what its earnings can support.
- Over the past 5 years the stock has gained 114.9%, which raises the question of how much of that move is grounded in the underlying profit power of the business.
- The recent redomiciliation to the United States and unified share structure may support clearer capital allocation and earnings visibility, which can influence how much investors are willing to pay for each euro of profit.
- Your read on Aegon is one view; the desks covering it have another. See what analysts think Aegon's shares could be worth.
The issue now is whether Aegon's current share price is adequately explained by its recent earnings profile.
If you want a wider yardstick for assessing whether Aegon's recent earnings justify its price, it can help to line it up against 198 high quality undervalued stocks.
Where Does Aegon Sit on Earnings?
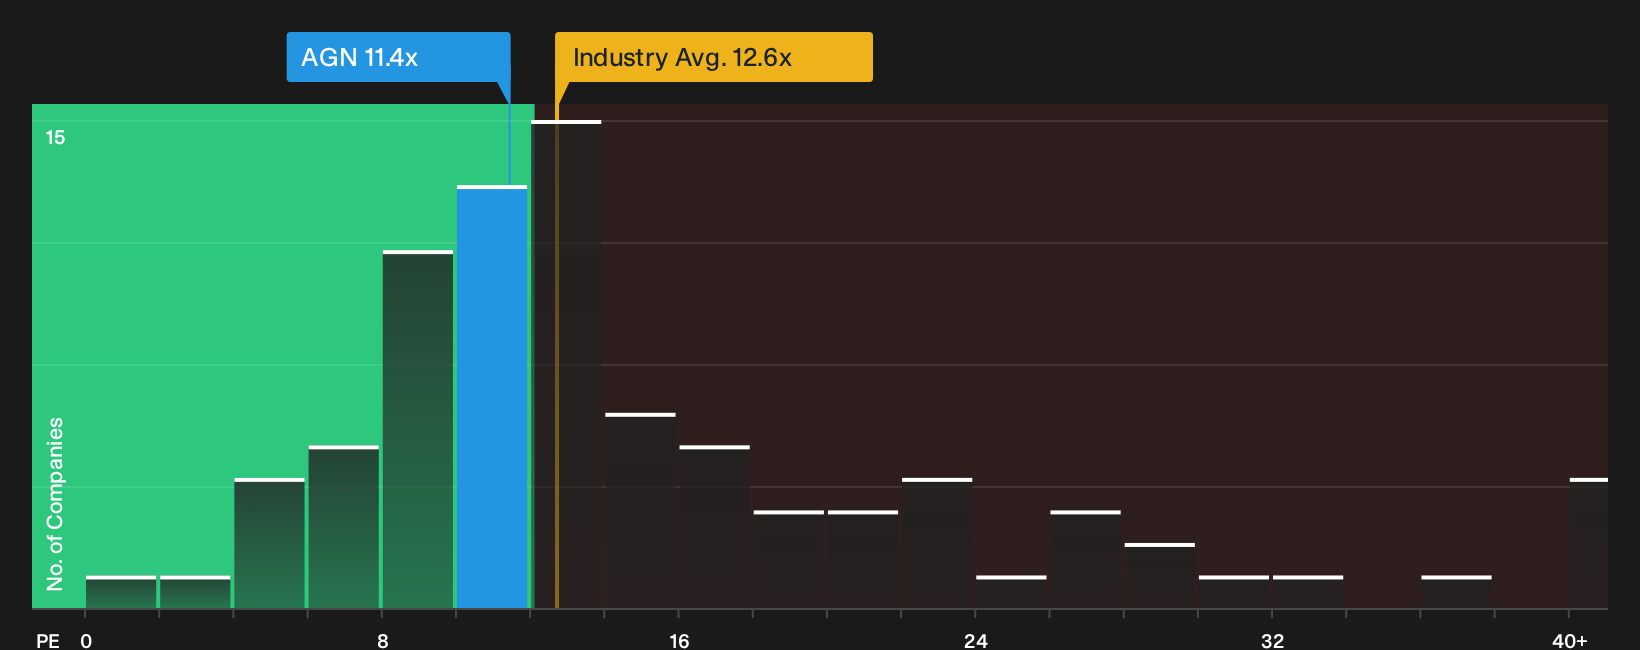
The P/E ratio suits Aegon because earnings remain the key anchor for how investors look at large insurers. On this metric, the stock trades around 11.4x, which is close to the Insurance sector average of about 11.2x and below the peer group on roughly 13.1x. That keeps the headline multiple in a fairly tight band with the rest of the industry rather than flagging a clear outlier in either direction.
Because the recent redomiciliation and share unification can make reported earnings cleaner and governance simpler to read, the current P/E sits near the level that a tailored fair multiple model would expect for Aegon, given its sector, size and risk profile. Even with that restructuring push improving visibility, the market is still valuing the business on only a slight discount to peers. Investors therefore need to decide whether the earnings quality and balance sheet justify paying roughly this kind of multiple. Explore the numbers behind Aegon's P/E valuation.
The Aegon Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Aegon pick up where this valuation puzzle leaves off by spelling out which paths for Aegon's growth, margins and earnings would need to hold for the shares to be worth materially more or less than they trade for today. Each one ties a fair value estimate to a specific mix of potential catalysts and risks so you can track over time which version of events is closest to what actually unfolds on the Community page.
Community views on Aegon split between a U.S. focused transition that could reward patience and a more cautious read on how much is already priced in.
Bull case: 10% undervalued
"The main factor that has to work in Aegon’s favor is successful execution of its U.S. transition and business mix shift..."
Discover why this Narrative puts Aegon at 10% undervalued.
Bear case: 6% overvalued
"The plan to grow U.S. strategic assets while financial assets run off, with CSM in Protection Solutions already at €4.3b and financial assets at €3.2b, increases exposure to assumption changes and experience variances..."
Explore why this Narrative puts Aegon at 6% overvalued.
Before you act on Aegon’s valuation, there is one more lever to examine
Price and earnings only tell part of the story for Aegon, because the people steering the business and the way their rewards are structured can heavily influence how value is created or eroded over time. See who runs Aegon and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com