
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For BlackRock (BLK) Could Change Following Earnings Beat
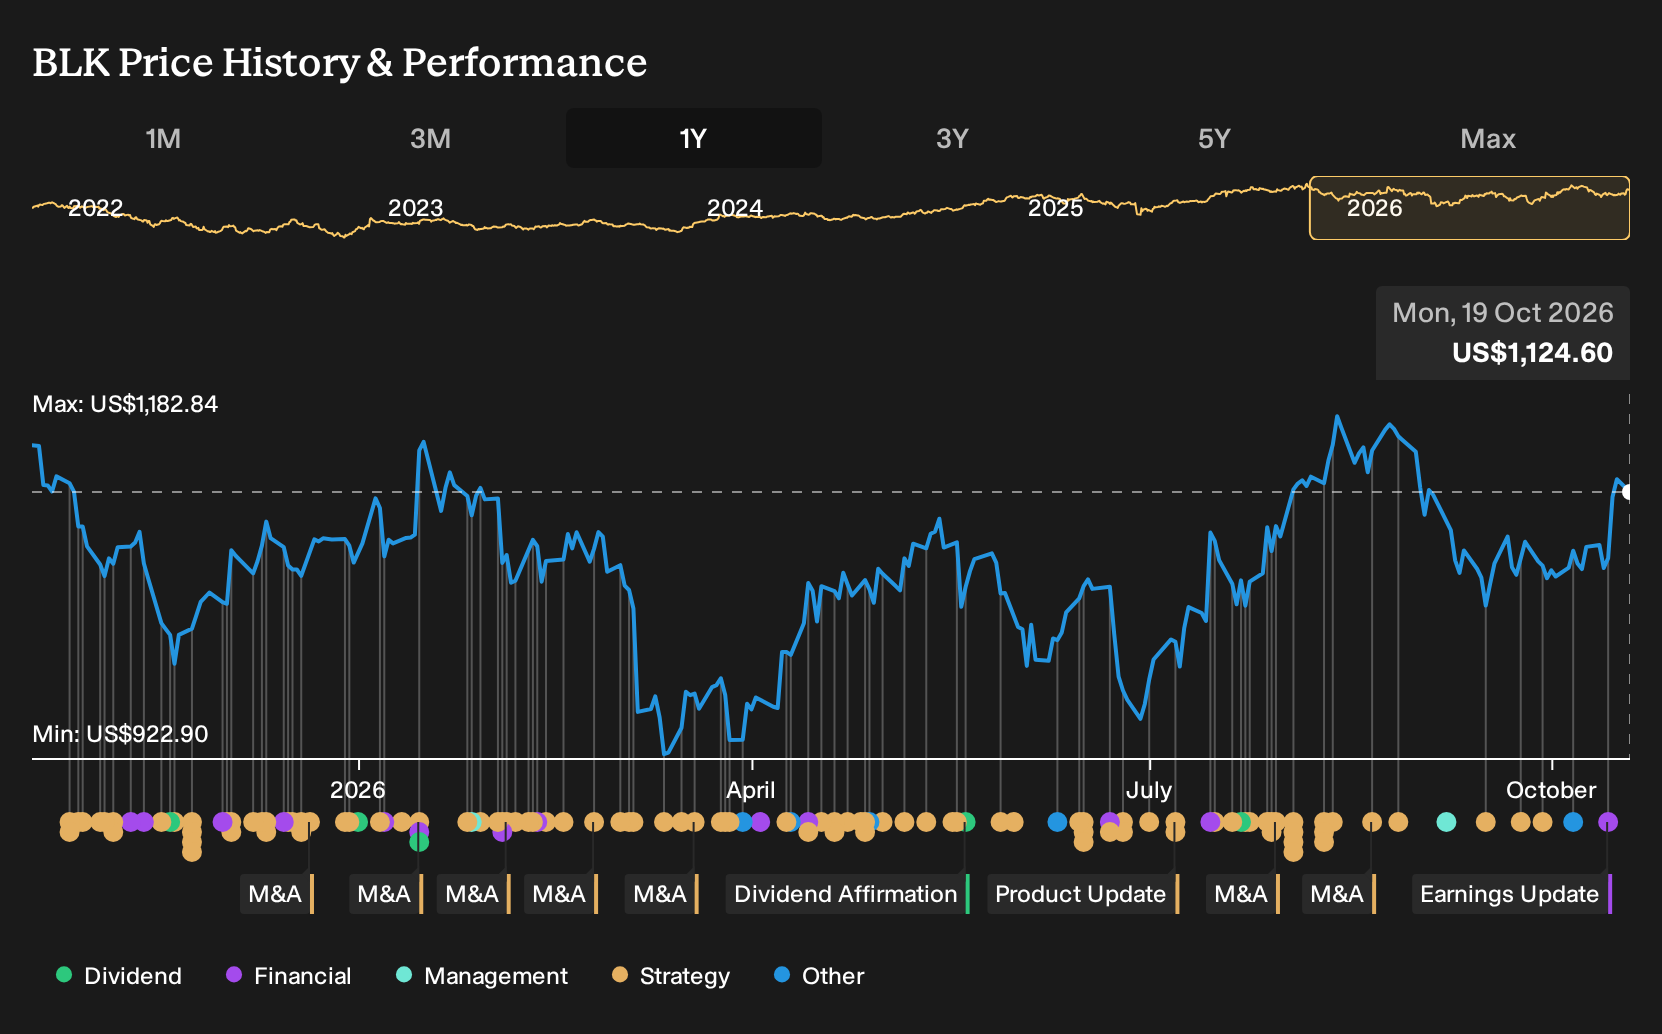
- BlackRock reported third quarter 2026 revenue of US$7,752 million and net income of US$1,659 million, alongside strong ETF and digital asset inflows, including a large single day subscription into its iShares Bitcoin Trust.
- Product development around digital assets, such as the proposed iShares Bitcoin Managed Protection ETF and a growing tokenized money market fund used as collateral, highlights how BlackRock is extending fee streams beyond traditional funds and technology subscriptions.
- The focus now is on how BlackRock's investment narrative intersects with this earnings performance and its expanding digital asset footprint.
Scan how BlackRock’s push into ETFs, Bitcoin products and AI funding compares with other asset managers by zeroing in on 35 high quality undervalued stocks that may be setting up for the next move.
BlackRock Investment Narrative Recap
To own BlackRock, you need to be comfortable with a global fee machine that leans on ETFs, higher fee private markets, technology, and now digital assets. The latest quarter, with US$7,752 million of revenue and US$1,659 million of net income, reinforces that earnings power is tied to scale and product breadth rather than a single segment.
In the near term, the key swing factor is whether flows into ETFs, private markets and Aladdin style technology offset any pressure in lower fee institutional mandates. The biggest risk is that organic base fee growth or operating margins around the high 40% range lose momentum. That would challenge the existing earnings narrative.
The most relevant fresh development for that story is BlackRock’s filing for the iShares Bitcoin Managed Protection ETF. It is designed to give exposure to the iShares Bitcoin Trust through options, with a defined risk profile, instead of holding Bitcoin directly. That fits alongside IBIT’s strong single day inflows and the firm’s broader digital asset build out.
For you as a shareholder, this matters because it adds another potential fee stream that is not tied to traditional market beta and could deepen BlackRock’s role in digital infrastructure. It also brings execution risk. Liquidity, derivative management and regulatory scrutiny all need to be handled cleanly for this product set to support, rather than dilute, the ETF and technology led catalysts already in play.
Analysts sketch out a BlackRock narrative that targets US$35.7b in revenue and US$10.7b in earnings by 2029. This outlook is built on 7.8% yearly top line growth and an earnings increase of about US$3.8b from the US$6.9b reported today.
Uncover how BlackRock's fair value indicates a 17% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between US$1,266.75 and US$1,339.65. This illustrates how closely some retail investors align in their views on BlackRock. However, there is still wide uncertainty. ETF, private markets and digital asset execution risks on one side, and AI infrastructure or Bitcoin ETF catalysts on the other, mean opinions can differ sharply. Explore multiple viewpoints before deciding where you sit in that spread.
Explore 3 other BlackRock fair value estimates, including one that suggests as much as 19% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BlackRock research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BlackRock. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BlackRock's overall financial health at a glance.
Looking For More Ideas Beyond BlackRock?
If you want to stress test your thesis on BlackRock against what else is out there, cast the net wider with the Simply Wall St Screener and see how other opportunities stack up on quality, income and risk.
- For investors who want income with resilience, scan for companies that line up as 8 dividend fortresses and see which ones match your payout and stability preferences.
- If capital preservation matters as much as upside, filter for 32 resilient stocks with low risk scores to find businesses that may better fit a steadier return profile.
- When you are hunting for something off the beaten path with strong fundamentals, shortlist ideas from 20 high quality undiscovered gems and compare them to BlackRock's risk reward trade off.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com